


Armour Residential REIT Inc. (ARR)



Armour Residential REIT (ARR) Q2 Earnings and Revenues Surpass Estimates
Armour Residential REIT (ARR) came out with quarterly earnings of $0.72 per share, beating the Zacks Consensus Estimate of $0.69 per share. This compares to earnings of $0.77 per share a year ago.
Armour Residential REIT: A High-Yield But Volatile Idea For Income Investors
ARMOUR Residential REIT gets is prior hold ratings reaffirmed again, ahead of its upcoming earnings results later this month. Positive notes include an agency-backed MBS portfolio with growth, as well as positive ROE trends. Some riskier factors include volatile earnings and operating cash flow, high D/E, weak market sentiment, and limited upside forecasts.
Cellebrite: Stronger Fundamentals Support A Buy Rating
Cellebrite (CLBT) remains a buy as fundamentals strengthen, with FedRAMP High achieved and federal demand reaccelerating. Q2 ARR guidance of $510–513M implies 22–23% growth, supporting a narrative of renewed momentum post-federal softness. Platform adoption advances, with Inseyets conversions near 60% and growth products now 14% of ARR, lengthening CLBT's growth runway.
Palo Alto Networks: The Market Is Pricing 2030 At 12x
Palo Alto Networks is a long-term Buy, supported by 28% organic NGS ARR growth and robust AI-driven portfolio expansion. NGS ARR headline growth (+60%) is acquisition-boosted; organic growth is 28%, with new net recurring ARR up 18%. RPO growth of 22% organically signals deepening customer commitments and validates PANW's integrated platform strategy.
Alkami Technology Touts $500M ARR, AI Upside and Bank Demand at Fintech Event
Alkami Technology NASDAQ: ALKT executives outlined the company's growth strategy, financial outlook and market positioning during a William Blair fintech and payments event, emphasizing demand from regional banks and credit unions seeking digital capabilities comparable to large banks and fintechs.
The Smartest AI Money Is Buying Nebius
Leopold Aschenbrenner disclosed a 5.6% stake after Microsoft, Meta, and Nvidia validated Nebius operationally and financially. Q1 revenue surged 684% YoY to $399 million, while Nebius AI EBITDA margins expanded sharply to 45%. Management projects annualized ARR reaching $7 billion to $9 billion despite current ARR sitting near $1.9 billion.
Palo Alto Networks: Why $6 Billion In ARR Is Just The Beginning
Palo Alto Networks, Inc. remains a Strong Buy as new catalysts reinforce my long-term bullish thesis. PANW consistently beats analyst expectations, with 15% revenue and 27% EPS growth year-over-year, justifying its premium valuation. Sticky customer relationships, platform unification, and robust RPO/ARR growth signal a strengthening competitive moat.
Fair Isaac Q2 Earnings Beat Estimates on Scores, Revenue Up Y/Y
FICO tops Q2 estimates as revenue surges 39%, fueled by booming mortgage activity and strong Scores segment growth, prompting a raised full-year outlook.
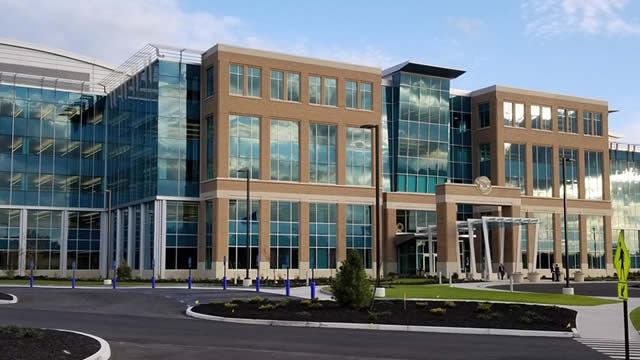
Armour Residential REIT (ARR) Upgraded to Buy: Here's What You Should Know
Armour Residential REIT (ARR) has been upgraded to a Zacks Rank #2 (Buy), reflecting growing optimism about the company's earnings prospects. This might drive the stock higher in the near term.

Amazon Q1: $200B In FY26 CapEx For A $15B Run-Rate Story
In my view, $15B in Amazon.com, Inc.'s AWS AI services ARR is not enough to justify a $200B FY26 CapEx plan. At least, not yet. I want to see AWS AI services ARR increase significantly over the next few quarters, since it still represents only 10% of AWS's run rate. AWS grew 24% in Q4, and I want to see Q1 revenue coming in clearly above the $36.8B consensus.

ARMOUR Residential REIT, Inc. (ARR) Q1 2026 Earnings Call Transcript
ARMOUR Residential REIT, Inc. (ARR) Q1 2026 Earnings Call Transcript
Docusign Bottoms And Delivers Renewed Growth Prospects - Reiterate Buy
DOCU's new IAM offerings are driving robust ARR growth, a growing customer base, higher net retention rates, and improved international monetization trends. Management guides for IAM to reach 18% of total ARR by FY2027 (+7.2 points YoY), with reinvestments in R&D expected to accelerate their product roadmap. Thanks to the SaaSpocalypse, DOCU now offers a deep value Buy opportunity at a P/E of 10.78x and a 3Y PEG of 0.84x, along with compelling upside potential to LTPT of $59.20.


