


Simpson Manufacturing Co., Inc. (SSD)



Wall Street Analysts Believe Simpson Manufacturing (SSD) Could Rally 25.06%: Here's is How to Trade
The average of price targets set by Wall Street analysts indicates a potential upside of 25.1% in Simpson Manufacturing (SSD). While the effectiveness of this highly sought-after metric is questionable, the positive trend in earnings estimate revisions might translate into an upside in the stock.
Is the Options Market Predicting a Spike in Simpson Manufacturing Stock?
Investors need to pay close attention to SSD stock based on the movements in the options market lately.
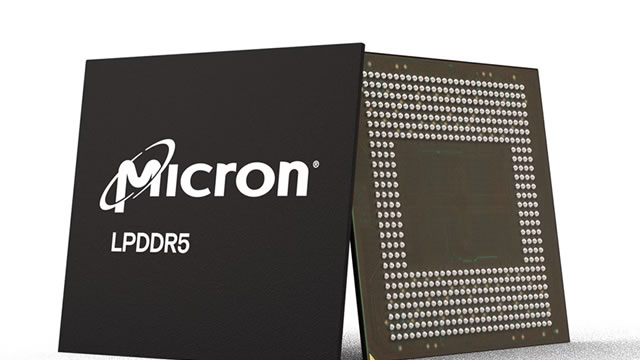
Micron Buried One Sentence About Dec. 9 - It Could Begin Retiring 12% Of Its Shares
Micron remains a Strong Buy, driven by underappreciated SSD/NAND growth and strategic capital return catalysts beyond the AI/HBM narrative. MU's data center SSD revenue surpassed $5B in a quarter, doubling sequentially, with AI-driven demand and pricing power fueling record NAND results. The company's $24.4B net cash and CHIPS Act buyback restrictions lift in December 2026, enabling significant MU share repurchases and enhanced capital returns.
Can Silicon Motion's New MonTitan SSD Solution Drive Growth?
Silicon Motion Technology Corporation SIMO has strengthened its footprint in the evolving artificial intelligence (AI) infrastructure market by introducing its MonTitan SSD Reference Design Kit (RDK). The new platform is designed to deliver high performance, predictable latency and sustained data processing to meet the demanding storage requirements of Agentic AI workloads.
CRWV's Solidigm Deal: Can Priority SSD Access Give an Edge in AI Cloud?
CoreWeave's Solidigm deal secures priority SSD access, helping align storage capacity with its expanding AI infrastructure needs.
Sandisk Just Announced Its Next Game Changer
Sandisk Corporation's latest progress on its HBF roadmap is expected to complement the QLC SSD ramp and impending transition to BiCS10 TLC SSD, strengthening its share of the accelerating NAND supercycle. Specifically, the first OCP technical specifications disclosed for HBF, alongside participation from Google, marks a meaningful step towards commercialization, underscoring incremental upside to its fundamental outlook. HBF remains critical in expanding Sandisk's role in the AI memory hierarchy, adding up to 512GB of high-bandwidth near-compute NAND capacity for inference-intensive agentic workloads.

Simpson Manufacturing Co., Inc. (SSD) Q2 2026 Earnings Call Transcript
Simpson Manufacturing Co., Inc. (SSD) Q2 2026 Earnings Call Transcript
Simpson Manufacturing Q2 Earnings Call Highlights
Simpson Manufacturing NYSE: SSD reported second-quarter 2026 net sales of $671.1 million, up 6.3% from the prior-year period, as pricing actions, favorable mix and foreign exchange more than offset modestly lower sales volumes.
Simpson Manufacturing (SSD) Beats Q2 Earnings and Revenue Estimates
Simpson Manufacturing (SSD) came out with quarterly earnings of $3.09 per share, beating the Zacks Consensus Estimate of $2.72 per share. This compares to earnings of $2.47 per share a year ago.

Strength Seen in Simpson Manufacturing (SSD): Can Its 4.4% Jump Turn into More Strength?
Simpson Manufacturing (SSD) was a big mover last session on higher-than-average trading volume. The latest trend in earnings estimate revisions might not help the stock continue moving higher in the near term.

AI Storage Boom Aids NAND Demand: Can Micron Capitalize on the Trend?
MU's NAND revenues surge on AI-driven data center SSD demand, as disciplined supply and advanced SSD launches bolster its storage growth outlook.

Simpson Manufacturing Co., Inc. (SSD) Presents at 16th Annual Wells Fargo Industrials & Materials Conference Transcript
Simpson Manufacturing Co., Inc. (SSD) Presents at 16th Annual Wells Fargo Industrials & Materials Conference Transcript


