


XPeng Inc. (XPEV) Q1 2026 Earnings Call Transcript
XPeng Inc. (XPEV) Q1 2026 Earnings Call Transcript
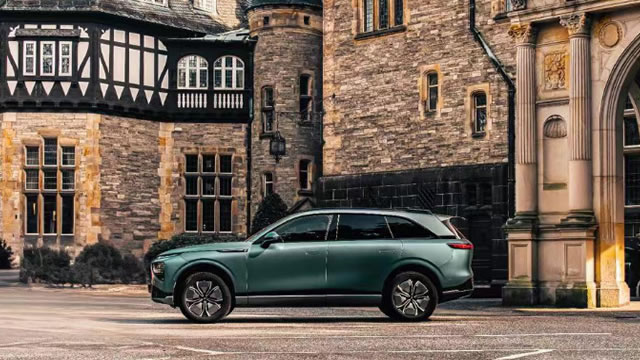
XPeng's Robotaxi Dream Doesn't Save It From EV Market Collapse
Xpeng (XPEV) faces declining deliveries and revenues, with Q1 2026 vehicle deliveries down 33.3% year-over-year and revenues falling 17.6%. Despite margin improvements to 20.6%, XPEV swung to a net loss of RMB 1.78 billion, driven by higher R&D and lower volumes. Management projects a Q2 rebound with 100,000–106,000 vehicle deliveries and RMB 19.6–20.8 billion in revenue, banking on new model launches.
XPENG Q1 Earnings Call Highlights
XPENG NYSE: XPEV said it expects a sharp rebound in second-quarter deliveries after a weaker first quarter, while management outlined a broader push to position the company around “physical AI” applications including advanced driver assistance, Robotaxis and humanoid robots.
XPeng Posts Loss as Revenue Slumps Despite Stronger Margins
Chinese electric-vehicle maker XPeng had a weak start to 2026, slipping back to a loss in the first quarter after becoming profitable at the end of last year.
China's Xpeng begins mass production of robotaxis in Guangzhou
Chinese electric vehicle maker Xpeng said on Monday it had begun mass production of its first robotaxi at its Guangzhou headquarters, targeting fully driverless operations by early 2027.

XPeng: Near-Term Growth Pains Meet Solid, Diversified Prospects - Reiterate Buy
XPeng faces near-term delivery and margin headwinds from changing EV regulations and elevated investment/capex guidance, with Q1'26 revenue and earnings likely to be soft. International expansion, autonomous driving, SaaS monetization, & ambitious robotics/flying car initiatives underpin its multi-pronged growth prospects, targeting multi-trillion dollar markets. XPEV trades at a compelling forward EV/Sales of 1.07x with a 3Y revenue growth at a CAGR of +21.5%, aided by the strong balance sheet and positive cash flows.

China's Xpeng expects full-scale delivery of 'flying' cars in 2027
Chinese electric car maker Xpeng expects full-scale delivery of 'flying' cars in terms of volume production next year, its president Brian Gu said in an interview on Thursday.

XPeng: Looks Like A Tesla That Keeps Its Promises, Long-Term Strong Buy
XPeng Inc. is a Strong Buy, reflecting robust execution, milestone achievement, and strategic AI-driven growth. XPEV demonstrates superior operational continuity, highlighted by successful launches, rapid AI SoC deployment, and a landmark Volkswagen partnership. Despite guiding for Q1 2026 revenue and delivery declines, XPEV's financial strength, profitability trajectory, and attractive valuation underpin the bullish thesis.
XPeng: Margin Inflection Point Reached
XPeng Inc. is a fast-growing, innovative Chinese EV OEM, now achieving positive EBITDA and scaling rapidly in a highly competitive market. I maintain a Buy rating, targeting $31 for YE27 (64% upside), based on strong volume growth, margin expansion, and over 60% forecasted earnings growth for 2026-2028. Robotaxi and robotics initiatives offer additional upside optionality, though competition, price wars, and tariff risks remain material.

XPeng: Q4 Net Profit, Leading Gross Margins, Cheap
XPeng achieved its first-ever GAAP net profit in Q4, marking a significant turnaround and improved investment setup. Q4 saw strong delivery momentum, especially for the Mona brand, driving 38.2% year-over-year revenue growth to $3.18B. Despite a slight margin contraction to 13%, I reaffirm my buy rating on XPEV, citing upside risk skew from delivery growth.

XPeng Inc. (XPEV) Q4 2025 Earnings Call Transcript
XPeng Inc. (XPEV) Q4 2025 Earnings Call Transcript

XPeng Drops 5%: Is This Tesla Rival's Autonomous Driving Bet Enough to Justify the Risk?
XPeng (NYSE:XPEV) stock is down 5% in early trading on Friday, sliding toward $18 after closing at $19.15 the day prior.


