


Star Group L.P. (SGU)
 NYSE NYSE Primary

Star Bulk Carriers: Strong Rates Could Sustain A Yield Above 10%, But Risks Remain
Star Bulk Carriers offers high spot market exposure, creating significant upside if dry bulk rates remain strong. SBLK's shrinking, modernizing fleet and opportunistic asset sales have unlocked book value and improved balance sheet strength. Q2 is poised for robust EPS and a dividend yield above 10%, with management's new policy targeting 100% of post-amortization operating cash flow.
Star Bulk Carriers: Rich Dividends, Healthier Balance Sheet, And Fleet Renewal - Promising Industry Tailwinds
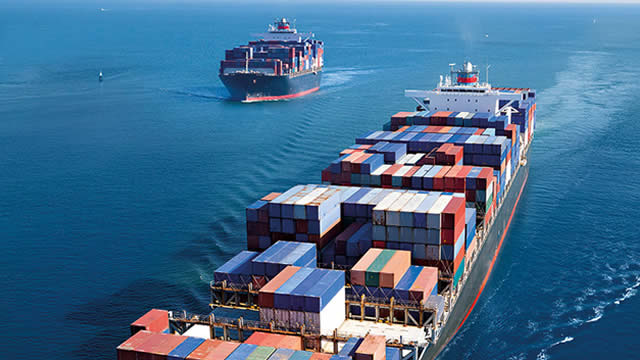
Star Bulk Carriers' elevated spot rates, especially for Ultramax/Supramax and Newcastlemax/Capesize vessels, may drive SBLK's robust FCF generation in FQ2'26. The healthier balance sheet at a net debt/annualized adj EBITDA ratio of 1.18x provides flexibility for disciplined fleet renewal across older fleet sales and new shipbuilding. These developments may have contributed to the updated dividend policy, at which they 'distribute 100% of free cash flow,' aided by the accretion from the ongoing share repurchases.
Five Star Bancorp: A CRE-Focused Bank With An Exemplary Track Record
Five Star Bancorp demonstrates robust earnings growth, driven by disciplined underwriting and a high-quality, expanding loan book. FSBC's focus on manufactured home communities and RV parks, with low average CRE LTV ratios (49%), limits risk despite sector concerns. The bank's strong asset growth and low loan loss provisions support a premium valuation above 2x tangible book value and a 13x earnings multiple.

‘The Boroughs' Star Has No Idea Why Netflix Cancelled The Hit Show
It's not every day you see Netflix cancel a series with solid viewership and something as high as a 97% Rotten Tomatoes score. But that's what's happened with The Boroughs, which only just fell off the service's top 10 list as recently as this past week, almost a month after its debut.

Here's Why Investors Should Bet on Star Bulk Carriers Stock Now
SBLK gains from a 16-vessel acquisition, stronger liquidity and continued dividends as earnings estimates move higher.

Spotify's "North Star" Outlook Was Music to Investors Ears
Shares of the world's most dominant player in music streaming, Spotify Technology NYSE: SPOT, have come under significant pressure in the past 52 weeks. In June of last year, Spotify hit its all-time highs, trading well above $750.

Star Bulk Carriers: New Dividend Policy Unlocks A 15% Yield
Star Bulk Carriers Corp (SBLK) has outperformed, appreciating over 40% and consistently beating earnings estimates while enhancing its dividend policy. SBLK now pays 100% of free cash flow as dividends when cash exceeds $2.1M per vessel, reflecting disciplined capital allocation as the stock approaches NAV. Strong Q2 guidance, robust rate environment, and a solid balance sheet support expectations for materially higher earnings and dividends in coming quarters.
Is the Options Market Predicting a Spike in Five Star Bancorp Stock?
Investors need to pay close attention to FSBC stock based on the movements in the options market lately.

Northern Star: CEO Exit Creates A High-Potential Turnaround Opportunity
Northern Star Resources Limited remains a Buy, offering strong turnaround potential amid CEO transition and gold's long-term repricing prospects. NESRF's operational setbacks led to guidance cuts and a sharp stock decline, but projects like the KCGM mill expansion and Hemi support future production growth. The company's robust balance sheet—A$320 million net cash after dividends and a new A$500 million buyback—reinforces its financial resilience.

Disney Reveals Star Wars Spinoff ‘Ahsoka' Is 30% Cheaper Than ‘The Acolyte'
Pre-production of the second season of Star Wars streaming show Ahsoka cost around 30% less than the sum spent on its counterpart The Acolyte according to recently-released filings.

‘The Mandalorian and Grogu' opens below ‘Solo' in weakest Disney-era ‘Star Wars' debut
“The Mandalorian and Grogu” hauled in an estimated $82 million domestically over its first three days in theaters, according to CNBC.

‘The Mandalorian and Grogu' Returns Star Wars to Theaters With $102 Million
The film based on a hit Disney+ series is the first new Star Wars film since 2019.


