


Tesla, Inc. (TSLA)




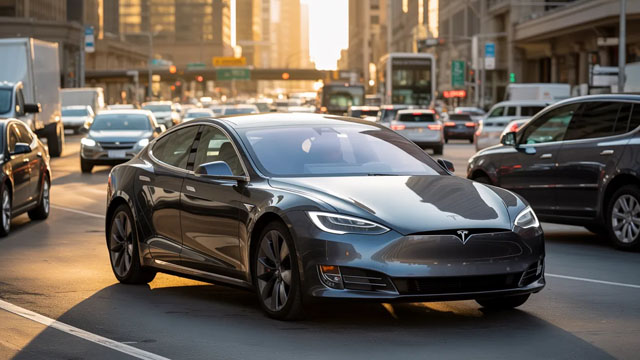
Tesla plans next-generation Roadster reveal after almost a decade of delays
Tesla plans to reveal its next-generation Roadster from a SpaceX test site in Texas. CEO Elon Musk first debuted the Roadster refresh concept in 2017 but Tesla has since missed every targeted delivery date.
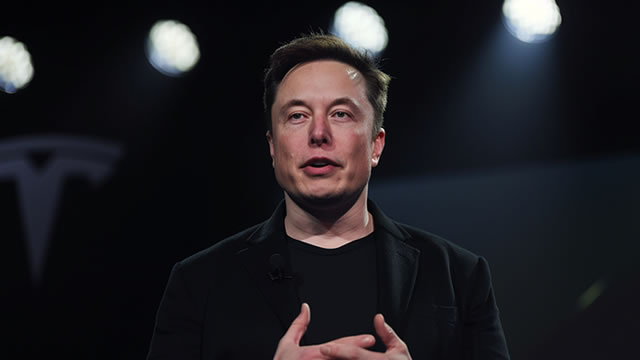
Tesla's long-awaited Roadster gets its moment after years of delays
Tesla's redesigned Roadster debuts at a SpaceX test site in Texas, nearly nine years after Elon Musk first previewed the electric sports car.
Tesla Stock Has a Huge Valuation. Here's What It Would Take to Justify It
Tesla trades at multiples that make traditional automakers look like bargain bins, and whether that premium survives depends on a set of bets that have never been more consequential or more uncertain.
Tesla's Volatility Is Tempting Investors Again at $375
Tesla just posted record deliveries and sits on a $43 billion cash pile, yet margins are crumbling and free cash flow turned negative.
TSLA's Megapack Order Highlights AI Demand and Future Growth Potential
Tesla's 1 GWh Megapack order from Apollo Power highlights rising AI data center storage demand, but undisclosed deal value and pending commitments limit revenue visibility.
Tesla Cybertruck sales top 70,700 since 2024
Despite a sharp slowdown following their first full year on the market, Tesla's Cybertruck sales have reached an estimated 70,788 units in the United States between January 2024 and the end of the third quarter of 2026.
Tesla set to unveil next generation Roadster sports EV after years of delay
Tesla set to unveil next generation Roadster sports EV after years of delay
The 1 Thing I'd Want Elon Musk to Answer on Tesla's Oct. 21 Call
Tesla's adjusted earnings per share dropped 18% year over year in the second quarter, to $0.33. Tesla expects capital spending of over $25 billion in 2026.
Tesla Wants to Make Its Own Chips—What Could Go Wrong?
Elon Musk has never been one to think small, and his latest ambition might be one of his boldest ideas yet. Tesla Inc. NASDAQ: TSLA, the electric-vehicle giant increasingly being pitched as an AI and robotics company, is no longer content to design its own chips.
The Tesla Story Is Falling Apart, And A Flying Roadster Won't Save It
Tesla, Inc. remains rated Strong Sell due to extreme valuation, weak margins, and negative free cash flow despite recent delivery and revenue beats. Q2 revenue rose 26% YoY, but operating margin collapsed to 1.4% and free cash flow was negative ~$1.1 billion, with CapEx surging and new debt facilities secured. Automotive gross margin excluding credits fell to 16.3%, energy margins halved, and GAAP net income was heavily reliant on mark-to-market gains from SpaceX holdings.
Tesla: The Robotaxi Dream Meets An Earnings Reality Check
Tesla, Inc. remains rated Hold with an $406.50 price target, reflecting only 8% upside and an uncompelling risk/reward at a premium valuation. Q3 vehicle deliveries exceeded expectations but remain 2% below last year; automotive earnings face margin, pricing, and regulatory-credit risks. Battery storage is a credible diversification, but Q3 deployments missed expectations by 14% and margin sustainability is uncertain amid competitive and tariff pressures.
Earnings Preview: Tesla (TSLA) Q3 Earnings Expected to Decline
Tesla (TSLA) doesn't possess the right combination of the two key ingredients for a likely earnings beat in its upcoming report. Get prepared with the key expectations.


