


Advanced Micro Devices, Inc. (AMD)





AMD shares rise after unveiling $6B stock buyback plan
Advanced Micro Devices Inc (NASDAQ:AMD, ETR:AMD) shares were up 5.1% in early trading on Wednesday after the chipmaker unveiled a new $6 billion share repurchase program, expanding its total buyback authorization to about $10 billion. The announcement comes as a number of semiconductor firms seek to return capital to shareholders amid signs of cooling investor enthusiasm for the artificial intelligence boom that has driven up valuations across the sector.
Chip Stock Surges on Share Buyback, Saudi Arabia Deal
Shares of Advanced Micro Devices Inc (NASDAQ:AMD) are up 7.2% at $120.53 at last glance, after the semiconductor company announced a $6 billion share buyback program.
AMD announces $6 billion buyback; shares climb 8%
AMD announces $6 billion buyback; shares climb 8%
AMD Stock Rises. Buyback News, and More, Boosts AI Chip Maker.
AMD was rising on an expanded stock buyback program and prospective sales of chips to Saudi Arabia.
AMD Will Never Match Nvidia, And That's Why It's A BUY (Upgrade)
I am upgrading AMD to a BUY due to an attractive valuation and upcoming catalysts such as China trade war de-escalation and a new AI hardware cycle. AMD trails Nvidia in AI chip technology, with data center growth at 39% YoY (Q1) versus Nvidia's 427%, but its focus on memory and bandwidth is promising. AMD doesn't need to match Nvidia's pace; even modest AI inference gains and niche success can drive outsized returns of up to 10X from current share prices.
Qualcomm Is 5x Cheaper Than AMD, but Won't Be for Long
Qualcomm Inc. NASDAQ: QCOM closed at its highest level in more than a month on Monday night, continuing a solid recovery from its post-earnings dip two weeks ago.
Advanced Micro Devices, Inc. (AMD) Is a Trending Stock: Facts to Know Before Betting on It
Zacks.com users have recently been watching Advanced Micro (AMD) quite a bit. Thus, it is worth knowing the facts that could determine the stock's prospects.
Nvidia, AMD help the chip sector to its highest close since February
One analyst says it's now time to go ‘back to fundamentals' on Nvidia's stock
AMD Is Quietly Catching Nvidia - Wall Street Just Doesn't See It Yet
AMD reported strong Q1 results, with YoY gross profit up 46%, despite sequential revenue decline due to seasonality. AI demand, new product launches, and easing China tariffs position AMD for potential outperformance. AMD's valuation at 18x 2026 earnings suggests room for growth, with a potential rally if it clears the $115 resistance.
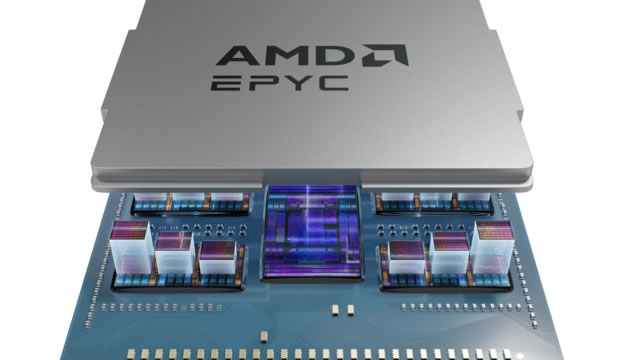
AMD: Strong Upside Potential If U.S.-China Trade Talks Turn Constructive
AMD's 1Q FY2025 revenue topped the high end of its previous guidance, with strong margin expansion resulting in 55% YoY growth in non-GAAP EPS. The weak 2Q FY2025 outlook is largely impacted by the inventory write-off due to the MI308 chip ban in China. FY2025 remains a YoY growth rebound year, even considering the $1.5 billion revenue headwind from China, with Gaming and Embedded contributing positive YoY growth.
AMD: Potential To Double Its Valuation
AMD beat Q1 EPS and revenue estimates, driven by strong Data Center demand and AI accelerators, signaling undervaluation despite negative sentiment. AMD's free cash flow surged 92% Y/Y, growing 2.6x faster than revenue, highlighting improved profitability from Data Center and AI accelerator sales. AMD also continued to make gross margin gains and the chipmaker confirmed that it is going to accelerate production/shipments of its next-gen MI350 series Instinct GPU in mid-2025.
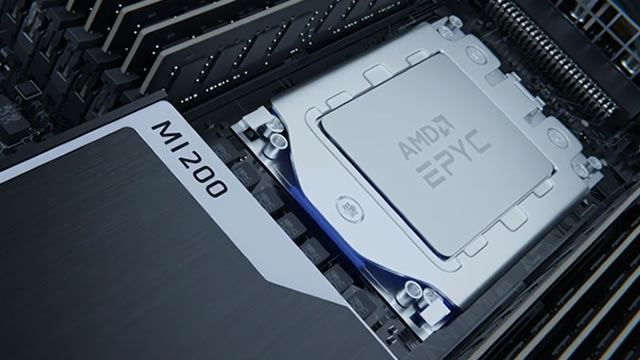
AMD Q1: You Still Have Time To Buy Before The Sentiment Shift
Buy Advanced Micro Devices, Inc. proactively. My $200 target anticipates AI-driven margin gains amid data-center strength and macro-induced 2026 upside. Macroeconomic tailwinds from U.S. deregulation and free-trade momentum should boost AMD's valuation multiples; position yourself now ahead of the sentiment shift. Keep a 15-20% cash buffer amid China risks; deploy this steadily as TSMC Arizona ramps up, mitigating Taiwan-related supply chain concerns.


