


The Coca-Cola Company (KO)




3 Dividend Stocks to Buy Before August Ends and Hold for Life
August is closing on a market that has rewarded speculation and punished patience, which is exactly when the boring compounders start looking interesting again.
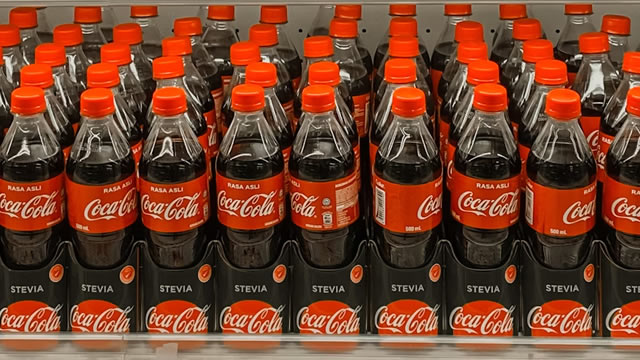
Inside Coca-Cola's secretive innovation labs: How the beverage giant wants to automate dirty soda and refreshers
Coca-Cola is working on equipment to automate dirty soda and refreshers as consumers increasingly want more drink options. From McDonald's to Wendy's, longtime Coke customers have been expanding their beverage offerings to boost their profit margins.
Brokers Suggest Investing in Coca-Cola (KO): Read This Before Placing a Bet
Investors often turn to recommendations made by Wall Street analysts before making a Buy, Sell, or Hold decision about a stock. While media reports about rating changes by these brokerage-firm employed (or sell-side) analysts often affect a stock's price, do they really matter?
Coca-Cola's Volume vs Price Mix: What's Driving Growth Now?
KO's growth is becoming more balanced as stronger volumes, brand activation and disciplined price/mix support healthy demand.
Coca-Cola Trades at a Valuation Premium: Justified or Overstretched?
KO's premium valuation draws attention as strong growth, margin expansion and raised outlook fuel its recent stock rally.
Coca-Cola's Revenue Growth: Organic Strength or Pricing-Led?
KO's second-quarter revenue growth leans on stronger volumes, as organic revenues rise 6% and unit case volume gains 5% versus just a 2% rally from price/mix.
3 Boring but Brilliant Stocks to Buy in August
Mid-year 2026 has been exhausting. Tech multiples have whipsawed on every AI CapEx headline, tariff chatter keeps macro desks on edge and the average investor is tired of getting head-faked.
Coca-Cola (KO) Just Pulled Back. Here's Why Retirees Are Buying the Dip in August
Here is the setup the headlines missed. Coca-Cola (NYSE:KO | KO Price Prediction) reported Q1 2026 numbers that triggered a fast bearish reaction on social platforms, followed by an equally fast reversal from a very specific group of buyers: income investors.
Here's How Many Shares of Coca-Cola You'd Need for $30,000 in Yearly Dividends. (Spoiler: It's a Lot.
Coca-Cola has been paying a dividend for decades and increased its payout for 64 consecutive years. It recently yielded 2.4%.
Will Coca-Cola's Emerging Market Expansion Offset U.S. Slowdown?
KO's emerging-market momentum and affordability strategy could cushion softer U.S. demand as global growth supports its raised 2026 outlook.
Can Coca-Cola's Raised 2026 Outlook Support More Earnings Growth?
Coca-Cola's raised 2026 outlook, stronger margins and broad volume growth support earnings momentum, though Africa sale timing and tougher comps add risk.
Is Coca-Cola Stock Worth Buying as Growth Meets a Premium Valuation?
KO's volume growth, margin gains and higher cash-flow outlook strengthen its case, but a premium valuation leaves little room for missteps.


