


Mondelez International, Inc. (MDLZ)




Mondelez: Trading At Attractive Levels For Long-Term Buyers
The market is pricing in a scenario where Mondelez business fundamentals remain at historical levels and margins stay flat. Recent developments, however, point out to a scenario of gradually improving margins over the coming years. The likelihood of MDLZ stock trading at higher multiples over the coming years has increased significantly.
Cadbury cut two months off its supply chain lead time for a key chocolate-bar ingredient in one move
Mondelez has opened a new $22 million chocolate ingredient facility in Malaysia. The investment brings a key part of the Cadbury maker's chocolate supply chain closer to its Southeast Asian operations.
Can Mondelez's Productivity Gains Offset Elevated Cocoa Cost Pressure?
Mondelez's productivity and pricing lift Q2 gross margin, but cocoa cost phasing keeps pressure on year-to-date profit and EPS.
Cramer Says the Snack Business Is Bad. Mondelez and Smucker Did Not Get the Message.
Jim Cramer called Campbell's snack quarter a nightmare and warned the whole category is broken, but two other packaged food giants reported something very different this week and raised their dividends to prove it.
Why Is Mondelez (MDLZ) Down 3.1% Since Last Earnings Report?
Mondelez (MDLZ) reported earnings 30 days ago. What's next for the stock?
Mondelez: Quality At A Reasonable Price, Regardless Of Cocoa Noise
Mondelez International remains a Buy, supported by resilient performance, global scale, and an attractive valuation with a solid margin of safety. MDLZ continues to outperform in core snacks, maintains strong emerging market momentum, and is on track to become the #1 global chocolate manufacturer. Guidance was raised to at least 2% organic net revenue growth, with long-term targets of 3–5% organic growth and high single-digit Adj. EPS growth.
Can Mondelez Build on 2.5% Growth in Biscuits and Baked Snacks?
Mondelez's biscuits and baked snacks grow 2.5% in Q2 as volume/mix, brand gains and share trends strengthen, with innovation offering more growth levers.
MDLZ Q2 Sales Beat and Higher 2026 Growth View Put Margins in Focus
Mondelez beat Q2 sales and earnings estimates and raised its 2026 organic growth outlook, but margin pressure keeps earnings conversion in focus.
Is MDLZ Worth Buying as Growth Improves but Valuation Stays Rich?
Mondelez's growth is broadening as North America rebounds and Emerging Markets stay firm, but Europe, chocolate weakness and rich valuation cloud the case.
Can Mondelez's Organic Growth Momentum Continue Through 2026?
Mondelez lifts its 2026 organic growth outlook as improving volume/mix, pricing and strength across key regions support its first-half momentum.
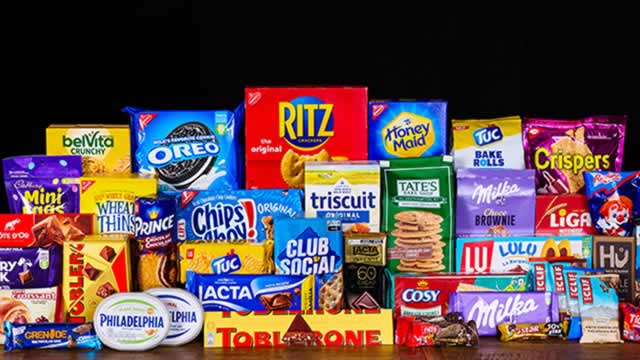
Mondelez: This Dividend Stock Still Has Room To Run
Mondelez remains a compelling core holding-type stock, combining strong brands, global scale, and robust emerging market momentum. MDLZ delivered net revenue growth and positive volume/mix, with emerging markets driving 8%+ organic growth. With a BBB credit rating, a 3.2% well-covered dividend yield, and 12 years of dividend growth, MDLZ offers defensive income.
Mondelez (MDLZ) Reliance on International Sales: What Investors Need to Know
Explore how Mondelez's (MDLZ) revenue from international markets is changing and the resulting impact on Wall Street's predictions and the stock's prospects.


