


Micron Technology, Inc. (MU)





Why I Wouldn't Own Micron Into Print - Earnings Preview
Micron Technology, Inc. is going to report its earnings results after the bell, marking the first out of the bunch to report for Q4. Non-HBM DRAM supply from China is rapidly increasing, threatening MU's pricing power and gross margins, but this is completely overlooked by the market. Recent data shows DRAM price acceleration is slowing, with spot and contract prices cooling and demand destruction outside AI markets.
Here's How Much Traders Expect Micron Stock to Move After Earnings
Micron Technology is set to report earnings after markets close Wednesday, with traders anticipating a sizable move in the memory chipmaker's stock.
Micron poised for upside as memory prices climb, according to Wedbush
Micron Technology Inc (NASDAQ:MU) could deliver fourth-fiscal-quarter earnings per share in the mid-$30s as rising DRAM and NAND prices lift sales and margins, Wedbush said ahead of the company's earnings call. The revised estimates sit around the upper end of prior company guidance, assuming mid-teens price increases for DRAM and NAND flash.
Micron has a chance to set the record straight with its earnings report
Micron is no longer the company it was before the AI boom, and one analyst says it's time that investors fully appreciate that.
Micron Q4: The Market Is Already Looking Beyond 2027
If you lean towards the view that markets tend to be forward-looking, how much growth do you think Micron Technology, Inc.'s 590% rally over the past year has priced in? That's the main question that I have heading into the fiscal Q4 FY26 print. Yeah, the 16 SCAs sound amazing, but I think the market wants more than that. Micron says 2027 could be even tighter than 2026, with some data center customers already receiving less than half the memory they want.
Micron's Earnings: Don't Be Misled By The Guidance, Don't Worry, Q4 Should Be Stellar
Micron (MU) is benefiting from a severe industry supply bottleneck in HBM4 and DRAM, driving exceptional pricing power and margin expansion. MU's gross margin surged to 84% and is guided to 86%, with revenue and EPS growth driven primarily by price, not volume. Fiscal Q4 2026 will be a 14-week quarter; headline growth may mislead, but underlying demand and pricing remain robust.
Micron: The Memory Cycle May Never Be The Same
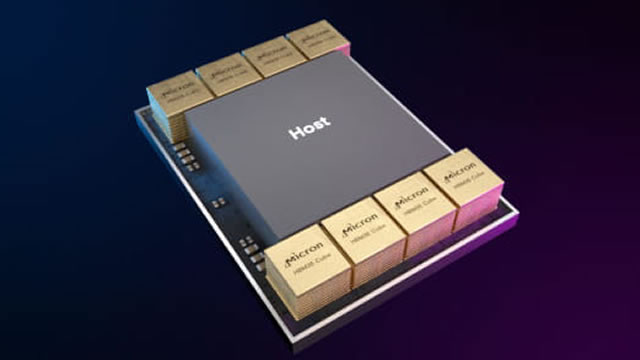
Micron Technology, Inc. remains a Buy as AI-driven memory demand outpaces supply, supporting a higher earnings floor and robust pricing. HBM's wafer intensity is tightening conventional DRAM supply, making the next downturn less severe and enhancing MU's margin durability. Strategic Customer Agreements now cover 20% of DRAM and one-third of NAND volume, with management targeting 50% coverage for future production.
Micron's Stock Faces Another Post-Earnings Plunge
Micron faces extreme bullish options positioning ahead of Q4 earnings. Despite strong analyst forecasts for revenue and EPS growth driven by AI demand, only a significant upside surprise may drive sustained share gains. Implied volatility is lower than last quarter, suggesting a post-earnings move of about 8.5%.
Micron: Remains A Strong Buy Ahead Of Q4 Earnings
Micron Technology remains a Strong Buy ahead of Q4 earnings, driven by constrained memory supply, robust AI demand, and sharply higher earnings estimates. Consensus expects MU to beat Q4 guidance, but investor focus is shifting to FY27 outlook, pricing power, and supply-demand dynamics across DRAM, NAND, and HBM4. EBITDA and free cash flow estimates for MU have surged, with a base case price target raised to $1,557, implying 46% upside and a potential path to $2,000 per share.
In 1980, Idaho's ‘French Fry King' Acquired 40% Of A Struggling Startup Called Micron, Operating Out Of A Boise Dentist's Office. His Stake Would Be Worth Well Over $400 Billion Today, If Any Of It Were Still In His Descendants' Hands.
A potato empire built on frozen fries and handshake deals sounds like an unlikely launching pad for one of the most lucrative bets in American business history, yet a single $1 million check written in 1980 set off a chain
Micron could dethrone Nvidia and become the biggest driver of S&P 500 profit growth
Micron is increasingly important to the S&P 500, and its earnings report has become “a market event in and of itself.”
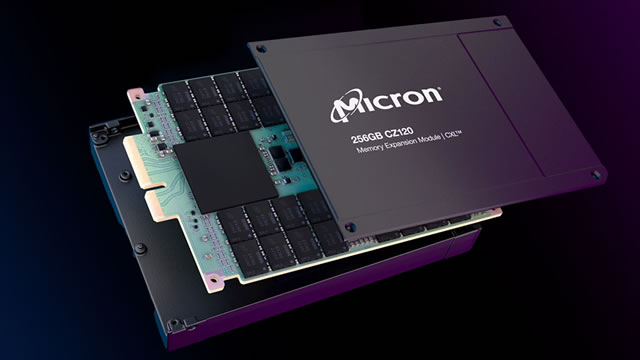
Micron investors should get ready for a seesaw ride, analyst says
The timing of an Nvidia product ramp may require a balancing act for Micron investors, as some estimated revenue shifts toward next year instead of this year.


