


Micron Technology, Inc. (MU)





Memory Stocks Were One of 2025's Hottest Trades. Now They've Cooled Off.
No one stays on top forever. That goes for the hottest stocks in the AI trade, too.
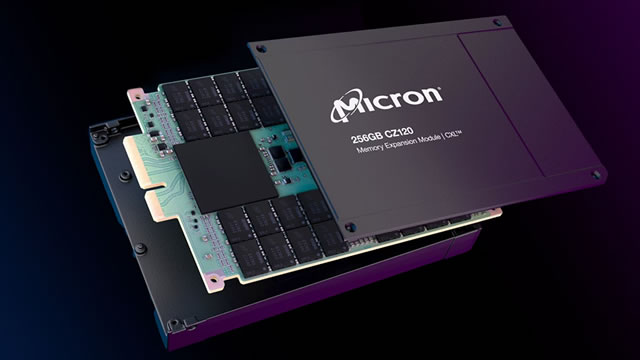
Wall Street Tells Investors Its Less Excited About Micron Stock
Citi trimmed its price target on Micron Technology (Nasdaq: MU | MU Price Prediction) to $425 from $510 but held firm on its Buy rating, pushing back against what it sees as an overblown narrative around TurboQuant's impact on memory demand.
Can Micron stock really jump 100%? Here's what analysts say after crash
Micron stock (NASDAQ: MU) is witnessing some sharp divergence in the current quarter. It posted record fiscal second-quarter results and leaned hard into the idea that memory has become a strategic part of the AI buildout.
Micron stock sinks 10%, further cratering in post-earnings sell-off
Micron shares fell 10% Monday, continuing a slide that began after the company reported earnings on March 18. The memory company's stock has cratered 30% since that blowout report.
Micron Slides 5% as Google's AI Memory Algorithm Sparks Fresh Fears Across the Semiconductor Sector
Micron Technology (NASDAQ:MU | MU Price Prediction) stock is falling 5% in early trading on Monday, trading around $339 after opening at $357.22.
Wall Street Sees Plenty of Upside in Micron Despite the Recent Dip
Micron Technology (NASDAQ: MU | MU Price Prediction) is trading at $357.22, while the Wall Street consensus price target sits at $527.60.
Micron's Selloff Is A Setup For The Next Surge
Micron reported $23.9B revenue and $12.20 EPS, yet fell ~20% as TurboQuant fears and capex concerns drove sentiment reversal. Forward EPS peaks near $98 by 2027, but current ~6x forward P/E implies aggressive earnings normalization assumptions by the market. AI-driven demand keeps DRAM and NAND supply constrained beyond 2026, with Micron still under-delivering to customers at record margins.
Micron: Buy This Selloff Driven By TurboQuant And Sora
Micron remains a 'Strong Buy' as structural shifts in memory reduce cyclicality and support long-term demand visibility. Recent stock pullback is attributed to increased CAPEX guidance, TurboQuant headlines, and Sora's shutdown, but these are viewed as short-term noise. MU's five-year SCA agreements and robust earnings beats reinforce confidence in sustained demand and business model stability.
Micron: AI Memory Paradox Could Send Demand Exploding Despite Margin Risks
Micron Technology (MU) demonstrates exceptional sales and margin growth, driven by robust AI-related demand and industry-wide supply constraints. Q2 revenues surged 196% year-over-year to $23.9B, with DRAM pricing up mid-60% and NAND up high-70%, fueling significant margin expansion. I raise my base case price target to $556.40 (56% upside) and bullish case to $871.56 (144% upside) on explosive EBITDA and free cash flow revisions.
Micron's stock bounces, as an analyst offers a reality check on the recent panic
Micron Technology shares were on pace to snap a six-session losing streak Friday, with an analyst likening the recent market freakout over memory stocks to last winter's DeepSeek saga that ultimately proved a blip.
Micron: Don't Be Fooled By The Beat, The Downturn Is Coming
Micron Technology (MU) has delivered explosive Q2 results, with revenue nearly tripling and margins approaching 75%, driven by AI-related demand and HBM memory. MU's growth is fueled more by price increases amid supply shortages than by volume expansion, signaling classic memory cycle dynamics rather than purely structural change. Despite strong AI tailwinds, weakening traditional memory markets and aggressive industry-wide CapEx raise risks of future oversupply and margin normalization.
Micron and SanDisk stocks are getting pummeled this week. Is the memory chip rally over?
Thanks for the memory?


