


Palantir Technologies Inc. (PLTR)



C3.ai and Palantir: Who Wins the Battle of Enterprise AI Stocks Now?
C3.ai and Palantir are taking very different paths as enterprise AI shifts from hype to execution, raising fresh questions for investors.
Palantir Technologies Inc. (PLTR) Is a Trending Stock: Facts to Know Before Betting on It
Zacks.com users have recently been watching Palantir Technologies (PLTR) quite a bit. Thus, it is worth knowing the facts that could determine the stock's prospects.
'PLTR positioned to be the nervous system' of Trump Trade in 2026
The the shift in U.S. foreign policy priorities provides different opportunities to invest in the defense sector, according to Matt Tuttle. Tuttle likes European defense stocks, as the U.K. and E.U.
Palantir Technologies (NASDAQ: PLTR) Price Prediction and Forecast 2025-2030 for December 23
Last week, shares of Palantir Technologies Inc. (NASDAQ:PLTR) gained 6.56% over past five trading sessions after gaining 0.72% the five prior.
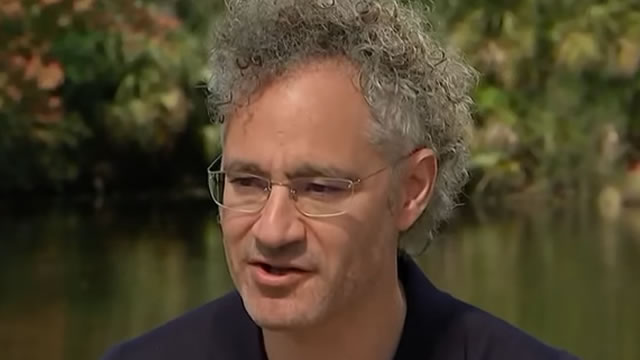
Palantir CEO Alex Karp buys 68-year-old Colorado monastery on 3,700 acres for whopping $120 million
The Colorado monastery has been carefully tended to by a group of Trappist monks for the last seven decades.
3 Reasons Palantir Is Unavoidable in AI Infrastructure by 2026
Palantir Technologies Inc. NASDAQ: PLTR continues to be a polarizing stock. Despite being up more than 155% in 2025, many investors remain concerned about the company's valuation.
This Michael Burry Warning Could Be Bigger Than His Short Call on Palantir
Most investors are well aware I'm not necessarily bullish on Palantir (NASDAQ:PLTR) and a few other high-flying growth stocks which have valuations that just appear to be untenable right now.
How Low Could Palantir (PLTR) Stock Go In 2026?
We're nearing the end of 2025, so it's now time for pundits and market commentators to make their predictions for what 2026 will bring.
Palantir Stock's Valuation: Overstretched or Rightfully Earned?
PLTR's valuation towers over peers with sky-high multiples, testing whether Palantir's AI growth and execution can justify what investors are paying.
The Palantir Bear Case for 2026
Palantir (NASDAQ:PLTR) is among the most notable growth stocks that's absolutely ripped higher thus far this year.
Should You Buy Or Sell Palantir Stock Today?
Palantir Technologies (PLTR) stock has decreased by 5.6% in Wednesday's trading and is currently valued at $177.29. While the company has seen expanding partnerships and contracts, fueling growth of its commercial segment, investors have been skeptical about the broader AI trade.
Palantir: Yes, This AI Play Is Still Undervalued
Palantir Technologies is experiencing explosive revenue and earnings growth, driven by surging demand for its AIP platform in both government and commercial markets. PLTR's commercial segment outpaced government growth, with Q3 commercial revenue up 73% year-over-year and US commercial revenue growing 121%, signaling a major revenue mix shift by 2026. Despite a lofty 2026 P/E of 189.4, PLTR's 231% earnings growth and expanding business intelligence market exposure may justify its premium valuation for bullish investors.


