


Philip Morris International Inc. (PM)




Coca-Cola or Philip Morris: Which Is the Better Short Bet Right Now?
Coca-Cola (NYSE: KO | KO Price Prediction) and Philip Morris International (NYSE: PM) both posted Q1 2026 beats within a week of each other.
Philip Morris: Room To Run Toward Fair Value
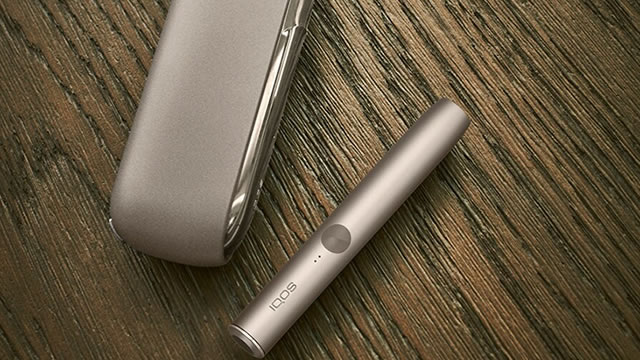
Philip Morris International is reiterated as a 'Buy,' offering high income, robust dividend growth, and capital appreciation at a modest discount to fair value. PM's smoke-free segment now comprises 43% of revenue, with IQOS surpassing Marlboro as the leading nicotine brand in key markets. PM targets a 2x net debt/EBITDA by end-2026, likely prompting a credit upgrade and enabling share buybacks to further boost EPS.
Philip Morris: No Reason To Get Involved Today
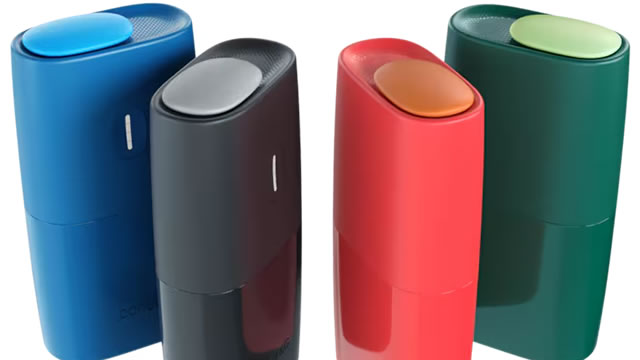
Philip Morris (PM) exhibits strong growth in smokeless tobacco but trades near fair value after a 6% post-earnings rally. SFPs now comprise 41.4% of PM's product mix, driving high-single-digit shipment growth and international momentum. Despite a solid 3.5% yield and robust SFP performance, the risk/reward is balanced with limited upside at current valuation.
Philip Morris International Inc (PM) Q1 2026 Earnings Call Highlights: Strong Smoke-Free Growth and EPS Surge
Net Revenues: Over $10 billion, a 9% increase in reported terms and 2.7% organically.Adjusted Operating Income: Grew by 10% to $4.2 billion with close to 1% or
Philip Morris: Growth At An Expensive Price (Rating Upgrade)
Philip Morris International delivered strong Q1'26 results on Wednesday, with alternative products now comprising 43% of total revenues. I see PM as a reliable income vehicle, with the tobacco and alternative products company on track to pay out ~73% of adjusted EPS this year. PM confirmed its adjusted EPS guidance (excluding currency impact) for FY 2026, reflecting momentum in non-traditional tobacco products and robust emerging markets exposure.
Philip Morris stock jumps 7% as smoke-free growth drives beat
Shares of Philip Morris International rose about 7% on Wednesday after the tobacco giant reported stronger-than-expected first-quarter results, driven by robust growth in its smoke-free business and solid international performance. The company's earnings and revenue both exceeded analyst expectations, with adjusted earnings per share of $1.96 topping consensus estimates of around $1.83.
Philip Morris Sales Rise on Smoke-Free Business Growth
Philip Morris International logged higher revenue in the first quarter, with particularly strong growth in its smoke-free business.
Philip Morris cuts annual profit forecast
Philip Morris International cut its annual profit forecast on Wednesday, signaling pressure from heightened competition in tobacco products and regulatory uncertainty over its Zyn nicotine pouches.
Philip Morris' IQOS Retains FDA Modified-Risk Authorization
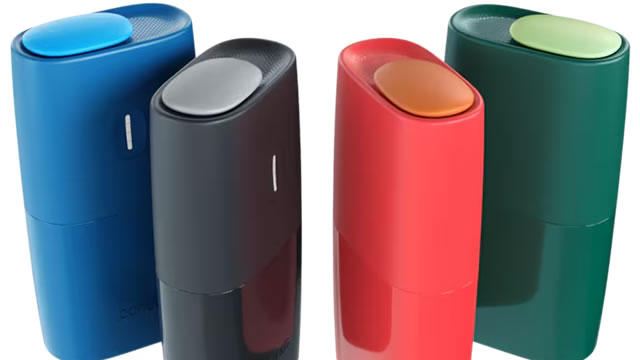
Philip Morris wins renewed FDA backing for IQOS, keeping its modified-risk claims alive as the company accelerates its shift beyond cigarettes.
Insights Into Philip Morris (PM) Q1: Wall Street Projections for Key Metrics
Get a deeper insight into the potential performance of Philip Morris (PM) for the quarter ended March 2026 by going beyond Wall Street's top-and-bottom-line estimates and examining the estimates for some of its key metrics.
Philip Morris: Expect Upside Surprise From Q1 2026 Results
Philip Morris International might have had a lacklustre 2026 so far, but it could well see a price uptick following its Q1 2026 results, providing a trading opportunity. Typically, the stock tends to react sharply on earnings releases, and my estimates indicate that the adjusted EPS could surprise upwards, which can be positive for price. Over the remainder of the year, though, PM's price prospects are limited, with fair valuations, but over the medium and long term, it's firmly supported by stock metrics.
Philip Morris Q1 Earnings on Deck: Key Factors You Should Understand
PM's first-quarter results are likely to show revenue and earnings growth, supported by pricing discipline and strength in smoke-free products.


