


Waste Connections Inc. (WCN)



Waste Connections (WCN) Moves 5.5% Higher: Will This Strength Last?
Waste Connections (WCN) saw its shares surge in the last session with trading volume being higher than average. The latest trend in earnings estimate revisions could translate into further price increase in the near term.
Waste Connections (WCN) is a Top-Ranked Momentum Stock: Should You Buy?
Whether you're a value, growth, or momentum investor, finding strong stocks becomes easier with the Zacks Style Scores, a top feature of the Zacks Premium research service.
Waste Connections (WCN) Earnings Expected to Grow: What to Know Ahead of Next Week's Release
Waste Connections (WCN) doesn't possess the right combination of the two key ingredients for a likely earnings beat in its upcoming report. Get prepared with the key expectations.
WCN Benefits From Buyouts & Global Waste-Management Market Expansion
Waste Connections gains from buyouts, strong pricing and AI-driven efficiencies as the global waste-management market expands, supporting revenue growth.
Here's Why Waste Connections (WCN) is Poised for a Turnaround After Losing 6.2% in 4 Weeks
Waste Connections (WCN) has become technically an oversold stock now, which implies exhaustion of the heavy selling pressure on it. This, combined with strong agreement among Wall Street analysts in revising earnings estimates higher, indicates a potential trend reversal for the stock in the near term.
Here's Why Investors Must Hold WCN Stock in Their Portfolios Now
Waste Connections' shares fall 10.7% over the past year, but solid Q2 growth, a raised 2026 outlook and acquisitions support prospects amid cost and volume pressures.
WCN Shares Rise 8.6% in 3 Months: Here's What You Should Know
Waste Connections gains 8.6% in three months as market tailwinds, acquisitions and strong cash generation support its growth momentum.
Why Is Waste Connections (WCN) Up 0.2% Since Last Earnings Report?
Waste Connections (WCN) reported earnings 30 days ago. What's next for the stock?
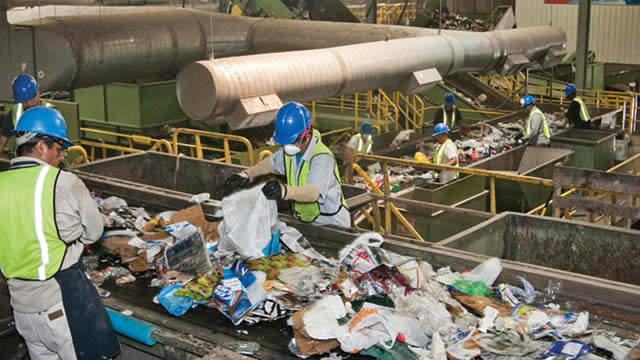
Here's Why Investors Must Hold WCN Stock in Their Portfolios Now
Waste Connections gains as market expansion, acquisitions and steady dividends support growth despite rising liquidity and regulatory pressures.
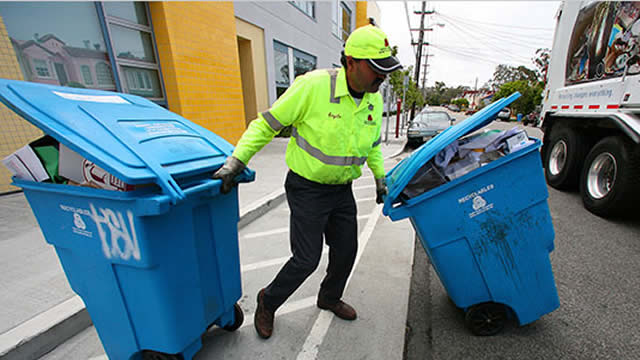
Waste Connections: Turning Moderate Growth Into Exceptional Shareholder Returns
Waste Connections, Inc. earns a Buy rating for its proven ability to compound shareholder value through disciplined capital allocation and operational excellence. WCN's differentiated operating model focuses on secondary and exclusive markets, driving superior margins, customer retention, and consistent free cash flow growth. Adjusted EBITDA margins have steadily improved from 31.5% to 33.0% (2023–2025), with free cash flow outpacing moderate revenue growth, underpinning long-term returns.

How Waste Connections Is Using AI to Expand Margins and Future Growth
WCN is turning AI pricing into $20 million in annualized EBITDA gains while testing routing tools and targeting broader margin growth.

Is WCN Stock Worth Its Premium Valuation After Strong Q2 Results?
Waste Connections beat Q2 estimates, raised its 2026 outlook and delivered strong cash flow, but debt and a premium valuation leave limited upside.


