


Micron Technology, Inc. (MU)





Micron Q4 Earnings Beat Estimates on Strong Pricing and AI Demand
MU's Q4 earnings surge as stronger DRAM and NAND pricing, AI demand and data center growth drive record revenues and margins.
Micron Q4: Favorable Outlook As Memory Shortage Persists
I believe the forward outlook for Micron remains favorable, as the memory shortage is set to continue well past 2027. The company reported quarterly results that topped expectations. Looking ahead, the company plans to spend about +$25B in CAPEX, with just under +$12B expected in Q1.
Why Micron's big earnings report isn't lifting the stock
Expectations are high, and Micron isn't topping estimates to the degree that it used to.
Micron Technology Stock Slides Despite Blowout Q4 Report
Shares of Micron Technology Inc (NASDAQ:MU) are modestly lower before the open, down 0.9% despite the semiconductor giant's blowout fiscal fourth-quarter earnings and revenue beat.
Micron Blew Past Estimates and Says It Can't See When the Memory Shortage Ends
Micron just posted its eighth straight earnings beat and a stock gain that tops 270% for the year, yet the CEO openly admits he cannot see when the memory shortage ends.
Analysts Are Bullish on Micron. The Numbers Argue for Patience
Wall Street consensus puts Micron near the top of every buy list, but one model sees something the bulls are missing.
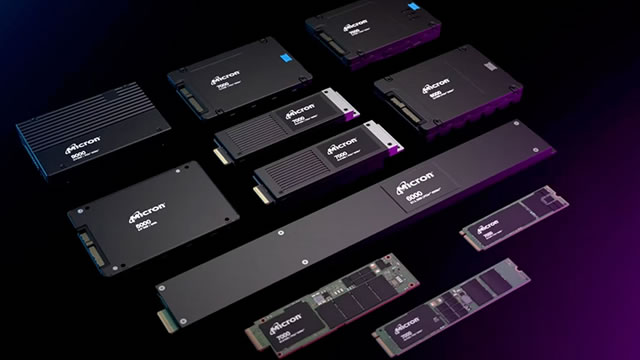
Wall Street analysts update Micron (MU) stock price target
Multiple prominent Wall Street analysts took Micron's (NASDAQ: MU) latest earnings report – published on September 30 – to provide their revised 12-month stock ratings and price targets.
Tech Stocks Rise as Micron's Bullish AI Forecast Fuels Rally
Bloomberg Daybreak Europe is your essential morning viewing to stay ahead. Live from Brussels, we set the agenda for your day, catching you up with overnight markets news from the US and Asia.
Samsung, SK Hynix rise after Micron earnings but investors ignore the 24-year warning
Samsung Electronics and SK Hynix recovered intraday on Thursday after opening lower, as Micron Technology's record results reinforced the view that the global memory shortage is becoming more severe rather than easing. Micron reported fiscal fourth-quarter revenue of $54.23 billion and guided for $61.5 billion next quarter, both ahead of expectations.
Micron revenue quadrupled to $54 billion but the stock fell: here's why
Micron (MU) delivered a blockbuster Q4 earnings report on September 30, crushing Wall Street estimates and proving the artificial intelligence infrastructure (AI) boom remains in hyperdrive. Driven by surging global demand for High-Bandwidth Memory (HBM), the semiconductor giant posted unprecedented top- and bottom-line performance, with data center sales up 11x.
Micron Technology, Inc. (MU) Q4 2026 Earnings Call Transcript
Micron Technology, Inc. (MU) Q4 2026 Earnings Call Transcript
Wall Street Lunch: Micron On Top
Micron (MU) remains a strong buy, supported by robust quant ratings and consistent earnings beats. MU has demonstrated accelerating EPS growth, with recent quarters showing dramatic improvements and record results.


