


Philip Morris International Inc. (PM)




Philip Morris: The First $11 Billion Quarter Won't Be The Last
Philip Morris International delivered record Q2 2026 net revenues of $11.19 billion, with 15.2% adjusted EPS growth and expanding margins. Smoke-free products now comprise 42% of PM's revenues, with IQOS and ZYN driving global share gains and margin expansion. I remain bullish on PM, citing robust earnings growth, a 3% dividend yield, and clear capital allocation optionality post-deleveraging.
Philip Morris International Q2 Earnings Call Highlights
Philip Morris International NYSE: PM reported what management described as a “very strong” second quarter, with growth led by its international smoke-free products business and a better-than-expected performance in combustibles.
Philip Morris (PM) Tops Q2 Earnings and Revenue Estimates
Philip Morris (PM) came out with quarterly earnings of $2.2 per share, beating the Zacks Consensus Estimate of $2.04 per share. This compares to earnings of $1.91 per share a year ago.
Philip Morris Sales Boosted by Growth in International Business
Philip Morris International recorded higher revenue in the second quarter, boosted by growth in its international business and its Zyn portfolio in the U.S.
Philip Morris (PM) Earnings Expected to Grow: Should You Buy?
Philip Morris (PM) doesn't possess the right combination of the two key ingredients for a likely earnings beat in its upcoming report. Get prepared with the key expectations.
Philip Morris International's Earnings Preview: I'm Not Buying
Philip Morris International's Earnings Preview: I'm Not Buying
FDA lets Philip Morris market Zyn nicotine pouches as less harmful than cigarettes
The FDA will allow 20 Philip Morris-owned Zyn nicotine pouch products to carry a modified-risk claim saying switching from cigarettes lowers the risk of several smoking-related diseases. The decision gives Philip Morris a major marketing win for one of the fastest-growing nicotine products as cigarette sales decline in the U.S.
1 Dividend Powerhouse Retirees Can Lean On Even If Rates Hike
Philip Morris International (NYSE:PM | PM Price Prediction) is a tobacco giant in the middle of a profitable pivot, with smoke-free products now accounting for over 43% of net revenues through IQOS heat-not-burn devices and ZYN nicotine pouches.
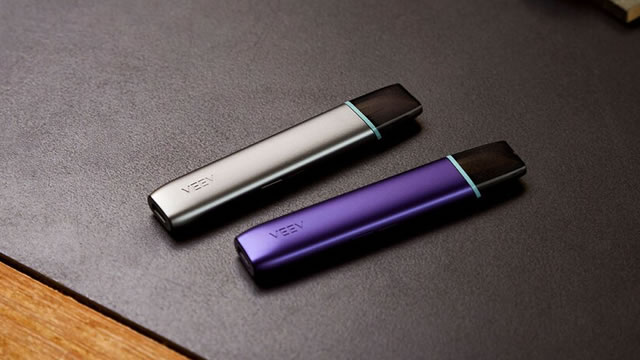
Philip Morris: King Of Tobacco In Consolidation Stage - Wait For A Dip
PM's leadership in smoke-free products, profitable growth trends, and secure dividend prospects justify a Buy on pullbacks, especially for swing traders within the $150s–$180s range. Smoke-free revenues now comprise 43% of sales, with IQOS/ZYN/VEEV delivering double-digit volume growth in select regions, supporting the management's adj EPS growth target at 3Y CAGR of +10%. These may very well temper the risks from the declining cigarette volumes amid price sensitivity, attributed to the likely to remain higher inflationary pressure in the intermediate term.
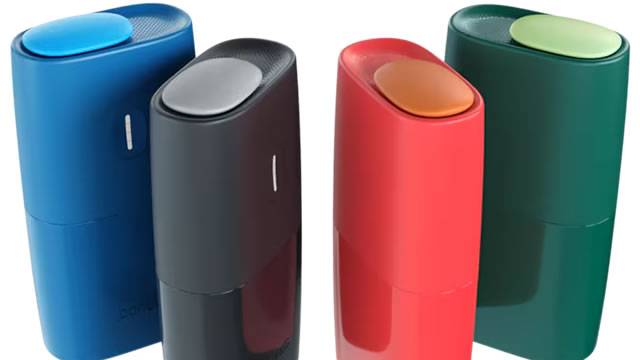
Philip Morris: IQOS And ZYN Offset Combustibles Volume Decline
Philip Morris International delivered strong FQ1 2026 results, with EPS of $1.96 and 9% YoY revenue growth, mostly driven by smoke-free products. But growth potential from smoke-free offerings, notably IQOS and ZYN, is tempered by declining combustible product sales. Despite the mixed dynamics, PM trades at a significant P/E premium to the sector and historical averages.
Philip Morris to Post $500 Million Impairment on Canada Affiliate
Philip Morris International said it is booking a roughly $500 million impairment charge in the second quarter to reduce the carrying value of its investment in Canadian affiliate Rothmans Benson & Hedges, or RBH.
Philip Morris: The Pullback Is A Gift For Long-Term Investors
Philip Morris: The Pullback Is A Gift For Long-Term Investors


