


Vici Properties Inc. (VICI)



VICI Properties: Why I'm Buying The Tumble
VICI has crashed despite higher cash flows and a new dividend hike. The market is pricing in the Caesars risk and higher rates. A recovery to $40 by 2030 may not be that far fetched.
VICI Properties Inc. (VICI) Surpasses Market Returns: Some Facts Worth Knowing
In the closing of the recent trading day, VICI Properties Inc. (VICI) stood at $23.46, denoting a +2.27% move from the preceding trading day.
VICI Properties Manages Debt: Is Its Balance Sheet Ready to Grow?
VICI expands its portfolio while maintaining $2.5 billion in liquidity, manageable leverage and no remaining 2026 debt maturities.
Cheaper Than March 2020: Why We're Buying VICI Properties At An 8% Yield
In 2025, negative sentiment created a massive buying window in energy; in 2026, the exact same dynamic has played out across real estate, opening up historic entry multiples. VICI trades at just 8.24x FFO (Avg of 15x–16x and peak of 21.4x) – valued cheaper than during March 2020 (~9x FFO), when its tenants were literally prohibited from operating. Management's recent 2.2% dividend increase matches organic CPI-linked contractual rent escalators, conserving valuable liquidity rather than straining the balance sheet to appease short-term sentiment.
Should Realty Income Buy VICI?
Realty Income could unlock significant value by acquiring VICI Properties at a premium, leveraging cost-of-capital arbitrage. An O + VICI merger would substantially reduce tenant concentration risk and diversify rental income while maintaining O's A-rated balance sheet. At a $27.50 per share offer for VICI, the deal models to 5.3% AFFO-per-share accretion for O, balancing premium and accretion.
VICI Properties Trading at a Discount: Should You Buy the Stock Now?
VICI's long-term leases and portfolio expansion offer growth potential, but heavy tenant concentration remains a key risk.
VICI Properties: I've Seen This Story Before, Why I'm Buying The 8% Yield
VICI Properties is upgraded to a buy, trading at an 8% dividend yield—its highest since IPO—amid broad sector underperformance. VICI's trophy casino assets, robust net lease structure, and conservative 4.9x leverage support resilient cash flows despite tenant concentration and rising rates. Annual lease escalators above 2%, ultra-long lease terms, and manageable debt maturities underpin double-digit total return potential even without multiple expansion.
VICI Properties: Strong Buy Amid Overstated Risks - Rich Capital Appreciation And Dividends
Despite macro headwinds, major tenants' take-private noise, and Las Vegas softness, VICI maintains robust fundamentals: 100% occupancy, CPI-linked escalators, and secure dividends. Ongoing diversification into experiential assets and (speculatively) regional gaming may reduce Las Vegas concentration and mitigate iGaming competition risks. The meltdown has triggered VICI's extremely discounted Price/AFFO of 9.2x (8Y mean at 13.92x and COVID lows at 6.58x), with it triggering >70% upside to my bull-case LTPT of $38.90.
VICI Properties Expands Experiences: Can Non-Gaming Growth Scale?
VICI expands beyond casinos with Club Med St. Croix and other experiential assets, using partnerships and financing to grow its experiential real estate platform.
VICI Properties Inc. (VICI) Stock Declines While Market Improves: Some Information for Investors
The latest trading day saw VICI Properties Inc. (VICI) settling at $22.73, representing a -1.04% change from its previous close.
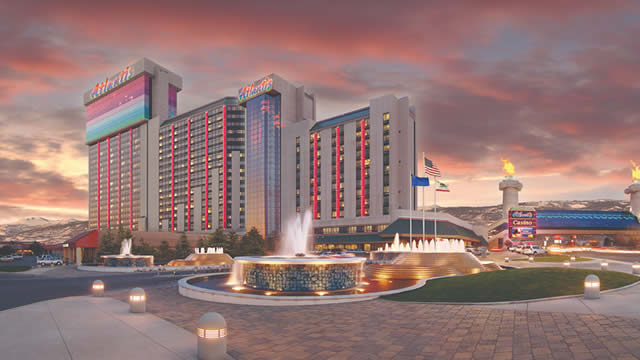
Why VICI's 1.3x Dividend Coverage Ratio Looks Safer Than Its Falling Stock Price Suggests
VICI Properties stock has shed nearly a quarter of its value in a year, yet the company just raised its dividend again.
VICI Properties: Priced For A Caesars Rent Cut The Math Doesn't Support
VICI Properties trades at 9.6x AFFO with a 7.8% yield, despite raised guidance and dividend, reflecting market overreaction to regional lease concerns. Even a 30% rent cut on the Caesars regional lease would reduce AFFO by only 8%, leaving the dividend well covered and the valuation discount excessive. VICI's intrinsic value is estimated at $31–$36 per share, implying a 25%–34% discount at current prices, with upside if multiples normalize or lease outcomes are better than feared.


