


First Majestic Silver Corp (AG)


First Majestic's Silver Production Decreases 11% Y/Y in Q3
AG's Q3 silver production falls 11% y/y amid a labor dispute at San Dimas, while La Encantada delivers a 68% surge.
Fortuna Mining's Q3 Gold-Equivalent Production Dips Sequentially
FSM's Q3 gold-equivalent production falls 3.9% sequentially, but the company remains on track to meet its 2026 target as mine performances diverge.
Can First Majestic Meet Its Upbeat 2026 Production Guidance?
AG lifts its 2026 production outlook after a strong H1, with higher silver and gold guidance driven by mine performance and throughput gains.
First Majestic Silver Eyes Growth, Jerritt Canyon Restart as Silver Deficit Deepens
First Majestic Silver NYSE: AG outlined plans to expand production, advance exploration and restart its Jerritt Canyon gold operation as the company seeks to capitalize on higher precious-metals prices and strengthen its position as a major silver producer.
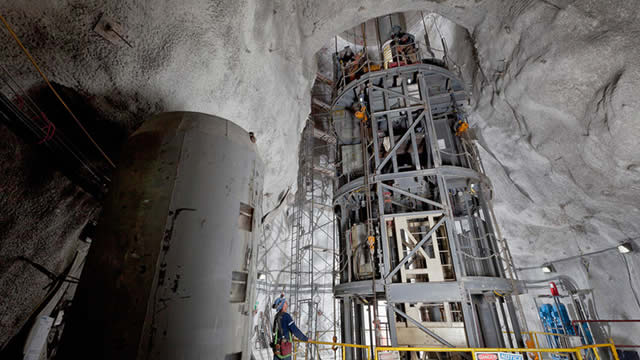
Gold, Silver Gain as Oil Prices Ease & Dollar Weakens: 4 Stocks to Watch
Gold and silver rebound as lower Treasury yields, a weaker dollar and falling oil prices support metals, putting four mining stocks in focus.
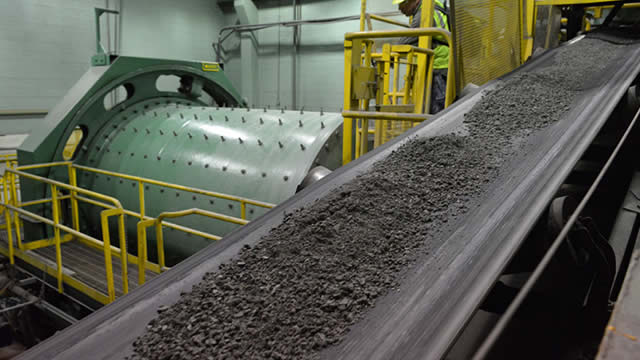
First Majestic: Closer To Fair Value (Upgrade To Hold)
First Majestic Silver Corp. is upgraded to Hold, reflecting a now fair valuation and improved operational outlook amid continued gold and silver demand. AG's production guidance has increased, with gold output expected up 30% through 2028 and Jerritt Canyon's restart accelerating gold growth potential. The valuation premium has deflated; at 8x EV/EBITDA, AG's YE27 price target is $21, offering little near-term upside versus consensus.
Is the Options Market Predicting a Spike in First Majestic Silver Stock?
Investors need to pay close attention to AG stock based on the movements in the options market lately.
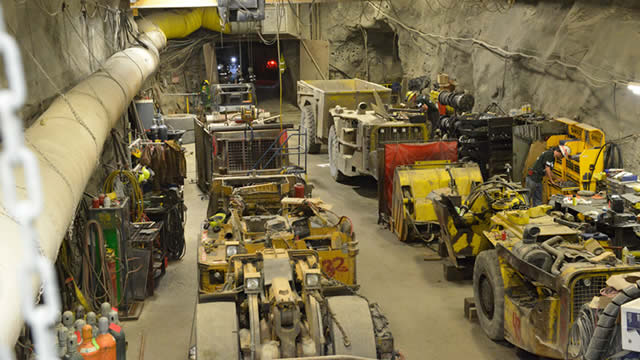
First Majestic Silver: The Silver Re-Rating Opportunity Returns (Rating Upgrade)
First Majestic Silver is upgraded to Buy as the valuation now offers a discount to intrinsic value assuming silver's re-rating potential. Q2 performance was robust with EBITDA up 110% and $194.6M FCF, supported by higher realized silver and gold prices despite increased costs. AG's improved 2026 guidance, major cash position ($1.09B), and asset sales position it for reinvestment and potential M&A activity.
First Majestic (AG) Could Find a Support Soon, Here's Why You Should Buy the Stock Now
First Majestic (AG) appears to have found support after losing some value lately, as indicated by the formation of a hammer chart. In addition to this technical chart pattern, strong agreement among Wall Street analysts in revising earnings estimates higher enhances the stock's potential for a turnaround in the near term.

2 Silver Mining Stocks to Buy in a Challenged Industry
With the recent volatility in silver prices weighing on the near-term prospects of the Zacks Mining - Silver industry, stocks like AG and VZLA will likely gain from solid growth projects.

Wall Street Analysts Think First Majestic (AG) Could Surge 54.3%: Read This Before Placing a Bet
The mean of analysts' price targets for First Majestic (AG) points to a 54.3% upside in the stock. While this highly sought-after metric has not proven reasonably effective, strong agreement among analysts in raising earnings estimates does indicate an upside in the stock.
First Majestic Silver: Monster Q1 And Two Smart Asset Sales
First Majestic Silver remains a buy, offering high leverage to silver with improved fundamentals and a cleaner portfolio after two non-core asset sales. Recent sales of San Martin ($90M, NPV ~$77M) and Del Toro (up to $60M) convert idle assets into liquidity, supporting capex for growth projects like Santo Niño. Q1 delivered strong results: revenue up 95% YoY to $476.7M, free cash flow $224M, and record $1.13B treasury, reflecting operational leverage to silver prices.


