


BYD Company Limited (BYDDY)



BYD Company: Strong Export Growth Underpins Value
BYD Company Limited maintains strong export momentum and rising EV sales, signaling a robust upcoming Q2 earnings report. BYDDF leads Tesla in terms of gross profit margins, and BYD has a much larger delivery volume. The stock trades at a depressed valuation—13.9x FY 2027 P/E—despite profitability and industry leadership.
BYD Company: Overseas Boom Changes The Entire Thesis
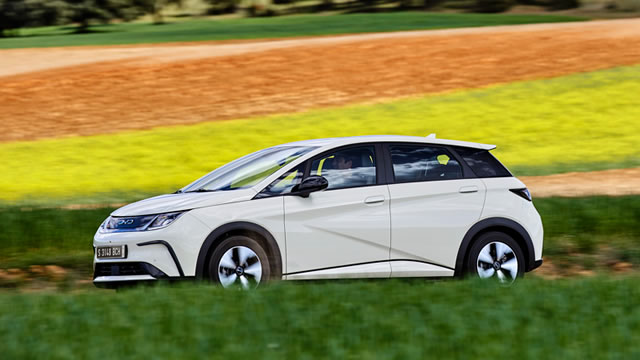
China is still BYD's biggest problem, but the picture is starting to stabilize, with domestic sales declines narrowing while total vehicle sales returned to growth in June and July. Overseas sales are now large enough to materially change BYD's growth mix and offset weakness at home. Europe and Brazil show that BYD can take share outside China, while local production should make that expansion more durable.
Record Exports Boost BYD Sales as Chinese EV Stocks Suffer
BYD exported over 180,000 vehicles in July, more than 40% of its total sales volume.
Buoyant BYD has Tesla in it's rear view mirror. Musk needs to put his foot down
The headline number in BYD's July sales, announced over the weekend, is not the one that should worry Tesla. BYD, the Chinese carmaker that overtook Tesla Inc (NASDAQ:TSLA) as the world's largest seller of battery-electric vehicles last year, lifted global sales 21.8% to 419,211 vehicles, a third straight month of growth.
BYD's sales rise for third month, buoyed by exports
Chinese electric vehicle maker BYD's , global sales rose for a third straight month in July, with robust overseas demand continuing to help offset softer conditions in its home market.
BYD Shares Rally 22% As Tesla Dives 23%
The EV business is supposed to be in trouble. U.S. sales have dropped as much as 20% in the first half of the year.
Zacks Industry Outlook BYD, NIO and Yamaha
BYD, NIO and Yamaha have been highlighted in this Industry Outlook article.
BYD's Growing Exports Meet Cash Flow/Balance Sheet Risks - Growth Pains Persist
BYD Company Limited's aggressive international investments drive robust export volumes at potentially higher ASPs in Q2'26, with it supporting the sequential top/bottom-line improvement prospects from FQ2'26. Despite the intensifying competition in China, BYDDF remains the market leader with leading shares, with further sales opportunities in H2'26 given the potentially higher for longer oil prices. The meltdown has triggered BYDDF's discounted valuations at EV/Sales of 0.81x and P/E of 16.48x, with the oversold technicals and bottoming at $9.20s triggering a compelling risk/reward for contrarian investors.
Shares of BYD and Xiaomi surge as June delivery figures fuel optimism
Xiaomi maintained deliveries above 30,000 units for a third straight month. BYD's June sales volume rose 5.46% from a year earlier.
BYD: Export Cheer, Domestic Despair
BYD is rated 'hold' as surging high-margin exports offset severe domestic sales and margin pressures. Despite valuation models indicating BYDDY is undervalued, extremely bearish technicals and a persistent downtrend preclude a buy recommendation. Export sales, especially in Europe, deliver premium margins—up to €10,000 per vehicle—while domestic net profit margin fell to 4.09% in 2025.
Humanoid Livestream: Robot Makers Rushing To Show Machines On Real Production Lines
The new flex in humanoid robotics isn't a backflip or a dance routine. It's a webcam pointed at a factory floor, running for days, watching robots do actual work on actual production lines in actual factories.
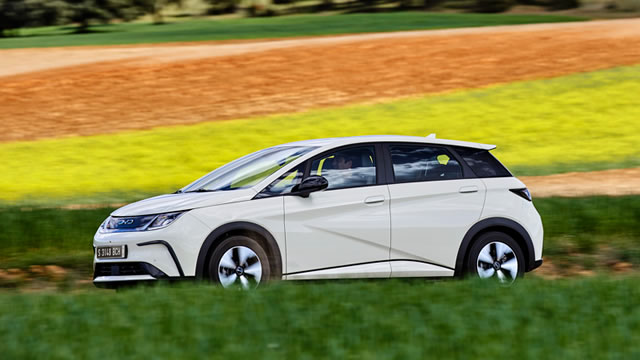
F1 sponsorship could give BYD lower-risk route to global recognition
Electric vehicle giant BYD is interested in getting involved with the Formula One motor racing circuit as it aims to boost its brand outside its home market of China, where it already has a strong foothold.


