


Cerebras Systems Inc. (CBRS)
 NASDAQ (NGS) NASDAQ (NGS) Primary
Cerebras (CBRS) Down 17.2% Since Last Earnings Report: Can It Rebound?
Cerebras (CBRS) reported earnings 30 days ago. What's next for the stock?
Cerebras: The Inference Bottleneck Winner
Cerebras holds $25.4 billion of RPO, but only 22% should convert into revenue through June 2028. Cloud and services revenue surged 287% YoY to $127.7 million as Cerebras increasingly monetizes inference rather than hardware. More than 600MW of secured capacity shifts Cerebras' primary growth constraint from semiconductor availability toward data center deployment.
Cerebras Has a $25.4 Billion Backlog, and One OpenAI Agreement Is Behind Much of It
Cerebras grew its second-quarter adjusted revenue 103% year over year to $209.9 million. Remaining performance obligations reached $25.4 billion as of June 30, and a significant amount of that balance traces to a December agreement with OpenAI.
Sizing Up Cerebras Systems: Why Its Latency Moat Makes It A Buy For Aggressive Growth Investors
Cerebras targets dominance in AI inference with its CS-4 chip and unique wafer-scale architecture, aiming to capture latency-sensitive workloads. Gross margin expansion, data center buildout, and core operating margin improvement are essential for CBRS to achieve GAAP profitability and justify its premium valuation. Major risks include Nvidia's entrenched ecosystem, manufacturing yield challenges, and limited competitiveness in applications requiring large KV caches.
Cerebras System's Choppy Year Continues But a Wall Street Pro Forecasts 80% Returns Moving Forward
Cerebras Systems (NASDAQ:CBRS) currently trades near $185.43, while the average Wall Street price target sits at $291.64.

This Brilliant Tech Investor Just Bought SpaceX, Micron, Cerebras and Some Other Semiconductor Names
The latest 13F filing season just came by, and as we gain a glimpse of what some of our favorite hedge funds have been up to in the second quarter, investors might have a breadcrumb trail to follow as the bull market takes its next turn and the most volatile time of the year comes rolling along.
Speed Sells: Cerebras Cracks the Silicon Ceiling
The semiconductor sector is undergoing a fundamental shift. While the opening chapters of the artificial intelligence boom centered on heavy training clusters, enterprise spending is pivoting toward real-time inference.

Cerebras launches new server chip and system designed to speed AI chatbots
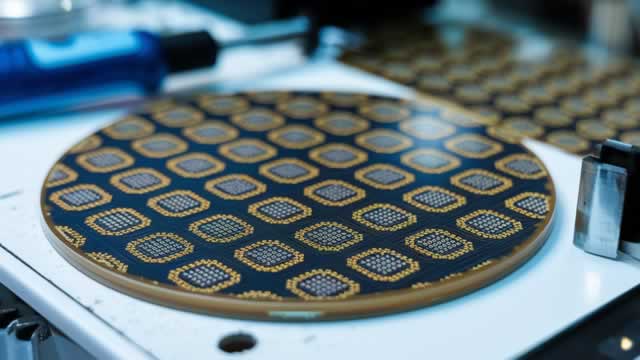
Cerebras Systems announced on Tuesday a new version of its server hardware that includes its dinner-plate-sized chips that it says will speed AI chatbot queries.
Cerebras: AI Growth Is Just Kicking Off
Cerebras Systems delivered 74% Y/Y GAAP revenue growth and 281% Y/Y AI cloud services growth in the second-quarter. CBRS benefits from secular AI CapEx trends, with robust demand for its wafer technology and gross margin gains indicating pricing power. Analyst projections highlight that the company is expected to deliver significantly faster top line growth next year, in large part due to surging AI cloud services business.
Does Cerebras (CBRS) Have the Potential to Rally 29.44% as Wall Street Analysts Expect?
The mean of analysts' price targets for Cerebras (CBRS) points to a 29.4% upside in the stock. While this highly sought-after metric has not proven reasonably effective, strong agreement among analysts in raising earnings estimates does indicate an upside in the stock.
Digi Power X: Power Scarcity Makes Cerebras Contract More Valuable Than Market Thinks
Digi Power X (DGXX) transitions from crypto mining to AI infrastructure, anchored by a $1.1B take-or-pay contract with Cerebras for 40 MW in Alabama. DGXX's dual revenue model—colocation and GPU rentals—offers both predictable income and upside from compute scarcity, with management targeting $140M+ annualized contracted run rate in 2027. The current $150M cash balance and no debt support project execution, but ongoing equity raises dilute shareholders; prudent debt financing is preferred for future growth.

Cerebras: 3x 2027 Revenue Guidance Changes The Valuation Debate
I'm reiterating Cerebras Systems (CBRS) as a Buy with an updated price target of $284. CBRS raised 2026 core revenue guidance to $880–$890 million and expects at least 3x core revenue growth in 2027, improving revenue visibility. Core cloud and services revenue surged 287% y/y, supporting the thesis of CBRS as an AI inference infrastructure platform with expanding operating leverage.


