


Cheniere Energy Inc. (LNG)




Down 6% in 4 Weeks, Here's Why You Should You Buy the Dip in Cheniere Energy (LNG)
Cheniere Energy (LNG) has become technically an oversold stock now, which implies exhaustion of the heavy selling pressure on it. This, combined with strong agreement among Wall Street analysts in revising earnings estimates higher, indicates a potential trend reversal for the stock in the near term.
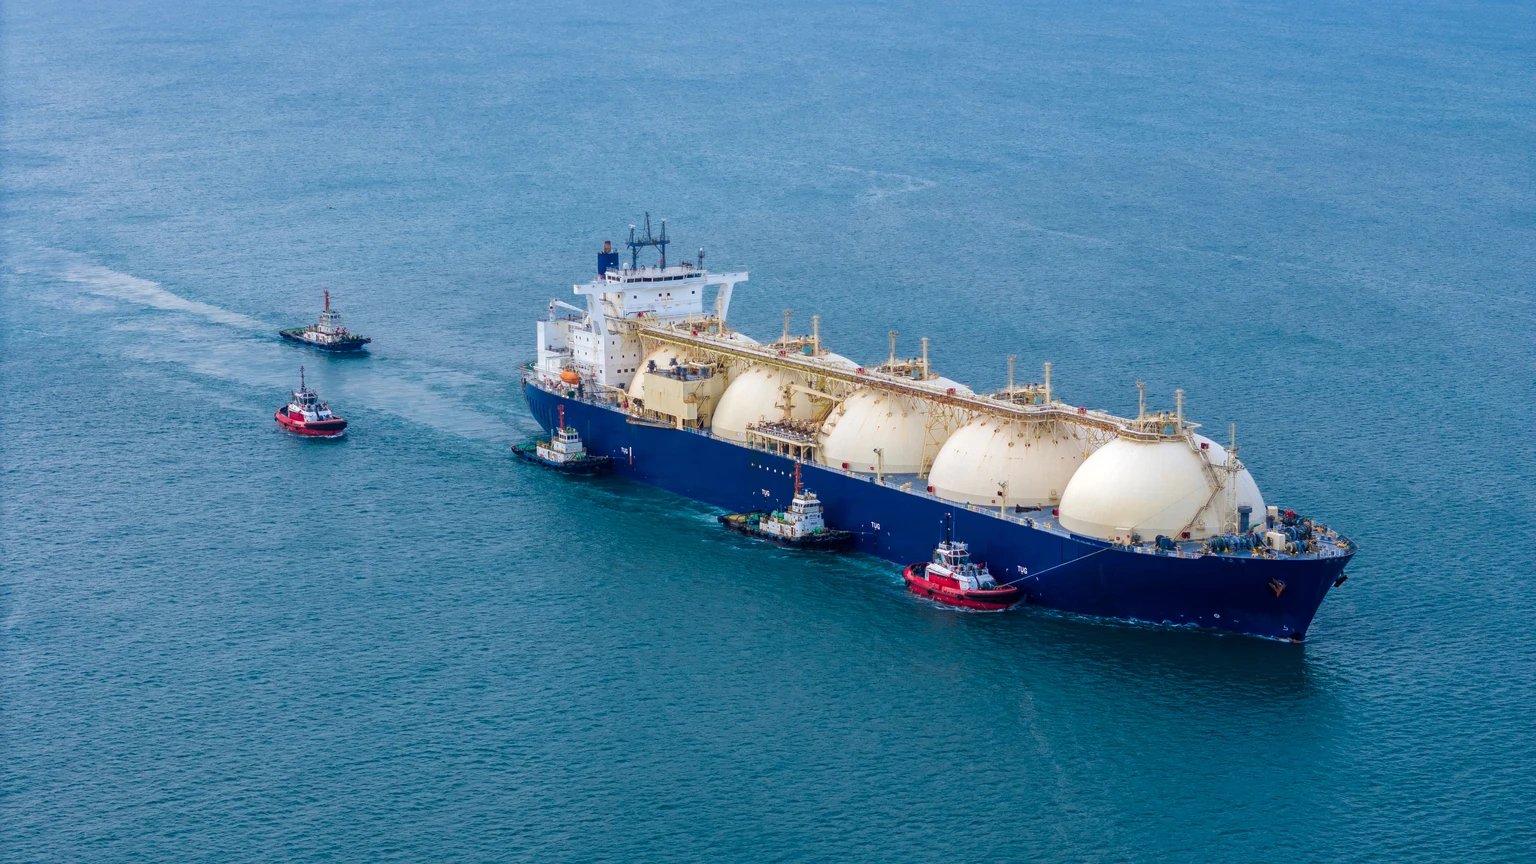
Golar LNG: Very Attractive Adj. Ebitda Growth Outlook
Golar LNG is rated a buy, positioned as the only proven independent operator in the floating LNG market. GLNG's liquefaction-as-a-service model enables rapid monetization of stranded gas, offering high-margin, long-term, infrastructure-like earnings with a $17 billion contracted backlog. GLNG's Argentina contracts provide a 20-year call option on global LNG prices, adding significant upside potential with limited downside risk.
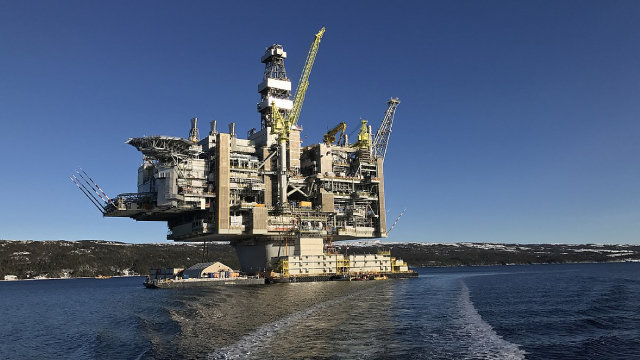
TotalEnergies: LNG, Portfolio Shifts And Capex Discipline Create Opportunity
TotalEnergies remains a solid buy, benefiting from strong natural gas, LNG, and energy exposure amid ongoing portfolio rebalancing. TTE is executing significant cost savings, CapEx cuts, and asset rebalancing while maintaining a robust dividend policy and scaling back buybacks due to macro uncertainties. Medium-term oil price support is possible from potential OPEC actions, global oil CapEx reductions, and rate cuts, with LNG growth providing additional catalysts.
Vopak secures key vessel for Australia LNG import project
Vopak has entered into an exclusive agreement with shipping firm Seapeak to provide a floating and regasification unit for its liquefied natural gas import terminal project in Australia, the Dutch tank storage firm said on Tuesday.
LNG is Shell's top contribution to energy industry over next decade, CEO says
Liquefied natural gas (LNG) will be European oil major Shell's biggest contribution to the energy industry over the next decade in terms of value and as it seeks to cut emissions from fossil fuel production, CEO Wael Sawan said on Monday.
Cheniere Energy: Buybacks, Dividends, And Further Upside, Despite LNG Glut Fears
Cheniere Energy remains a buy, despite long-term risks from China's pipeline deals and domestic gas production threatening future LNG demand. Cheniere's current business is insulated by long-term, fixed-fee contracts, ensuring robust cash flow and stability through the late 2020s and early 2030s. Management is leveraging strong cash flows for debt reduction, expansion, and aggressive shareholder returns, including buybacks and dividends.
Pembina Pipeline: Dividend Strength Meets LNG Expansion Potential
Pembina Pipeline Corporation is a North American midstream energy infrastructure company with interconnected value chains in natural gas, NGLs, and oil/condensates. PBA benefits from predictable cash flows due to a high proportion of take-or-pay contracts while maintaining moderate exposure to commodity price fluctuations and macroeconomic risks. Growth is expected from new assets, especially the Cedar LNG terminal, despite near-term delays in projects like Dow's Path2Zero cracker and elevated capital expenditures.
Australia's Woodside inks LNG supply deal with Turkey's BOTAS
Australia's Woodside Energy said on Wednesday it has clinched an agreement to supply about 5.8 billion cubic metres of liquefied natural gas, to Turkish state-owned petroleum company BOTAS.
Iraq signs joint operation agreement with France's TotalEnergies, QatarEnergy LNG
Iraq's oil ministry signed a joint operation agreement with France's TotalEnergies, QatarEnergy LNG and Iraq's Basra Oil Company, the Iraqi prime minister's office said on Sunday.
Woodside Energy and Petronas ink 15-year LNG supply deal
Australia's Woodside Energy said on Wednesday it had entered an agreement with Malaysia's state-owned Petronas to supply 1 million metric tons of liquefied natural gas per annum for 15 years, starting 2028.
Investors Underestimating U.S. LNG Export Growth
Domestic energy opportunities continue to draw investor attention as data center growth and utility demand ramps up. However, investors appear to have a less firm grasp on energy export expectations, specifically in relation to liquefied natural gas (LNG).
Cheniere Energy: Strong Performance, Solid Liquidity, And Market Opportunity To Support Its Valuation
Cheniere Energy is well-positioned for future growth, driven by rising global LNG demand, data center expansion, and energy security concerns. Strong revenue growth, stable margins, and robust liquidity support ongoing capacity expansion and dividend payouts, justifying the recent price surge. Valuation remains reasonable with some upside potential, despite technicals showing consolidation and a more neutral short-term sentiment.


