


Nio Inc. (NIO)



Will New Launches Drive NIO's Gross Margin Expansion in 2025?
NIO's rising vehicle margins, new model rollouts, and cost efficiencies signal improvement in overall gross margins.
Under $5 and Down 20% YTD, Is NIO Stock a Bargain Buy Now?
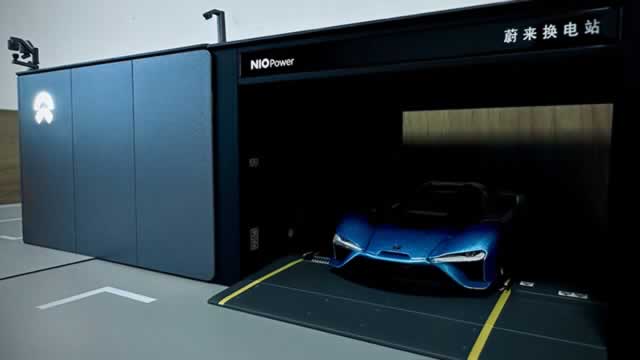
NIO Inc. NIO is a notable name in the Chinese EV market with several growth drivers in place. Vehicle deliveries are rising, new models are being rolled out, its battery swap technology gives it an edge, and the company continues to make progress in smart driving and operational efficiency.
NIO: Impact Of New Pricing War In China
NIO faces a new pricing war started by BYD in late May, but regulators could limit the headwinds due to these massive discounts. Vehicle margins improved to 10.2% in Q1 2025 compared to 9.2% in Q1 2024, despite the massive price war currently taking place in China. The company has projected 25% to 30% YoY growth in deliveries for the second quarter compared to the year-ago quarter.
Nio (NYSE: NIO) Stock Price Prediction and Forecast 2025-2030 (June 12)
The tariff-driven market volatility has been rough on shares of Chinese electric vehicle (EV) maker Nio Inc.
NIO: Too Cheap To Dismiss
NIO delivered strong EV growth, especially with ONVO and Firefly brands, but missed profit and sales estimates due to widening operating losses. Despite robust delivery momentum, NIO's profitability remains suboptimal, with operating losses rising 19% YoY, raising concerns about future equity dilution. NIO trades at a rock-bottom price-to-sales ratio, significantly below peers, offering potential upside if management can rein in operating losses.
NIO Expects Y/Y Rise in Q2 Deliveries: What are the Growth Agents?
NIO forecasts June and Q2 deliveries to rise year over year, fueled by fresh model rollouts.
NIO: Don't Give Up Just Yet
NIO missed Q1 estimates, reported significantly higher losses and a drop in vehicle margins despite strong delivery growth and success with its ONVO brand. ONVO's rapid ramp-up is driving delivery growth, but persistent high R&D and marketing expenses keep profitability out of reach for now. NIO announced an aggressive push into new markets in Europe in order to accelerate its delivery momentum.
NIO's Q1 Loss Wider Than Expected, Revenues Increase Y/Y
NIO posts wider-than-expected loss in the first quarter, with revenues rising year over year due to higher deliveries.

Banking giants update Nio stock price target
Chinese electric vehicle (EV) maker Nio (NYSE: NIO) has seen a flurry of price target revisions from major banking institutions following its first-quarter 2025 financial results.

NIO: More Disappointment From Q1 Earnings Report
NIO continues to miss aggressive growth targets, with shares falling towards their 52-week low despite new sub-brand launches. Q1 deliveries rose over 40% year-over-year, driven by the lower-priced Onvo brand, but revenue growth lagged due to lower ASPs. Q2 guidance was weaker than expected, but management hopes that sales will really jump in the second half of this year.

NIO Inc. (NIO) Q1 2025 Earnings Call Transcript
NIO Inc. (NYSE:NIO ) Q1 2025 Earnings Conference Call June 3, 2025 8:00 AM ET Company Participants Rui Chen - Head of Investor Relations William Li - Co-Founder, Chairman & CEO Yu Qu - Chief Financial Officer Conference Call Participants Bin Wang - Deutsche Bank AG, Research Division Jing Chang - China International Capital Corporation Limited, Research Division Ming-Hsun Lee - BofA Securities, Research Division Paul Gong - UBS Investment Bank, Research Division Tim Hsiao - Morgan Stanley, Research Division Tina Hou - Goldman Sachs Group, Inc., Research Division Yuqian Ding - HSBC, Research Division Operator Hello, ladies and gentlemen. Thank you for standing by for NIO Inc.'s First Quarter 2025 Earnings Conference Call.

NIO Q1 2025 Earnings: Widening Losses Cast Doubt On Breakeven Ambitions
Not only was NIO Inc.'s Q1 double-miss a disappointment, but the 211-bps q/q margin compression and limited Q2 delivery acceleration cast significant doubt on management's sales and profitability targets for 2025. The results represent a significant setback, as they contradict management's earlier commitment to driving sustained margin expansion on the back of ongoing cost-saving efforts and scaling new model deliveries. This accordingly heightens execution risks ahead for NIO, which will weigh further on the stock's near-term upside potential.


