


NVIDIA Corporation (NVDA)




How Nvidia Tried to Profit Twice From Every Chip Sale—and Why It Backfired
Nvidia announced a program to collect revenue on the same chip twice, once at sale and again through ongoing cloud profits, then paused it weeks later after internal warnings about antitrust exposure.
Nvidia: Analyzing Its Datacenter Customers In A Changing Environment
Nvidia Corporation remains a Buy as hyperscaler and NeoCloud demand drives robust growth and profitability. NVDA's valuation has declined to a 28x PE, yet earnings and margins remain strong with Q2 FY27 net income up 126% YoY. Capex growth from hyperscalers is a key driver; any slowdown or ROI deterioration poses a risk to NVDA's outlook.
Nvidia's Scarcity Runs Out in Five Years: ‘A Chip Designed by OpenAI, by AI'
Two days after the biggest quarter in semiconductor history, macro investor Jordi Visser told listeners on The Pomp Podcast that the scarcity holding up NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) has an expiration date.
Nvidia: This Is A Golden Opportunity
Nvidia Corporation forecasts approximately 70% revenue growth in fiscal 2028, far exceeding prior Wall Street expectations and driven by robust AI infrastructure demand. Vera Rubin platform shipments have begun, with management expecting them to account for 20% of data center revenue in Q3 and significantly increase per-gigawatt revenue. Half of NVDA's data center business now comes from sovereign, neo-cloud, and enterprise customers, growing at roughly 100% annually, with innovative revenue-sharing models expanding the addressable market.
Nvidia just made a $3.5 billion move that could expand its AI empire
An expanded partnership with MediaTek shows that Nvidia is interested in making its AI ecosystem compatible with the world of custom chips, a portfolio manager says.
Nvidia stock rises as company announces $3.5B investment in MediaTek
Nvidia NVDA shares rose nearly 1% on Monday after the chipmaker announced a $3.5 billion investment in Taiwan-based MediaTek, deepening a partnership focused on artificial intelligence (AI) infrastructure and data-center technology. Nvidia will purchase bonds convertible into MediaTek shares, according to a joint statement from the companies.
Nvidia's $3.5B MediaTek bet reveals its plan for tackling Big Tech's AI chip buildout
Nvidia is investing $3.5 billion into Taiwanese chipmaker MediaTek. As part of the deal, MediaTek will adopt Nvidia's technology that will help it design custom chips for AI companies and hyperscalers that can be plugged directly into Nvidia-based data centers.
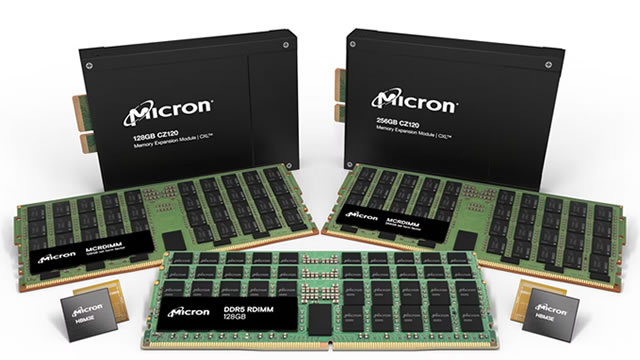
The Overlooked AI Bet That Could Outperform NVIDIA by 2027
Memory stocks quietly powered one of the steepest AI trades of the cycle, but Micron now sits at a crossroads where a blowout quarter and a $100 billion sales backlog collide with surging capex and insiders selling at a decade-high
Prediction: Nvidia Stock Will Trade at $350 on This Date
NVIDIA just posted the largest single quarter in semiconductor history, yet shares trade nearly 50% below where one price target says they belong. The math behind that gap reveals something Wall Street's consensus may be missing.
Nvidia Looks Like a Growth Stock Again. Watch Cathie Wood.
Nvidia stock is attractive to growth-focused investors again and Cathie Wood is leading the charge.
Here's how much you need to invest in NVDA to earn $100 from Nvidia's next dividend
Investors seeking to earn $100 from Nvidia's (NASDAQ: NVDA) next dividend payment will need to own 400 shares, based on its declared quarterly dividend of $0.25 per share.
Nvidia: Stock Price To Catch Up To Earnings Growth
NVIDIA is positioned for strong long-term growth, driven by advanced AI and data center solutions, notably the Vera Rubin architecture. NVDA's Vera Rubin platform is expected to achieve the fastest product ramp in company history, with broad adoption by hyperscalers and system OEMs. NVDA trades at a low PEG ratio of 0.50, reflecting an undervaluation due to its robust 3–5-year annual EPS growth estimate of 49%.


