


Target Corporation (TGT)




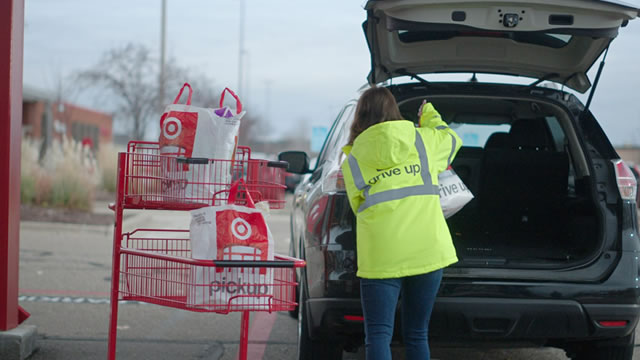
Target's Digital Growth Story Gains Strength With Same-Day Delivery
TGT's digital growth accelerates as same-day delivery surges, with stores powering faster fulfillment and stronger online sales momentum.
Centerra Gold: Why I Am Raising My Price Target
Centerra Gold remains a Strong Buy in my view, with my price target increasing from $24.30 to $28 per share. Öksüt, Mount Milligan, and Thompson Creek are driving the next leg of the thesis. Öksüt's 2026 production guidance increased to 120K to 135K ounces without a higher AISC range. My SOTP points to $28 per share, with Mount Milligan valued at about $2.14 billion, Öksüt at $1.05 billion, and Thompson Creek at $850 million, while Goldfield and Kemess remain heavily discounted in my model.
Halloween Costume Controversy Threatens Target's Hard-Won Recovery
A children's Halloween costume pulled from Target's shelves is threatening far more than a single product line. It is testing whether the retailer's celebrated comeback has the brand trust to survive another culturally charged misstep.
Figma Stock Price Prediction: Wall Street's $30 Target May Be Too Low
Figma has lost more than half its value since IPO even as revenue growth accelerated, creating a rare tension between a beaten-down chart and fundamentals that are quietly getting stronger.
How High Can Nvidia Stock Go? Wall Street's Next Target May Surprise You
Nvidia just posted 105% revenue growth yet its stock is barely moving, and Wall Street's price targets tell a story that gets more surprising the further out you look.
Target Just Proved the Turnaround Is Real. Here's What Comes Next.
Target just posted its strongest quarter in years, and shares have already surged 78% in 2025, yet Wall Street still refuses to turn bullish. Here is why that skepticism could be the biggest opportunity hiding in plain sight.
Target or Lowe's: Whose Dividend Streak Cracks First?
Target and Lowe's both reported earnings on the same day while defending dividend streaks built over decades, but the balance sheets underneath those payouts tell very different stories about which one is actually safe.
Nvidia: Compressing Multiples And A $260 Technical Target
Nvidia Corporation demonstrates robust business growth, with revenue forecasted to rise from $96B to $108B and forward P/E compressing to 23. Despite competitive threats and overproduction fears, NVDA's absolute revenue gains outpace rivals, supported by a second wave of sovereign and corporate demand. The consolidation pattern on NVDA's chart, coupled with strong fundamentals and neutral technicals, signals a high-probability breakout toward $260–$265.
Intercorp Financial Services: Strong H1 Earnings Support A Higher Target Price
Intercorp Financial Services delivered a strong Q2, with a net profit of S/585 million, exceeding Wall Street expectations. H1 earnings reached S/1.2 billion and ROE 18.9%, putting IFS on track for roughly S/2.4 billion of 2026 net income, above our previous S/2.2 billion estimate. Loan growth and higher-yielding lending, alongside improved fee income, support a positive earnings outlook and a higher target price.
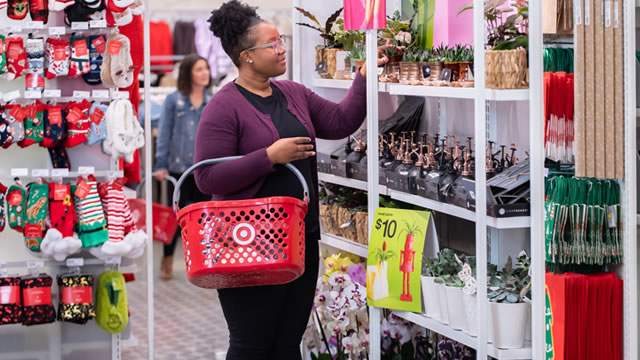
Target Stock Falls After ‘Offensive' Halloween Costume Pulled Amid Backlash
Major stock market indexes are up Tuesday, with Target's drop placing it among the day's top three losers on the S&P 500 as of shortly before 2 p.m. EDT.
Wells Fargo Hits 17%-18% ROTCE Target: Can It Sustain the Momentum?
Wells Fargo & Company WFC has made significant progress in improving profitability following years of regulatory restrictions and operational restructuring. The bank's return on tangible common equity (ROTCE) improved from 8% in the fourth quarter of 2020 to 14.6% by the end of 2025.
Sandisk: The Hidden Mechanism Behind Its 80% Margin Target
Sandisk Corporation is rated a Buy, supported by new multi-year business models (NBMs) that secure $93.9 billion in minimum revenue and greater demand visibility. SNDK's NBMs are structured to allow the company to retain most manufacturing cost reductions, targeting sustainable 80% gross margins and 50% adjusted free cash flow margins. Detailed customer forecasts and disciplined supply growth enable SNDK to better align production with demand, reducing historical risks of overproduction and margin erosion.


