


Advanced Micro Devices Inc. (AMD)




AMD: Q3 Earnings Reset Expectations, Growth Acceleration Phase Warrants Higher Valuation
Advanced Micro Devices experienced a significant pullback following a slight miss on 4Q revenue and a weaker-than-expected margin profile, leading to an in-line EPS result for 3Q. Its Data Center GPU business remains robust in 3Q, driven by strong AI demand that accelerates overall revenue and EPS growth, despite a declining Gaming and Embedded revenue. Despite anticipated gross margin expansion in 4Q, AMD management noted that the margin profile is currently below the corporate average as the company prioritizes demand growth.
Advanced Micro Devices Brought Impressive Q3 Results: Buy When Others Are Fearful
Advanced Micro Devices, Inc.'s recent sell-off (over 10%) raises a key question — does 'buy when others are fearful' apply? Some analysts raised concerns about future growth prospects, but their approach may not apply to long-term oriented investors. I don't expect AMD to overthrow Nvidia, but I believe it will still have enough room to expand, gain market share, and benefit shareholders.
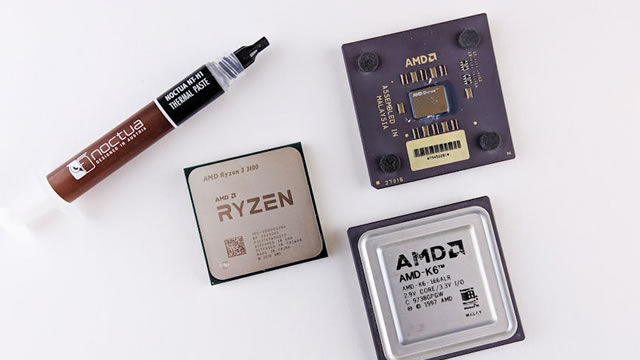
Chip Stock Due for Short-Term Bounce
Shares of Advanced Micro Devices Inc (NASDAQ:AMD) are extending yesterday's 10.6% post-earnings drop , down 3.1% at $144 at last glance and breaking into negative territory for the year.
Meta and AMD Race to Meet Demand for AI With Infrastructure Push
Tech giants are pouring unprecedented resources into artificial intelligence (AI) infrastructure as Meta plans up to $40 billion in 2024 spending and AMD rides the wave to record $6.8 billion in revenue.
Wall Street sets Eli Lilly stock price for the next 12 months
The ongoing earnings season has been filled with surprises in both directions. Some notable examples are Advanced Micro Devices (NASDAQ: AMD), which severely disappointed investors, and Garmin (NYSE: GRMN), which proved a surprise blockbuster.
These 2 Stocks Gained 3,000% Over the Past Decade. No, They're Not Nvidia and AMD.
AI chips powered the top two stock returns among current S&P 500 members over the past decade. For Nos. 3 and 4, think credit scores and lumber.
AMD Q3: Buy The Dip As Data Center Growth Is What Counts
I maintain a Buy rating on Advanced Micro Devices, Inc. shares despite short-term valuation concerns, as Q3 results highlighted strong AI-driven growth in the Data Center segment. AMD's Q3 revenue reached $6.8 billion, beating estimates, with Data Center revenue up 122% year-over-year, driven by AI demand. Weakness in the Gaming and Embedded segments is overshadowed by AI growth; management would be wise to focus capital on Data Center opportunities for now.
AI Is Starting to Hurt Earnings, and It Could Get Worse
24/7 Wall St. Insights Advanced Micro Devices Inc. (NASDAQ: AMD) and Microsoft Corp.
AMD Stock Drops On Q4 Outlook As 10 Analysts Highlight 'Long-Term AI Growth Opportunity,' Nvidia Rivalry
Advanced Micro Devices Inc AMD analysts make a case for the company to gain market share in several sectors as it works to compete against NVIDIA Corp NVDA and grow its AI business, as evidenced in third-quarter results.
AMD Earnings Show Power Of Nvidia Software, ADP Data Defies Expectations
To gain an edge, this is what you need to know today.
AMD CEO Lisa Su says GPU and CPU sales are nearly equal. Wall Street thinks that's not enough.
AMD's GPU sales are nearing CPU sales, driven by AI data center demand. AMD raised its 2024 GPU sales forecast to over $5 billion, up from $4.5 billion.
AMD Q3 Earnings Beat Estimates, Shares Down on Weak Q4 View
Advanced Micro Devices' Q3 2024 results reflect robust Client and Data Center revenues, offsetting weakness in the Gaming and Embedded segments.


