


Advanced Micro Devices, Inc. (AMD)





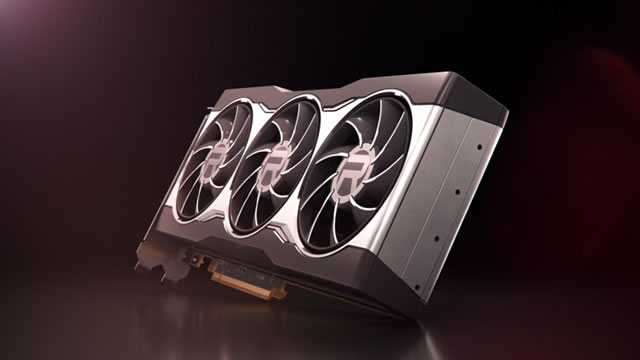
New Ryzen PRO 9000 Offerings Lift AMD's Client & Gaming: What's Ahead?
Advanced Micro Devices unveils Ryzen PRO 9000 workstation chips with 3D V-Cache, boosts performance for AI, simulation and gaming, with rollout set for H2 2026.
AMD Stock: I Called The Surge - Here's What Comes Next
Advanced Micro Devices, Inc. shares are surging, up 75% in the last month. CPU prices are rising as agentic AI demand explodes. AMD continues to execute in both CPUs and GPUs.
If Lisa Su Is Right, AMD Could Be as Big as Nvidia
Lisa Su's pitch on the Q1 call had a specific shape. She's arguing that the ratio of CPUs to GPUs inside an AI data center is about to collapse.
5 Companies Are Betting on Trump's China Pivot. Here's Who's Best Positioned.
President Trump's posture toward China has whipsawed markets for over a year, with prediction markets confirming tariffs escalated from 10% to 40% to 100% between February and June of last year.
EyePoint: DURAVYU's Durability Could Drive Significant Upside
EyePoint is rated a clear BUY, with central-case DCF modeling indicating roughly 2x upside from current levels. DURAVYU, EYPT's lead candidate for wet AMD and DME, has demonstrated a compelling durability profile in Phase 2 and could benefit from a large, high-turnover wet AMD market if confirmed. Probability-adjusted DCF values DURAVYU at ~$2.9B pre-dilution, with a final equity value of ~$2.3B and ~$27/share after an estimated 20% dilution.
Wall Street Is Worried About a ‘Sizzling' Semiconductor Trade. History Says Cooling Periods Like This Set Up the Next Leg Higher
Although the chip complex has spent the last six months looking unstoppable, Wall Street is starting to whisper that the heat may finally be coming out of the trade.
Advanced Micro Devices Shareholders Back Board as Lisa Su Touts AI Growth
Advanced Micro Devices NASDAQ: AMD used its 2026 Annual Stockholders Meeting to secure shareholder approval for its director slate and key governance items, while Chair and CEO Lisa Su outlined the company's growth strategy centered on artificial intelligence and data center computing.
AMD Jumps 76% in a Month: Is There More Room for the Stock to Rise?
AMD is up 75.8% YTD as EPYC and Instinct drive data-center growth, but stiff competition and a pricey P/E leave the stock a hold.
Wall Street Splits on AMD: BofA Hikes Price Target to $500, Daiwa Downgrades on Valuation
The Wall Street debate over Advanced Micro Devices (NASDAQ:AMD | AMD Price Prediction) crystallized on May 13, 2026, when two major firms reached opposite conclusions on the same stock.
Where Would Nvidia And AMD Be Today Minus U.S. Export Controls?
The Chinese Communist Party (CCP) must be thrilled. See last month's release of DeepSeek's latest AI.
AMD: The Bull Case Has A Fatal Flaw
Advanced Micro Devices, Inc. has reported strong Q1 results, with 38% Y/Y revenue growth and a 57% expansion in the Data Center segment, benefiting from the AI boom. Despite operational momentum, AMD remains a secondary player to Nvidia, with weaker margins and higher operating costs limiting leverage and profitability. The current market price reflects overly optimistic expectations, with intrinsic value estimated at $202.05 per share—about 56% below the prevailing price.
AI-Boosted Earnings Keep Institutions Buying AMD
Shares of Advanced Micro Devices, Inc. (AMD) up 4,171% since 1992's initial outlier inflow.


