


Bloom Energy Corporation (BE)



3 Reasons AI Stocks are Primed for a Rebound
While recent market turbulence tested momentum, the washout of extreme leverage combined with surging multi-year infrastructure spending and real-world biotech breakthroughs means the AI rally is far from over.
Bloom Energy: Pelosi Buys And Sell-Side Earnings Hikes, Reiterate 'Buy'
Bloom Energy remains a "Buy," supported by robust EPS growth, improved guidance, and attractive PEG valuation despite recent volatility and a 21% pullback since June. Q2 results exceeded expectations: non-GAAP EPS of $0.78 vs. $0.41 consensus and revenue up 167% YoY, with gross margin expanding by 604 bps to 34.3%. Management raised FY 2026 guidance, targeting $3.9–$4.2 billion in revenue, 34% gross margin, $800–$900 million operating income, and $2.55–$2.85 EPS.
Plug Power Falls 4%, Bloom Energy Moves Up as the Hydrogen Trade Divides
The hydrogen and fuel-cell trade is splitting in two Monday, and the sector fund tells almost none of that story.
Wall Street Analysts See a 36.89% Upside in Bloom Energy (BE): Can the Stock Really Move This High?
The mean of analysts' price targets for Bloom Energy (BE) points to a 36.9% upside in the stock. While this highly sought-after metric has not proven reasonably effective, strong agreement among analysts in raising earnings estimates does indicate an upside in the stock.
Bloom Energy: Factory-Built Power Is Becoming AI's Fastest Route To Scale
Bloom Energy is positioned to address the AI-driven power bottleneck with factory-built, modular onsite generation solutions tailored for data centers. Oracle's multi-gigawatt commitment and Brookfield's expanded $25B financing framework anchor BE's demand and enable scalable project deployment. BE's Q2 results showed 166% revenue growth, 34.3% non-GAAP gross margin, and positive operating cash flow, supporting a Buy rating with a $245 price target.
$5,000 in Bloom Energy at Its COVID-Era Low Would Be Worth This Much Now
Bloom shares are trading at about $202 today. During March 2020, Bloom shares sank to $3 a share.
Can Bloom Energy Keep Beating the Market?
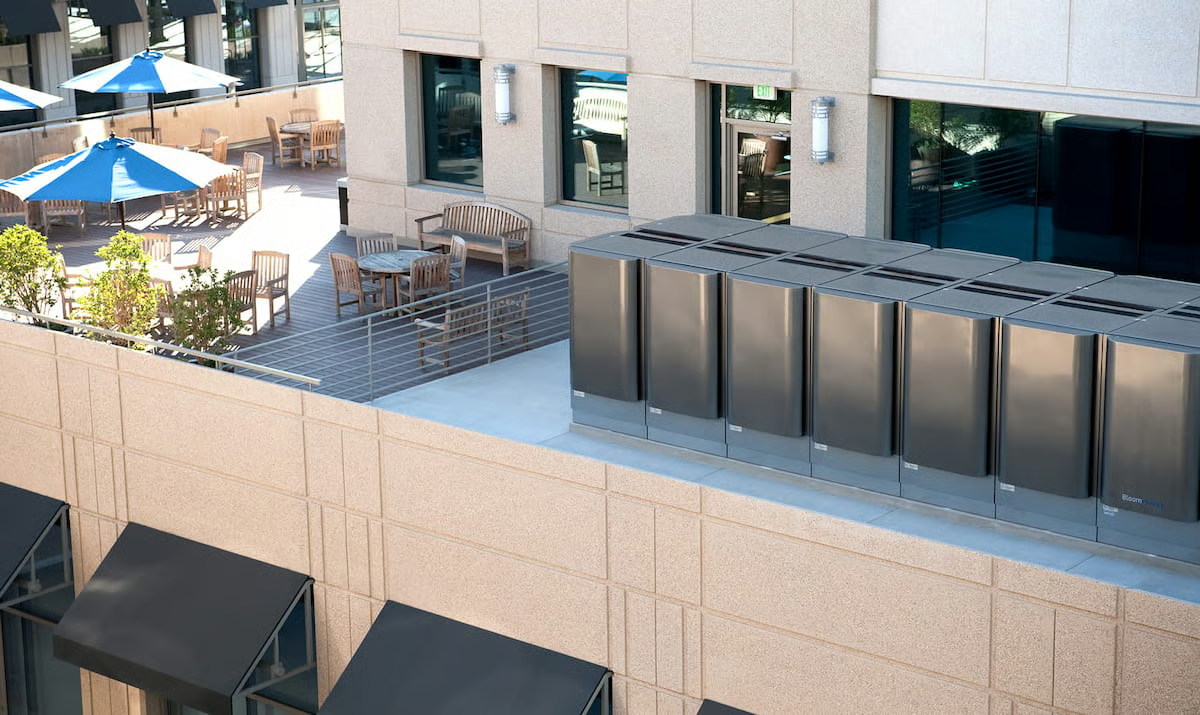
Bloom Energy has posted enormous revenue growth due to high demands for its energy systems. Its most recent product will reduce installation time by 40%, potentially speeding up deployments.
FuelCell Energy Jumps 5%, Plug Power Climbs 4%, Bloom Energy Slips as the Hydrogen Trade Splits
The hydrogen trade is splitting Friday, refusing the tidy “yesterday's rout reverses” script that a bounce after Thursday's selloff might have suggested.
Here's why the Bloom Energy stock is losing momentum despite its growth
Bloom Energy stock has slumped sharply in recent weeks, falling from its year-to-date high of $350 to around $200. The stock has declined for seven consecutive sessions, reaching its lowest level since August 3.
Bloom Energy: It Is Springtime For This Company's Growth And Profitability
Bloom Energy is recommended as a buy at ~$200/share, driven by explosive demand from AI data center power needs and rapid deployment capabilities. BE's revenue growth has inflected to hypergrowth, with Q/Q revenue up 42%, Y/Y revenues up 166%, and full-year guidance raised to 100% growth with a 22% non-GAAP operating margin. Major contracts with Nebius, Oracle, Equinix, and a $25B Brookfield financing commitment underpin a $20B backlog and robust forward visibility.
FuelCell Energy Sinks 8%, Bloom Energy Falls 3%, Plug Power Drops 3%: What's Behind the Hydrogen Stock Selloff?
Hydrogen and fuel cell names are selling off together Thursday afternoon, and the damage is spreading unevenly across the group.
Nvidia Chip-Filled Data Centers Need More Power Than Any Utility Can Promise. Here's Who Actually Wins.
Modern data centers powered by advanced Nvidia chips require significantly more power compared to traditional setups. Technology companies have signed some major long-term power purchase agreements with independent power producers.


