




Carter's: In Fairly Valued Territory, But There Will Be Better Opportunities Later
Carter's 2Q24 results disappointed the market, with retail sales continuing to fall in double digits. Management blames macroeconomic reasons, and argues that competitors are doing heavy discounting. There is evidence sustaining both claims. Today, Carter's trades at a P/E for FY24E of around 10x and at a P/B of 2.5 compared with a 15-year average ROE of 25%, attractive figures.

Carter's (CRI) Q2 Earnings Beat, Retail Comps Down 11.7%
Carter's (CRI) posts soft sales results in second-quarter 2024, owing to weak sales across the U.S. Retail and International segments.

Carter's, Inc. (CRI) Q2 2024 Earnings Call Transcript
Carter's, Inc. (NYSE:CRI ) Q2 2024 Earnings Conference Call July 26, 2024 8:30 AM ET Company Participants Sean McHugh - Vice President and Treasurer Michael Casey - Chairman, President and Chief Executive Officer Richard Westenberger - Senior Executive Vice President, Chief Financial Officer and Chief Operating Officer Kendra Krugman - Senior Executive Vice President, Chief Creative and Growth Officer Conference Call Participants Jay Sole - UBS Warren Cheng - Evercore ISI Ike Boruchow - Wells Fargo Securities, LLC Tom Nikic - Wedbush Securities Kelly Crago - Citigroup Inc. Operator Welcome to Carter's Second Quarter Fiscal 2024 Earnings Conference Call. On the call are Michael Casey, Chairman and Chief Executive Officer; Richard Westenberger, Chief Financial Officer and Chief Operator Officer; Kendra Krugman, Chief Creative and Growth Officer; and Sean McHugh, Treasurer.

Carter's (CRI) Q2 Earnings Beat Estimates
Carter's (CRI) came out with quarterly earnings of $0.76 per share, beating the Zacks Consensus Estimate of $0.45 per share. This compares to earnings of $0.64 per share a year ago.

Carter's (CRI) Stock Dips 23% in 3 Months: What You Should Know
Carter's (CRI) is battling with various uncertainties such as troubles in the business environment, inflation, generational high interest rates, higher consumer debt levels and recession risks.
Two Undervalued Dividend Opportunities For June 29th, 2024
This series looks for opportunities in undervalued dividend-paying companies. Carter's shows consistent operating margins and growth potential, but comes with the risk of a declining market due to lower birth rates. UPS faces challenges from rising costs and competition, but plans for consolidation of sorting facilities presents a significant opportunity for cost savings.
Carter's: An Investment That Is Appealing To More Than Just Parents
Carter's is a household name for anyone with a child ranging from infant to pre-teen. The Children's Place is going through some rough times and CRI is bound to benefit from PLCE's store closures and potential exit from the Canadian market. Carter's main risk is a declining birth rate, but this may be exacerbated by other factors including the median age of marriage.
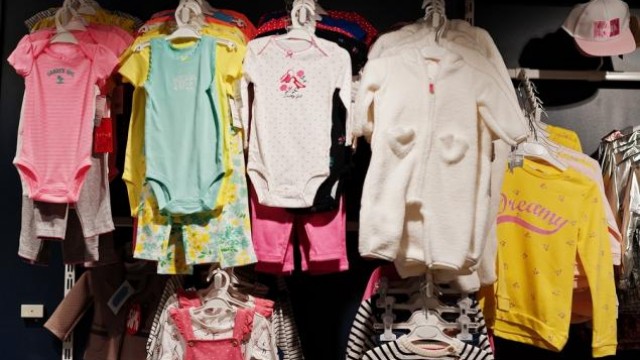
Carter's (CRI) Gains From Robust Strategies Amid Inflation Woes
Carter's (CRI) pricing strategy, efficient inventory management and enhanced product offerings have been driving growth amid the ongoing unfavorable impact of inflation.


