


First Commonwealth Financial Corp. (FCF)
 NYSE NYSE Primary
 XFRA

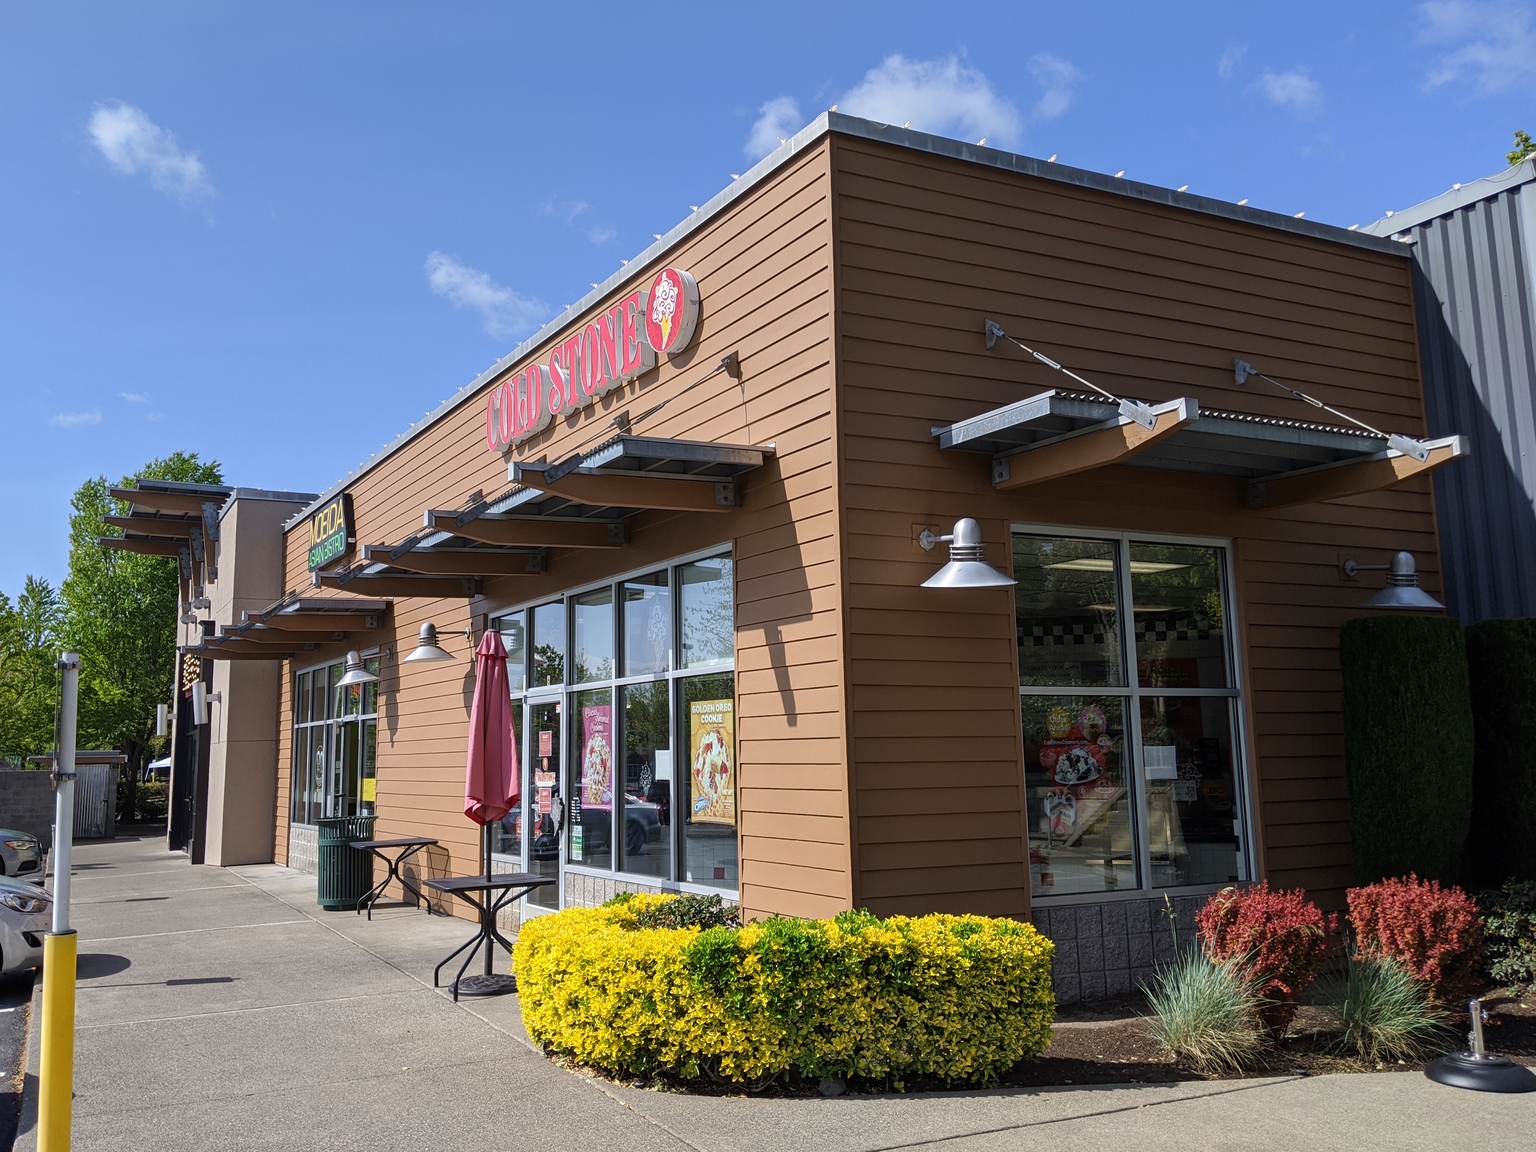
MTY Food Group: 5 Reasons Why Mr. Market Is Wrong On This Canadian Restaurant Operator
MTY Food Group trades at just 6x FCF, offering a 16% FCF yield and deep value for a historically cash-generative, diversified, asset-light franchisor. Cold Stone Creamery and Wetzel's Pretzels alone are conservatively worth nearly MTY's entire market cap, highlighting significant undervaluation. Despite declining same-store sales, MTY's FCF/share, dividends, and buyback potential remain robust, with most brands performing steadily except Papa Murphy's.
Cerebras: Can It Challenge The Data Center Chip Market?
Cerebras' wafer-scale ASICs deliver industry-leading memory bandwidth and output speeds, positioning it to capture rising AI inference demand despite GPU dominance in training. The OpenAI deal, valued at over $20 billion, is expected to drive rapid revenue growth but creates significant customer concentration and requires heavy upfront capex. Near-term FCF margins will likely remain negative due to data center expansion, with positive FCF margins forecasted only by 2029 as scale and margins improve.
Chord Energy: Q2 Strengthens The Buyback And FCF-Per-Share Thesis
Chord Energy demonstrates disciplined capital allocation, prioritizing free cash flow per share through operational efficiency, aggressive buybacks, and a clean balance sheet. Q2 results validate the thesis: FCF exceeded expectations, oil production hit guidance highs, and share count fell meaningfully, driving per-share value growth. Management commits to returning at least 75% of adjusted FCF to shareholders from Q3, primarily via buybacks, while maintaining a $1.30 quarterly base dividend.
Central Garden & Pet Company: The 10% FCF Yield PE Arbitrage Nobody's Pricing In
Central Garden & Pet offers 45% upside to a $65 base-case target, driven by discounted valuation and strategic expansion. The TRIXIE acquisition establishes CENT as a global leader, unlocking European growth and M&A opportunities at attractive multiples. Portfolio optimization and a shift to branded products have expanded margins to ~13%, with 10.3% FCF yield and robust buybacks.
Free Cash Flow ETFs: How VictoryShares Matches FCF Strategies to Advisor and Client Needs
Two recent TMX VettaFi advisor polls found that unfamiliarity with free cash flow (FCF) yield and portfolio integration are the top hurdles to broader adoption of FCF strategies. The findings shape how VictoryShares and Solutions positions its FCF ETF suite for advisors navigating today's market.
Magnera Corporation: Executing But Abandoned
Magnera Corporation (MAGN) is executing well post-merger, integrating operations, growing earnings, and reducing leverage in the nonwoven industry. MAGN trades at 5.5x FY26E EBITDA versus peers at 9x, with a ~20% FCF yield, highlighting a significant valuation disconnect. Management expects FY26 EBITDA towards the low end of $380–410m and FCF of $90–110m, with potential for >$400m EBITDA and $120m FCF in FY27.
Western Digital's $3.5B FCF: Can Growth Continue in Fiscal 2027?
WDC generates $3.5 billion in fiscal 2026 FCF as demand, pricing and high-capacity drives boost margins and cash flow.
Talen Energy: Very Solid FCF Yield, With More Upside If Data Center Pipeline Converts
Talen Energy remains a buy, with robust FCF growth visibility driven by data center demand and the Cornerstone acquisition. TLN raised 2026 adj. EBITDA guidance to $2.025–2.225 billion and adj. FCF to $1.2–1.35 billion, excluding Keystone, implying further upside. The 2028/2029 PJM capacity auction and a growing data center pipeline underpin a more predictable, resilient earnings base and margin mix.
Nvidia: Durable FCF As Company Expands Beyond Datacenter GPUs
Nvidia (NVDA) is initiated with a buy rating, driven by exceptional free cash flow generation and reasonable valuation multiples versus peers. NVDA's FCF reached $96.6B in FY26, with plans to return over 50% to shareholders and an $80B buyback boost. Customer diversification beyond hyperscalers and resilient GPU pricing trends support durable growth and reduce cyclicality risks.
Amazon: $1T AWS Ambition As Growth Accelerates - Ignore FCF/Debt Noise
AWS drives 60.3% of Amazon's operating income, with accelerating revenue/margin expansion and demand growth across custom chips/SaaS/compute backlog. These support AMZN's aggressive capex guidance and doubled AWS power capacity plans through 2027, supporting a long-term $1T annual revenue target. The elongated data center/server useful life may reduce depreciation risks, allowing them to deliver positive FCF from 2027 onwards, aided by accelerating commerce/ad/subscription trends.
ExxonMobil: A Capital Return Play Amid Soaring FCF
ExxonMobil benefits from elevated crude prices driven by Middle East conflict, supporting strong Q2 earnings and revenue outperformance. XOM trades at a forward P/E of 14.6x FY 2027 earnings, slightly cheaper than Chevron, positioning it attractively among mega-cap energy peers. Capital returns and free cash flow are accelerating as higher price realizations boost financial performance amid ongoing geopolitical tensions.
SM Energy: A Bigger, Cheaper Company Than The Tape Suggests
SM Energy is rated a buy post-merger, offering a compelling risk/reward with ~15% FCF yield and 20-50% upside. The merger with Civitas created a top-10 US independent, unlocking $375M in annual synergies and a diversified, high-margin asset base. SM's deleveraging flywheel accelerates value: 80% of FCF targets debt reduction, flipping to buybacks as leverage approaches 1x.


