



First Commonwealth Financial (FCF) Q4 Earnings: Taking a Look at Key Metrics Versus Estimates
While the top- and bottom-line numbers for First Commonwealth Financial (FCF) give a sense of how the business performed in the quarter ended December 2025, it could be worth looking at how some of its key metrics compare to Wall Street estimates and year-ago values.
First Commonwealth Financial (FCF) Beats Q4 Earnings and Revenue Estimates
First Commonwealth Financial (FCF) came out with quarterly earnings of $0.43 per share, beating the Zacks Consensus Estimate of $0.41 per share. This compares to earnings of $0.35 per share a year ago.
Antero Resources: Projected FCF Boosted By Recent Transactions
Antero Resources made some deals that are adding around 700 MMCFE per day to its production for $2 billion in net cash. It divested Utica Shale assets that it hadn't been developing recently and added Marcellus Shale assets. Antero expects its pro forma 2026 free cash flow to increase by close to $500 million due to the acquisitions.
Vista Energy: Strong Buy Confirmed After Analyst Day
Vista Energy is executing a high-growth, export-driven strategy in Argentina's Vaca Muerta shale, delivering industry-leading profitability and operational scale. VIST targets production of 180,000 boe/d and $2.8B EBITDA by 2028, with $1.5B cumulative FCF and leverage below 1x, even at modest oil prices. Operational efficiency, low costs ($11/boe), export expansion (75% of revenues by 2028), and firm FCF targets underpin a robust risk/reward profile.
GE Vernova: The AI Power Bottleneck Trade Is Far From Over
The December 8 update was very encouraging for GE Vernova, with a sequential 2026 margin and FCF step-up, and 2028 targets are now higher on revenue, 20% EBITDA, and >$22B cumulative FCF. The narrative is intact. Power generation and electrification are both in high demand in the AI data center buildout. Power is effectively sold out through 2028 (and largely into 2030), with a backlog skewed to high-margin services ($65B services vs. $19B equipment within $84B power RPO).
Imperial Brands: Great Value At 9x Forward Earnings, With 5% Yield Backed By Strong FCF
Imperial Brands benefits from a combustibles segment with modest revenue growth and very strong operating margins. In the firm's top national markets, it enjoys significant pricing power, reinforcing future cash flows and consequently dividends and buybacks. The NGP (non-combustible) segment is small compared to that of peers like Philip Morris but is moving rapidly towards profitability on account of increasing scale.
VerticalScope: Undervalued, We Keep Buying
VerticalScope is deeply undervalued, trading at just over 4x FY2025E EV/FCF, with market fears overblown. Despite declining MAU, FORA achieved strong FCF growth and expanded margins through cost-cutting and higher ARPU. Traffic appears to have bottomed, with October MAU rebounding and direct users up nearly 60% year-over-year.
Petco Health and Wellness: Business Is Stabilizing, But Not Enough (Rating Upgrade)
Petco Health and Wellness is upgraded to Hold as margin and FCF improve, but top-line weakness persists. WOOF's Q3 showed 21% y/y adjusted EBITDA growth and $61M in Q3 FCF, reflecting effective cost control and better inventory management. Net sales declined 3.1% y/y and comparable sales fell for the third consecutive quarter, highlighting ongoing brand and demand challenges.
Barrick Mining: Still Undervalued Despite Record FCF, Mali Agreement, CEO Change, And Activist Involvement
Barrick Mining Corporation (B) remains a top gold mining pick, with strong financials, Tier One gold and copper assets, and a robust global project pipeline. B delivered record Q3 cash flow, is advancing non-core asset divestitures, and maintains a solid balance sheet with improving net cash and dividend policy. Key catalysts include resolution of Mali disputes, Elliott Management's activist stake, CEO transition, and major projects like Reko Diq and Lumwana expansion advancing.

Coeur Mining's FCF Surges on Strong Output and Lower Capex
CDE's witnesses record free cash flow on stronger production, higher metal prices and sharply reduced capex.

AngloGold: Delivering Record FCF In Q3 Keeps The Bullish Case Intact
AngloGold Ashanti (AU) delivered record Q3 2025 free cash flow of $920M, driven by strong gold prices, production growth, and cost control. AU achieved a 61% year-over-year increase in gold sales revenue and a 185% surge in net income, with EBITDA margin expanding from 51% to 66%. Operational highlights include robust African mine contributions, especially from Sukari, and disciplined cost management, supporting a 9% FCF yield and 4.5% dividend yield.
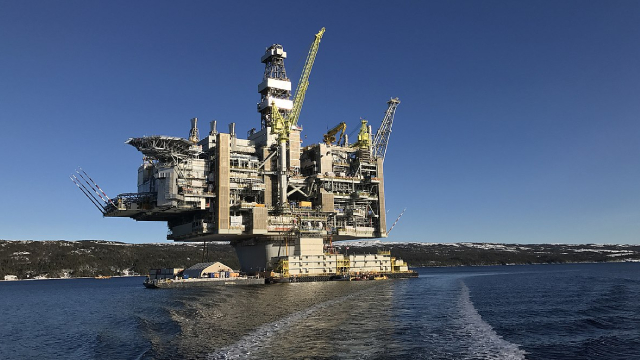
Devon Energy: Profit From Cost Control And FCF Growth
Devon Energy Corporation is rated a "Buy," supported by a competitive cost structure and new long-term natural gas contracts. DVN benefits from a low break-even oil production cost, outperforming sector peers and enhancing profitability potential. Key risks include market volatility, negative Levered FCF Margin (-8.3%), and high debt levels, which require close monitoring.


