


Hudbay Minerals Inc. (HBM)



HudBay Minerals (HBM) Misses Q2 Earnings and Revenue Estimates
HudBay Minerals (HBM) came out with quarterly earnings of $0.28 per share, missing the Zacks Consensus Estimate of $0.3 per share. This compares to earnings of $0.19 per share a year ago.
The Post-IPO Pullback Creates A Great Entry Point For SK Hynix
I am initiating SK Hynix (SKHY) with a Strong Buy rating and a $258 price target, implying 67% upside. SKHY's growth should come from the HBM3E-to-HBM4 transition, rising demand for high-capacity server DRAM and SOCAMM2, and the expansion of Solidigm's enterprise SSD business. Together, these growth drivers support my estimate of approximately $17.19 in 2027 EPS.
Unveiling HudBay Minerals (HBM) Q2 Outlook: Wall Street Estimates for Key Metrics
Looking beyond Wall Street's top-and-bottom-line estimate forecasts for HudBay Minerals (HBM), delve into some of its key metrics to gain a deeper insight into the company's potential performance for the quarter ended June 2026.
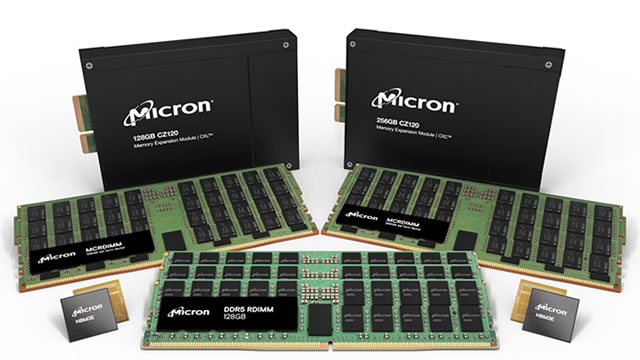
Micron Boosts HBM4 Ramp-Up: Will It Help MU Lead the AI Memory Race?
MU's faster HBM4 ramp-up, rising AI demand and quicker yield gains are likely to aid revenues, profitability and its AI memory position.
HudBay Minerals (HBM) Increases Despite Market Slip: Here's What You Need to Know
HudBay Minerals (HBM) closed at $23.55 in the latest trading session, marking a +2.39% move from the prior day.

HudBay Minerals (HBM) Earnings Expected to Grow: Should You Buy?
HudBay Minerals (HBM) doesn't possess the right combination of the two key ingredients for a likely earnings beat in its upcoming report. Get prepared with the key expectations.

SK Hynix's HBM Empire Powers 65% US Revenue — Is This the Must-Own AI Stock?
The artificial intelligence revolution has transformed the semiconductor landscape in ways few predicted even two years ago.

Micron: It Does Not Need To Beat SK Hynix At Nvidia
Micron Technology (MU) is rated Buy, with upside driven by expanding HBM demand beyond Nvidia, particularly from hyperscaler custom AI accelerators. MU targets maintaining a ~22% HBM market share, matching its DRAM share, as custom ASICs become a larger HBM demand source. Micron's HBM4 is in volume production, with qualification samples sent to multiple customers, but a named non-Nvidia win remains a key inflection point.

SK Hynix: Strong HBM Tailwinds, But Mind ADR Premium And The Cycle
SK hynix is rated Strong Buy, driven by its dominant HBM market share and temporary HBM pricing headwinds creating mispricing. SKHY's profitability surge is underpinned by unprecedented memory price increases and a strategic shift toward high-margin DRAM and HBM products. I see likely upcoming long-term supply contracts as a strong catalyst. Persistent capacity constraints are expected to sustain elevated margins and ROIC through at least 2028.
SK hynix Has Room For Another Leg Up
SK hynix is the current HBM leader, with roughly 58% market share and strong exposure to Nvidia's AI platform roadmap. HBM remains supply-constrained, while hyperscaler capex is still being revised upward despite higher component pricing. New memory capacity should take years to meaningfully come online, supporting pricing, margins, and earnings through the current cycle.
The AI Supply Chain Just Confirmed Nvidia's Future
TSMC and ASML both raised guidance, confirming AI infrastructure remains supply constrained, while Rubin's N3 node is fully booked and CoWoS capacity expands nearly 50%. Nvidia's Kyber delay concerns appear limited to Rubin Ultra, leaving mainstream Rubin NVL72 deployments and near-term revenue expectations largely unchanged. Qualification of Samsung, SK hynix and Micron for HBM4 reduces supply-chain risk as the industry shifts toward higher-capacity 16-Hi HBM4 memory.
HudBay Minerals (HBM) Stock Sinks As Market Gains: What You Should Know
In the closing of the recent trading day, HudBay Minerals (HBM) stood at $21.98, denoting a -2.31% move from the preceding trading day.


