


Hudbay Minerals Inc. (HBM)



HudBay Minerals (HBM) Outperforms Broader Market: What You Need to Know
HudBay Minerals (HBM) concluded the recent trading session at $23.68, signifying a +1.63% move from its prior day's close.
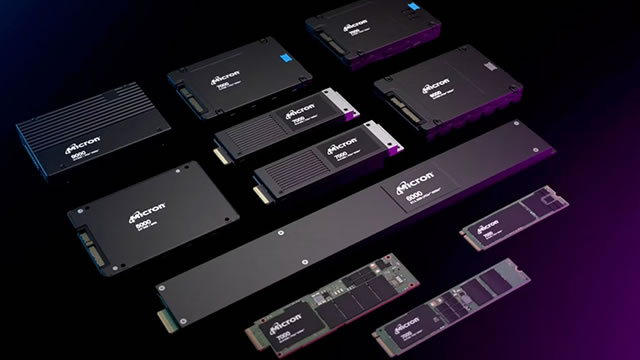
Micron's HBM Surge Could Redefine the AI Growth Story
Micron's NASDAQ: MU fiscal Q3 results and the strength of its outperformance highlight a persistent problem in today's market: there is a fundamental misunderstanding of the AI trade. AI isn't a niche; it's not a bubble.
Micron Could Beat Earnings Again, And It Still Might Not Be Enough
Micron Technology remains a strong buy, driven by robust AI-fueled demand for HBM, DRAM, and NAND memory. MU's valuation has reached an inflection point; further upside hinges on sustained growth and management's outlook for 2028. Investor focus is shifting from near-term beats to long-term revenue lock-in, HBM margin accretion, and supply chain health.
AI Boom and HBM Demand to Boost Micron's DRAM Revenues in Q3
MU's DRAM revenues may have surged in Q3 as AI demand, HBM leadership and NVIDIA ties fuel one of its strongest memory markets in years.
HudBay Minerals (HBM) Stock Declines While Market Improves: Some Information for Investors
In the latest trading session, HudBay Minerals (HBM) closed at $27.59, marking a -2.06% move from the previous day.
Micron stock in focus: can HBM demand unlock another 60% rally?
Micron stock (NASDAQ: MU) remains in focus ahead of the company's fiscal third-quarter results on June 24, with investors debating whether one of Wall Street's strongest AI-linked rallies still has room to run. The stock has surged as the memory-chip cycle has tightened, but a fresh bullish call has pushed the debate further.
SK Hynix says ships samples of 12-layer next-gen HBM4E chips to major customers
SK Hynix said on Thursday it has shipped samples of its 12-layer HBM4E memory chip to major customers, as the South Korean chipmaker seeks to strengthen its position in the fast-growing AI semiconductor market.
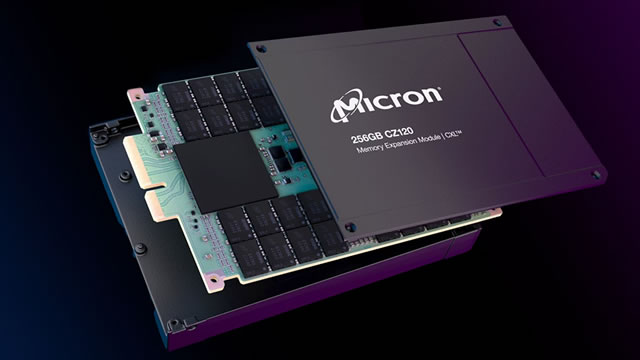
Micron: The Market Is Right (Rating Upgrade)
I'm upgrading Micron to a cautious buy on pullbacks. My call is mainly driven by structural AI demand and memory supply constraints. MU's valuation is now based on a multi-year AI supercycle, with HBM4 demand visibility and pricing power supporting the bull thesis. Key near-term catalysts include management's commentary on HBM TAM, revenue run-rate, and gross margin expansion at the upcoming June 24 print, in my opinion.
Micron: Rising Memory Demand And Tight Supply Create A Powerful Setup
Micron Technology (MU) is a frontrunner in the AI-driven memory supercycle, benefiting from surging demand for DRAM and HBM products. MU's strategic customer agreements, rapid HBM3E ramp, and expanding cloud memory business underpin record revenue and margin expansion. Despite cyclical risks and aggressive competition, structural supply constraints and AI tailwinds support elevated pricing and earnings durability.
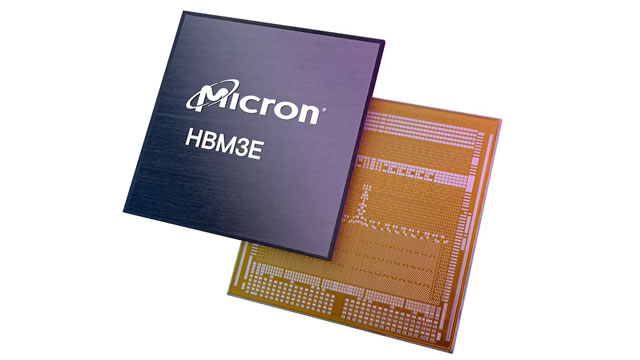
Micron: Stop Playing Musical Chairs And Take A Seat
Micron Technology, Inc. earns a Strong Buy rating, reflecting a structural shift from cyclical trading stock to a core AI infrastructure play. MU trades at a 17.6x forward P/E and 12.9x EV/EBITDA, both at notable discounts to sector medians despite record gross margin guidance and AI-driven demand. HBM4 and SOCAMM2 products drive multi-year visibility, with all 2026 HBM4 output sold out and SOCAMM2 offering incremental margin expansion.
Samsung jumps 10% as Jensen Huang lands in Seoul amid HBM4E deal buzz
Samsung stock jumped nearly 10% on Monday, adding another sharp leg to a rally that has turned the Korean chipmaker into one of the biggest listed plays on artificial intelligence infrastructure. The move came as investors looked ahead to Nvidia CEO Jensen Huang's expected visit to South Korea, where meetings with major Korean technology groups have stirred fresh hopes of deeper AI partnerships.
Samsung's shares surge as much as 6% company ships next-generation AI memory chip samples
Samsung shares rose after it shipped samples of its newest AI memory chip. The chipmaker said HBM4E was faster than its previous HBM4 products.


