


Hudbay Minerals Inc. (HBM)



Micron's Massive Gains: Why The Upside Isn't Over Yet
Micron Technology remains a compelling buy, with significant upside potential driven by AI tailwinds and a memory cycle upturn. Most traditional valuation metrics are flawed for MU due to its cyclical, commodity nature; forward EV/EBITDA and EV/EBIT provide more reliable benchmarks. Management expects its HBM4E chip to help it catch up to SK hynix and Samsung in HBM chip market share.
Micron: The Market Still Underestimates The AI Memory Cycle
Micron Technology is experiencing a structurally different upcycle, driven by surging AI-related memory demand, especially for HBM and advanced DRAM. MU has sold out its 2026 HBM capacity, is securing multi-year contracts, and is rapidly expanding fabrication to meet robust AI infrastructure needs. Despite a 700% stock gain, I see a 38% further upside, as the upcycle is in its early to mid stages and not yet at its peak.
Micron: AI Demand Is Turning Memory Into A Premium Asset
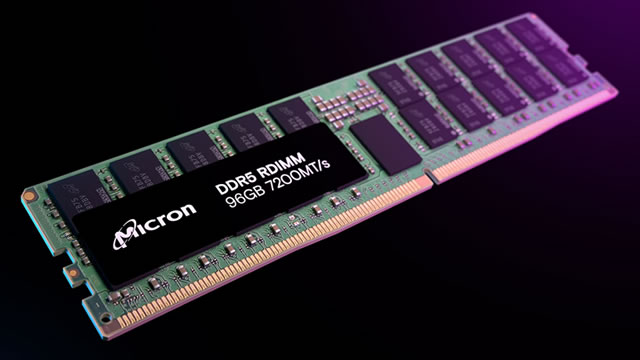
Micron is evolving from a cyclical memory supplier to a critical AI infrastructure enabler, warranting a premium valuation. Q2 guidance—$33.5B revenue, 81% gross margin, $19.15 EPS—signals durable, AI-driven demand and robust financial performance. MU's leadership in HBM and data center memory, with full 2026 HBM supply agreements and expanding NAND relevance, underpins its AI-centric growth.
Micron: AI Bottlenecks End The Commodity Cycle
Micron Technology (MU) is experiencing a structural shift, driven by AI-induced demand, with HBM and data center memory now critical to industry supply and pricing. MU's Q2 revenue surged 196% YoY, gross margin reached 74.9%, and HBM capacity is sold out through 2026, supporting a Buy rating. Memory is no longer behaving as a commodity; multi-year contracts, persistent supply constraints, and advanced packaging bottlenecks underpin durable pricing power.
Memory Revenues to Nearly Triple in 2026: Semiconductor ETFs to Buy
Semiconductor ETFs like SOXX offer broad exposure as AI-driven memory revenues are projected to nearly triple in 2026.
Micron Technology: I Think There Is A Clear Path To Over $1,500
Micron Technology is deeply undervalued at 11x forward P/E, despite 190% YoY revenue growth and a 57% net income margin. MU's rerating thesis is driven by structural AI demand, fully committed 2026 HBM capacity, and technological leadership in SOCAMM2 and HBM4. MU is a confirmed supplier for NVDA's Vera Rubin platform, with high-volume HBM4 and SOCAMM2 shipments and a rapid 1-gamma DRAM node ramp.
HudBay Minerals (HBM) Q1 Earnings: Taking a Look at Key Metrics Versus Estimates
While the top- and bottom-line numbers for HudBay Minerals (HBM) give a sense of how the business performed in the quarter ended March 2026, it could be worth looking at how some of its key metrics compare to Wall Street estimates and year-ago values.

HudBay Minerals (HBM) Surpasses Q1 Earnings and Revenue Estimates
HudBay Minerals (HBM) came out with quarterly earnings of $0.4 per share, beating the Zacks Consensus Estimate of $0.34 per share. This compares to earnings of $0.24 per share a year ago.

HudBay Minerals (HBM) Laps the Stock Market: Here's Why
HudBay Minerals (HBM) closed at $24.35 in the latest trading session, marking a +1.37% move from the prior day.

HudBay Minerals (HBM) Earnings Expected to Grow: Should You Buy?
HudBay Minerals (HBM) doesn't possess the right combination of the two key ingredients for a likely earnings beat in its upcoming report. Get prepared with the key expectations.

Micron Is Up 68% YTD as HBM Demand Explodes. Is the Memory Rally Sustainable?
Shares of Micron Technology (NASDAQ:MU | MU Price Prediction) are changing hands around $480 midday Thursday, off 2% on the session but still sitting near record territory.

Can Rising HBM Demand Accelerate Micron's Long-Term Revenue Growth?
MU rides surging HBM demand from AI workloads, with tight supply, rising memory content and strong pricing poised to fuel long-term revenue growth.


