


Hudbay Minerals Inc. (HBM)



HudBay Minerals (HBM) Stock Drops Despite Market Gains: Important Facts to Note
HudBay Minerals (HBM) closed at $24.88 in the latest trading session, marking a -1.35% move from the prior day.

Micron: The Peak Everyone Sees Isn't There
Micron Technology, Inc. remains a Buy as AI-driven memory demand, HBM strength, and margin expansion underpin a robust structural setup. Q2 FY25 saw revenue surge over 3x YOY to $23.86B and non-GAAP gross margin jump to 74.9%, reflecting accelerating AI adoption. Supply constraints, complex HBM production, and longer-term agreements support pricing power and visibility, while capex timing delays near-term supply risk.
How Micron Is Looking To Win The HBM Wars
Every advanced AI chip depends on a vital challenge: the memory necessary to provide it with data. High-bandwidth memory (HBM) has become so coveted that the entire sector, including SK Hynix, Samsung, and Micron (MU), is already sold out for 2026.
Micron Technology: Betting On The AI Memory Supercycle
Micron Technology delivered a record Q2 FY2026, with revenue up 196% YoY and EPS above consensus. MU's HBM supply is fully sold out through 2026, with long-term agreements and a unique U.S. manufacturing advantage amid geopolitical shifts. Despite a 7% post-earnings dip on $25B+ FY2026 Capex guidance, spending is backed by committed HBM orders and robust cash flow.
HudBay Minerals (HBM) Stock Slides as Market Rises: Facts to Know Before You Trade
The latest trading day saw HudBay Minerals (HBM) settling at $21.64, representing a -1.64% change from its previous close.

Can Micron Capitalize on Rising HBM Demand Amid AI Server Boom?
MU rides on surging HBM demand as AI server growth tightens supply, boosts pricing power and locks in 2026 capacity through long-term deals.

The Memory Inversion: Exploiting Micron's Algorithmic AI Valuation Fracture
I assign a Strong Buy rating to Micron Technology, Inc. with a $689 target, citing a major valuation dislocation and Wall Street's mispricing of its AI infrastructure transition. MU's shift to 5-year Strategic Customer Agreements and HBM4 base-die integration de-risks earnings, supporting a re-rating from cyclical to infrastructure-like multiples. Algorithmic compression is a bullish catalyst for memory demand, while architectural changes and margin permanence from HBM4/4E integration underpin long-term thesis strength.
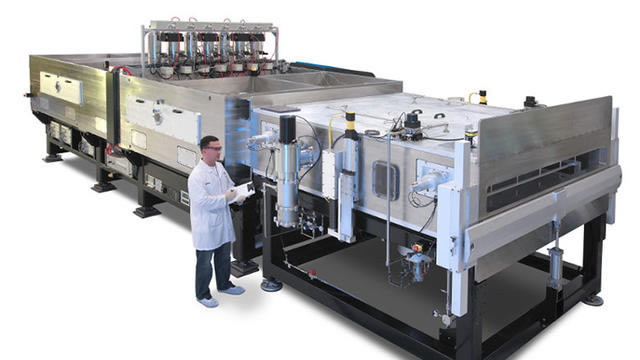
Can HBM and Packaging Demand Accelerate AMAT's Revenue Growth?
Applied Materials is poised to benefit as HBM and advanced packaging emerge as key growth drivers in AI-driven chip manufacturing.
The HBM Shortage May Make Micron A $1 Trillion Giant
Micron is positioned at the epicenter of a structural High Bandwidth Memory (HBM) shortage, with demand outstripping global supply through at least 2030. Q2 2026 results show MU revenue nearly tripled YoY to $23.86B, with gross margins exceeding 74%, driven by AI data center demand and supply constraints. Guidance for Q3 2026 implies $33.5B revenue and 81% gross margins, signaling a demand surge that may exceed annual global HBM production capacity.
HudBay Minerals (HBM) Falls More Steeply Than Broader Market: What Investors Need to Know
In the most recent trading session, HudBay Minerals (HBM) closed at $18.65, indicating a -6.19% shift from the previous trading day.
Micron: HBM Leads To Profit Explosion
Micron Technology, Inc. delivered record Q2 '26 results on Thursday, driven by unprecedented demand for high-bandwidth memory in the Data Center market. Micron's Q2 revenue surged 196% Y/Y to $23.9B, with non-GAAP gross margin reaching 75% and free cash flow up 705% Y/Y. Guidance for Q3 anticipates $33.5B in revenue and 81% gross margins, underpinned by ongoing HBM growth and robust DRAM demand.
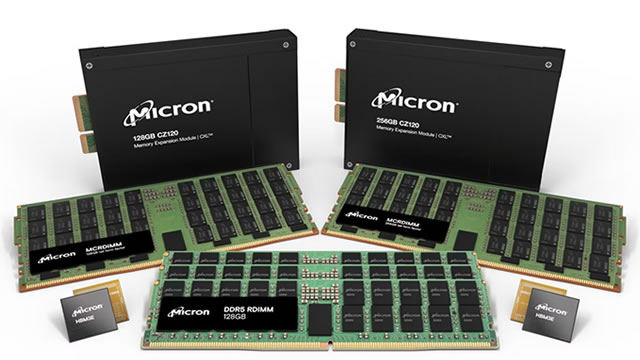
Micron Stock Gets Powerful Setup Ahead Of Earnings
Micron Technology has surged 188% in six months, driven by robust AI-fueled memory demand and HBM pricing power. MU's Q2 earnings are pivotal, with Wall Street expecting $8.59 EPS and $19.1B revenue; 23 upward estimate revisions signal optimism. HBM supply is fully contracted for 2026, supporting gross margins guided to 68% and a healthy liquidity position with $12B cash and $15.5B total liquidity.


