


Monarch Casino & Resort Inc. (MCRI)



Monarch Casino & Resort: What I'm Watching Ahead Of Q3
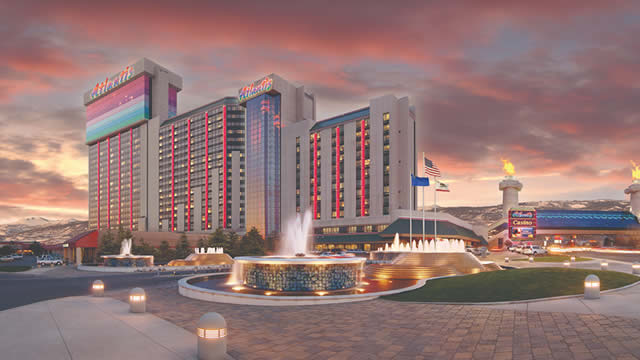
Monarch Casino & Resort earns a reiterated Buy rating, supported by strong EBITDA and FCF generation from Atlantis and Black Hawk properties. Texas Capital's recent Buy initiation and 20% upside target of $147/share align with my long-term valuation of $140–$150, independent of a potential third casino. Reno's tourism momentum and infrastructure upgrades drive bullishness for Atlantis, while Black Hawk maintains strong AGP growth and high visitation.
Monarch Casino (MCRI) Q2 Earnings and Revenues Top Estimates
Monarch Casino (MCRI) came out with quarterly earnings of $1.78 per share, beating the Zacks Consensus Estimate of $1.75 per share. This compares to earnings of $1.44 per share a year ago.
Monarch Casino: Earnings Are Coming, But Investors Want Something Bigger
Monarch Casino & Resorts, Inc. remains a high-quality 'Hold' with significant optionality, but current valuation tempers enthusiasm for new entries. MCRI's robust balance sheet and cash position enable flexibility for M&A, special dividends, or buybacks, though capital allocation timing is critical. Recent traffic and GGR trends in Reno and Black Hawk suggest a strong upcoming quarter, with potential for revenue and moderate EPS beats.
Monarch Casino (MCRI) Is Up 1.27% in One Week: What You Should Know
Does Monarch Casino (MCRI) have what it takes to be a top stock pick for momentum investors? Let's find out.
Are Consumer Discretionary Stocks Lagging Monarch Casino & Resort (MCRI) This Year?
Here is how Monarch Casino (MCRI) and Rush Street Interactive, Inc. (RSI) have performed compared to their sector so far this year.
3 Reasons Why Growth Investors Shouldn't Overlook Monarch Casino (MCRI)
Monarch Casino (MCRI) could produce exceptional returns because of its solid growth attributes.
Are You Looking for a Top Momentum Pick? Why Monarch Casino (MCRI) is a Great Choice
Does Monarch Casino (MCRI) have what it takes to be a top stock pick for momentum investors? Let's find out.
Monarch Casino (MCRI)'s Technical Outlook is Bright After Key Golden Cross
Monarch Casino & Resort, Inc. (MCRI) is looking like an interesting pick from a technical perspective, as the company reached a key level of support. Recently, MCRI's 50-day simple moving average crossed above its 200-day simple moving average, known as a "golden cross.
Monarch Casino (MCRI) Beats Q1 Earnings and Revenue Estimates
Monarch Casino (MCRI) came out with quarterly earnings of $1.52 per share, beating the Zacks Consensus Estimate of $1.15 per share. This compares to earnings of $1.05 per share a year ago.
Light & Wonder (LNWO) Surges 5.0%: Is This an Indication of Further Gains?
Light & Wonder (LNWO) was a big mover last session on higher-than-average trading volume. The latest trend in earnings estimate revisions might not help the stock continue moving higher in the near term.
All You Need to Know About Monarch Casino (MCRI) Rating Upgrade to Buy
Monarch Casino (MCRI) has been upgraded to a Zacks Rank #2 (Buy), reflecting growing optimism about the company's earnings prospects. This might drive the stock higher in the near term.
Monarch Casino: Capital Returns Today, Potential M&A Tomorrow
Monarch Casino (MCRI) remains a 'Buy' with a $100–$105 valuation range, reflecting strong fundamentals and optionality despite a recent EPS miss. MCRI's core casino business delivered 5.4% revenue growth and expanding EBIT margins, while hotel headwinds were minor and offset by robust FCF and buybacks. With $96.5 million cash, no long-term debt, and board-approved buybacks, MCRI offers over 10% total return potential including dividends.


