


Microsoft Corp. (MSFT)



Will Xbox Content Strength Continue to Lift MSFT's Gaming Revenues?
Xbox's rising content revenues, surging Game Pass growth and fresh hardware launches position Microsoft for sustained gaming momentum.
MSFT vs. AAPL: Which Mega-Cap Tech Stock is the Better Buy Now?
Microsoft outpaces Apple with 39% Azure growth, $13B AI business, and clear enterprise AI monetization, while Apple faces tariff headwinds and uncertain AI revenues.
Microsoft has ‘comfortable' AI lead, strong Q1 results expected: analysts
Wedbush analysts believe Microsoft Corp (NASDAQ:MSFT) has a “comfortable” lead in the AI revolution and expects the tech giant's upcoming fiscal first quarter 2026 earnings and outlook to be “robust”. In a note to clients on Wednesday, the analysts stated that Microsoft's stock, in their opinion, has yet to price in the next wave of Cloud and AI growth, given what they called the company's strong competitive Cloud edge over Amazon and Google.
Microsoft (MSFT) Reports Next Week: Wall Street Expects Earnings Growth
Microsoft (MSFT) doesn't possess the right combination of the two key ingredients for a likely earnings beat in its upcoming report. Get prepared with the key expectations.
Why Microsoft (MSFT) is a Top Stock for the Long-Term
Wondering how to pick strong, market-beating stocks for your investment portfolio? Look no further than the Zacks Focus List.
Microsoft: Insatiable Compute And Enterprise SaaS Demand - Wait For Dip Buying Opportunity
MSFT has delivered robust cloud/ enterprise SaaS monetization results during the ongoing AI boom, with demand only gated by compute capacity. These reasons are also why the hyperscaler has hinted at a drastically higher FQ1'26 capex spending along with an ongoing in-house AI chip investments ahead. While there may be near-term noise arising from MSFT's higher compute costs, as observed in the lower cloud gross margins, the management has well balanced these with richer Enterprise margins.
Microsoft: A Cautious Buy Ahead Of Q1 Earnings
Microsoft's stock fell 8% since the last article, creating a better margin of safety and upside potential if growth surprises continue. Valuation at 32x earnings looks high, but strong revenue growth, quality business segments, and historical multiples justify it. MSFT's key risks include AI demand fading, cloud competition, Xbox uncertainty, and potential overvaluation affecting upside.
Microsoft: Very Bullish Into Upcoming Earnings
Microsoft remains a top enterprise technology leader, strategically positioning itself as an AI winner through diversified investments and partnerships. MSFT's approach leverages a diverse set of AI relationships, reducing infrastructure risk and accelerating AI capabilities without heavy upfront costs. Valuation is reasonable at 33x forward EPS, with potential for multiple expansion, as AI investments mature, and drive future revenue and earnings growth.
Microsoft Expands Security Offering: Is it the Next Revenue Pillar?
Microsoft's MSFT security business is solidifying its position as a major revenue contributor, with the company now serving nearly 1.5 million security customers following the robust performance in fiscal 2025. The tech giant closed fiscal 2025 with Microsoft Cloud revenues surpassing $168 billion annually, up 23%, while prioritizing security above all else in its engineering investments.
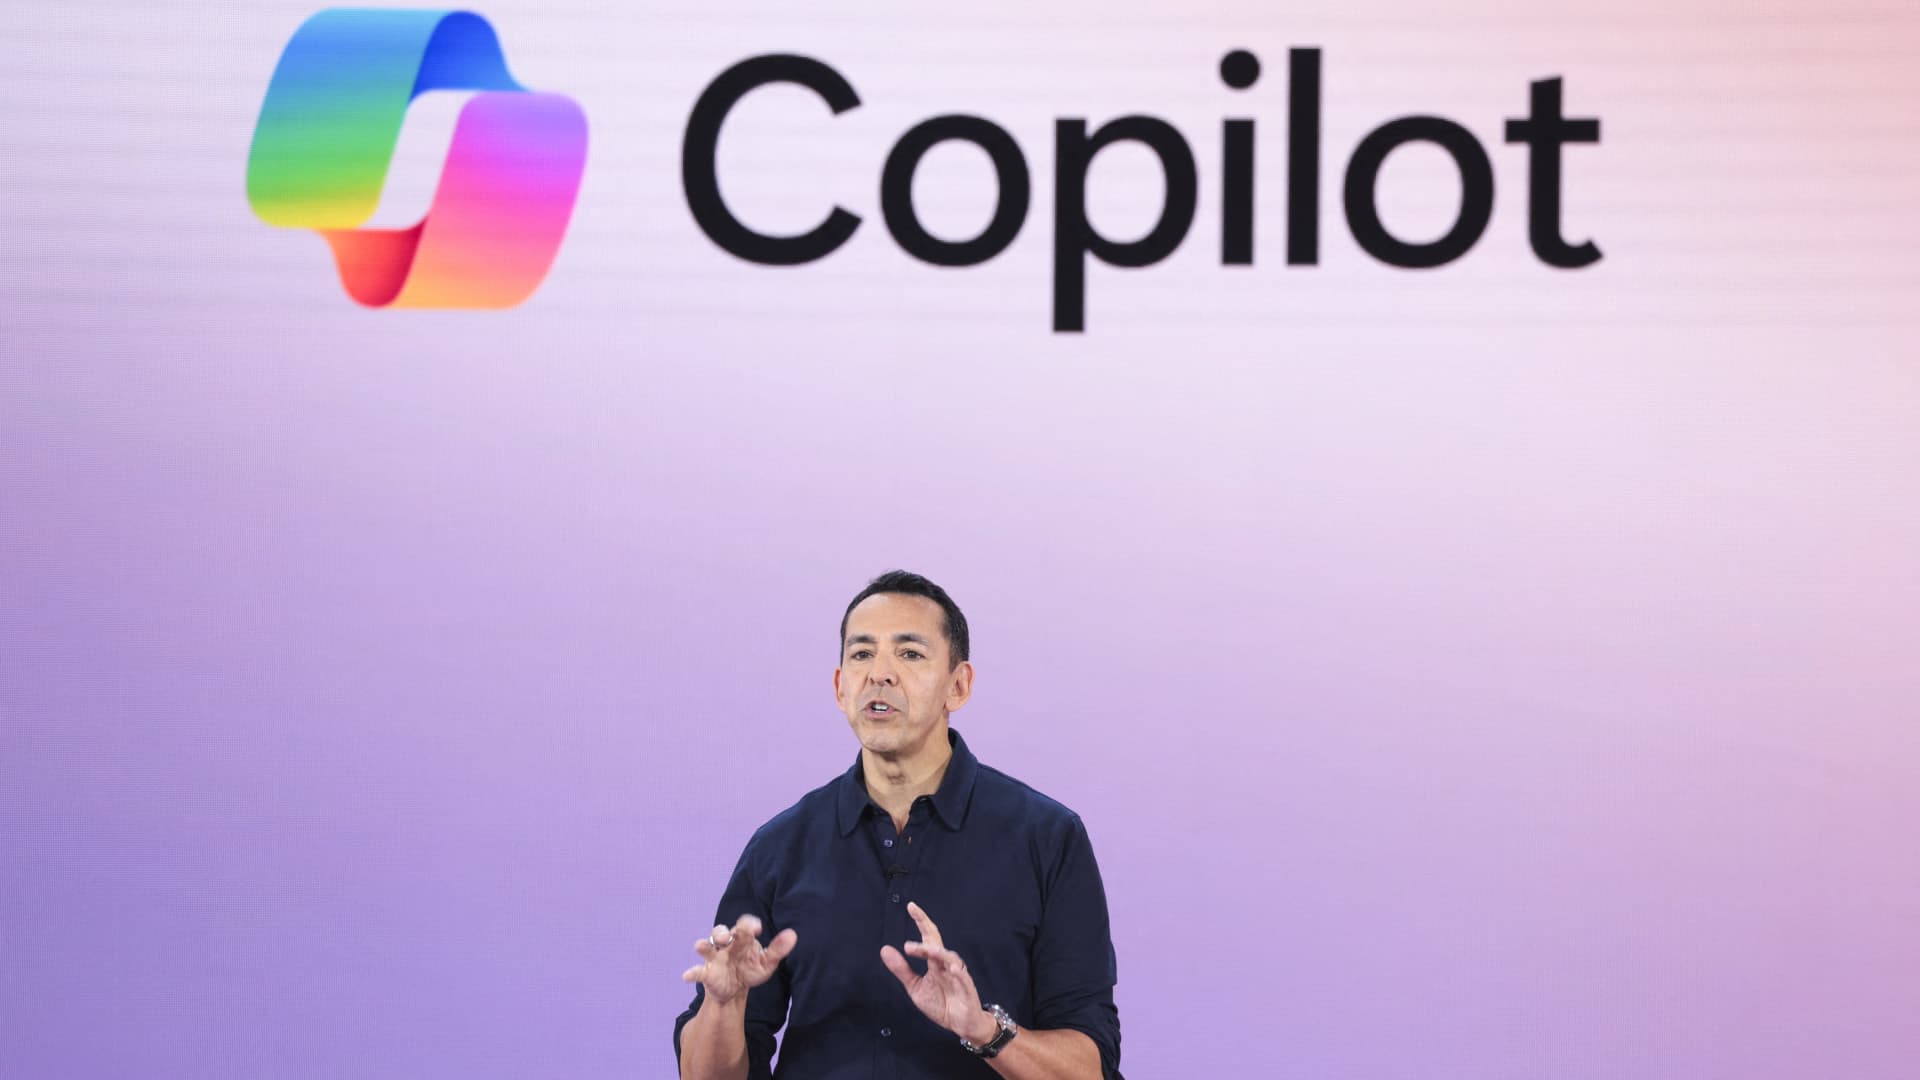
Microsoft will test a Copilot AI feature that performs work on local files in Windows 11
Microsoft will bring its Copilot Actions feature that can perform certain tasks to its Windows 11 operating system, enabling work with locally stored files. It's coming first to people in the Windows Insider Program and the Copilot Labs group for trying artificial intelligence experiments.
Microsoft: The Hyperscaler Monetizing AI With Copilots
I rate Microsoft Corporation (MSFT) a Buy, driven by its unique position in both AI infrastructure and AI-powered applications. MSFT's dual AI strategy—hyperscale cloud (Azure) and embedded AI copilots—creates multiple revenue streams and deepens customer integration. Despite a premium valuation, MSFT's higher margins, robust cloud growth, and proven AI monetization justify its pricing compared to peers like AMZN and GOOG.
Nebius: Why Microsoft's Deal Makes It Far More Valuable Than Most Realize
Nebius Group secures a transformative multi-year, nearly $20 billion GPU cluster supply deal with Microsoft, validating its AI infrastructure capabilities. The Microsoft contract provides NBIS with long-term revenue visibility and positions it as a reliable supplier for hyperscalers, enhancing its credibility and financing options. Despite a high price-to-sales ratio, NBIS remains undervalued due to the magnitude of its future revenue streams and foundational role in AI infrastructure.


