


Micron Technology, Inc. (MU)





Micron Q4 Earnings: AI Cycle Vs. Peak Margin Fears
Micron Technology, Inc. faces a pivotal FQ4 2026 earnings report amid record margin expansion and AI-driven demand. Consensus expects MU's net margin to reach a record of 70.7% in FQ4. I share the optimism for MU in the near term but remain skeptical about the sustainability in the longer term.
Micron: Records Are Not Enough Anymore
Micron remains rated Hold as the earnings cycle decelerates and capital returns lag Korean peers. DRAM and NAND price growth is slowing, with inventory and end-demand pressures signaling a shift from repricing to price holding. SK Hynix and Samsung are aggressively returning capital, while MU's capital return potential hinges on post-CHIPS Act restrictions expiring in December 2026.
Micron And The Memory Bottleneck
Micron Technology, Inc. is a core beneficiary of the AI infrastructure boom, uniquely positioned as the only major American DRAM and HBM supplier. MU's transition from commodity DRAM to engineered, capacity-constrained High Bandwidth Memory has shifted its business model and underpinned recent outperformance. Despite a 548.75% twelve-month return and an A+ performance grade, MU exhibits high volatility, a D- safety grade, and is consolidating after a major run.
Micron Q4: Brace Yourself For The Inflection
Micron Technology, Inc. is rated Buy, supported by robust fundamentals, multi-year strategic contracts, and a massive net cash position. MU's fiscal 2026 features explosive revenue and margin growth, driven by AI-related memory demand and pricing power, but price momentum is moderating. Long-term contracts now cover 20% of DRAM and ⅓ of NAND volume through 2030, with $22B in financial commitments and $24.43B net cash.
Why are Micron, SK Hynix, and SanDisk stocks jumping on Thursday?
Shares of major memory-chip companies jumped on Thursday as easing oil prices and Treasury yields improved broader sentiment toward technology stocks, helping the sector recover some of the losses suffered earlier in the week. Micron Technology MU rose about 5.5%, while SK Hynix gained more than 4% and SanDisk climbed roughly 5%.
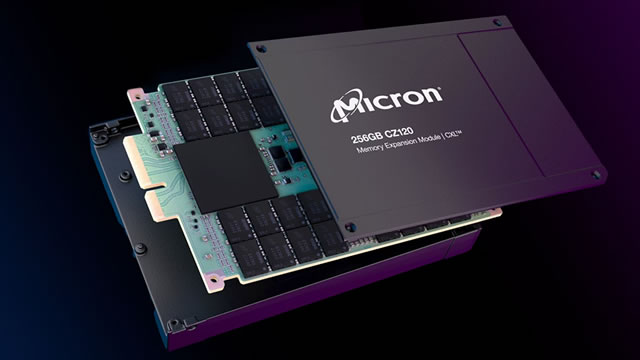
Micron's New 512GB Memory Module Deepens Its AI Infrastructure Advantage
Micron Technology TodayMUMicron Technology$975.35 +48.80 (+5.27%) As of 10:10 AM Eastern This is a fair market value price provided by Massive. Learn more.52-Week Range$154.65▼$1,255.00Dividend Yield0.06%P/E Ratio22.13Price Target$1,295.63Add to WatchlistEnterprise artificial intelligence (AI) development has focused in recent years on graphics processing units.
AI predicts Micron stock price for September 30, 2026
Micron (NASDAQ: MU) has suffered significant losses in the past month, losing roughly 8.5% of its value in a broader chip-market selloff. Looking toward the company's next earnings date, September 30, 2026, our machine learning algorithm believes the price is likely to fall further.
Micron stock: could a valuation rerating drive MU shares to $1,600?
Micron Technology stock (NASDAQ: MU) has surged 226% this year, powered largely by spectacular earnings growth as booming artificial intelligence demand has driven memory-chip prices higher. But the next phase of the rally could depend less on further earnings expansion and more on whether investors become willing to pay a higher valuation multiple for each dollar of Micron's profits.
Micron Technology Has Just Shared Great News
Micron Technology, Inc. is becoming undervalued despite a 1300% return since my article from April 2025. MU has just announced the world's first 512GB DDR5 module, which secures a first-mover advantage in high-performance, energy-efficient data center memory. Persistent memory shortages, forecast to last through 2030, provide multi-year revenue visibility and underpin MU's growth outlook.
A Broad-Based Earnings Growth Picture as Revisions Stay Positive
14 of the 16 Zacks sectors are currently expected to produce positive earnings growth in Q3, with six expected to see double-digit gains. This reflects the most broad-based earnings growth performance in recent times.
Micron Offers A Massive Margin Of Safety (Earnings Preview)
Micron Technology, Inc. remains a Strong Buy with Strategic Customer Agreements driving revenue durability and reducing cyclicality. MU's Q4 earnings are expected to beat both top- and bottom-line consensus, supported by a history of outperformance. Despite supply constraints and other risks, Micron's forward P/E of 5.95 and PEG of 0.07 highlight a generous margin of safety and deep undervaluation.
Micron's stock could climb 70% higher thanks to a factor that's been largely absent so far
Shares of Micron trade at a stubbornly low valuation but a TD Cowen analyst thinks that could change.


