


Micron Technology, Inc. (MU)






Forget Micron Technology: 1 Record-Breaking Cloud Powerhouse to Buy Hand Over Fist After the Pullback
Micron Technology (NASDAQ:MU | MU Price Prediction) is the chip stock dominating every feed after its memory business rode the AI cycle to a $1.12 trillion market cap and a 760.37% one-year run.

Micron stock jumps as AI memory boom fuels analyst price target hikes
Micron Technology MU shares moved higher on Thursday as investors returned to semiconductor stocks and analysts grew increasingly optimistic about the outlook for memory-chip demand driven by artificial intelligence. The stock gained more than 10% during the session, rebounding after a sharp pullback that had seen shares fall roughly 12% over the previous five trading days.

Micron Is Already Up 223% This Year. Wolfe Research Sees More Upside.
Shares of Micron Technology (NASDAQ:MU | MU Price Prediction) are up 5% in midday trading on Thursday, June 11, changing hands near $939.
Marvell vs. Micron: One Stands to Gain More From AI Demand
Marvell Technology (NASDAQ:MRVL | MRVL Price Prediction) and Micron Technology (NASDAQ:MU) both just delivered AI-fueled earnings reports, yet they sit on opposite sides of the data center stack.

Micron's stock rebounds after ‘healthy' reset, and analysts see blue skies ahead
Memory stocks are back on the upswing, and Morgan Stanley analysts say their recent breather was necessary to support more explosive gains.
Analyst raises Micron stock price target by 127%
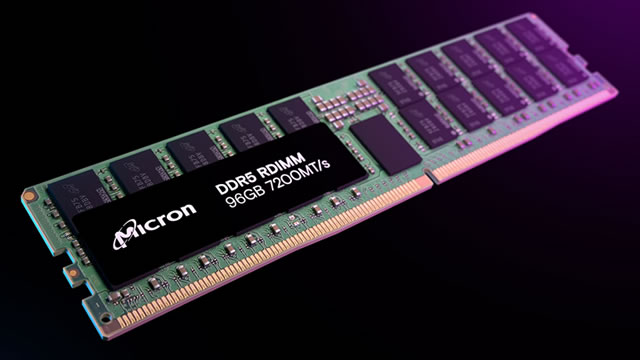
On June 11, Wolfe Research became the latest Wall Street entity to catch up with Micron (NASDAQ: MU) stock's staggering rally by issuing a massive 12-month price target upgrade.

Micron Can Shake Its Slump & Benefit This ETF
Once-hot Micron (MU) is proving vulnerable to a recent uptick in volatility weighing on the artificial intelligence (AI) trade. As of late Wednesday, shares of the memory chipmaker were off 16.55% over the past week and following a recent flirtation with $1,100, the stock is clinging to $900.

Micron Stock Roars Back as It Shrugs Off Threat From Rival Memory-Chip Maker
Shares rally as investors buy the dip in tech stocks despite the U.S. and Iran exchanging fire for a second straight day.
Micron stock plunges 12% in a week: why investors are booking profits
Micron stock (NASDAQ: MU) has dropped sharply after one of the most powerful rallies in the AI trade. The memory-chip maker has fallen about 12% over the past five trading sessions, with some market reports putting the slide closer to 13%.

3 Reasons Why Growth Investors Shouldn't Overlook Micron (MU)
Micron (MU) is well positioned to outperform the market, as it exhibits above-average growth in financials.

Micron's Parabolic Run May Have More Room To Go
Micron's equity story shines as AI-driven demand transforms memory from a commodity to a strategic infrastructure asset. MU's exposure spans HBM, server DRAM, and SSDs, positioning it across bandwidth, capacity, and storage bottlenecks in AI infrastructure. Long-term agreements with hyperscalers could structurally reduce earnings volatility and justify higher valuation multiples for MU.

Micron: Hot, And With Good Reason (Rating Upgrade)
Micron which has outperformed its semiconductor peers by 3.5x this year, is set to deliver Q3 results on the 24th of June. Gross margins which are already at record highs, are expected to exceed 80% in Q3, driven by robust DRAM/HBM demand and multi-year strategic customer agreements which bring added visibility. Valuation remains compelling at 16x forward earnings and a PEG below 0.2x, with a renewed dividend growing facet enhancing the investment case.


