


Micron Technology, Inc. (MU)





Micron at $420: Buy, Sell or Hold?
Micron Technology (NASDAQ:MU | MU Price Prediction) presents a compelling bull case at $420.52.
The Reason Why I'm Not Buying Micron Stock at Over $420
It didn't take all too long for shares of memory chip titan Micron (NASDAQ:MU | MU Price Prediction) to bounce back from a brief plunge into bear market territory.
Wall Street sets Micron stock price for the next 12 months
Following a dynamic month that first saw a 30% plunge and then a 30% rally for Micron (NASDAQ: MU), Mizuho Securities elected to raise its already bullish outlook for the memory company.
3 AI Semiconductor Stocks That Are Now Trading Below 20X Earnings
AI semiconductor stocks have been holding up, and some have been soaring.
Micron Stock Is on a Tear. How It Could Soar Another 40%.
Micron is one of the chip stocks with the best risk/reward ratio heading into earnings season, according to KeyBanc.
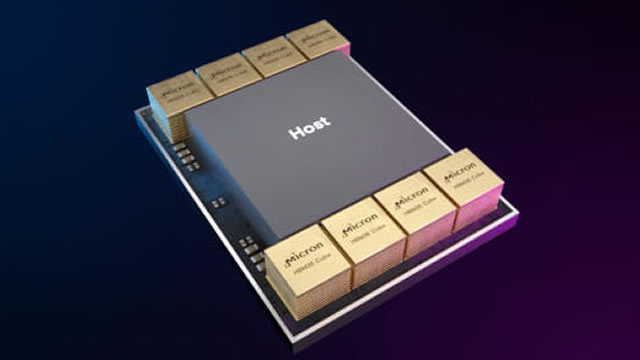
Micron Technology: I'm Buying And Not Looking Back
Micron Technology is rated a Strong Buy, driven by explosive top- and bottom-line growth and a compelling forward valuation. MU's HBM product line, power efficiency, and supply chain control position it to benefit from sustained AI and GPU demand. Even under bearish scenarios with supply increases and price declines, MU's earnings and margins remain resilient and undervalued.
Think It's Too Late to Buy Micron? Here's the Case for Getting In Now
Micron Technology (NASDAQ:MU | MU Price Prediction) has risen 522.09% over the past twelve months, climbing from $65.38 to $406.73.
Micron: Crushing Cyclical Fears (Rating Upgrade)
Micron Technology (MU) is upgraded to 'Buy' due to strong operational momentum, execution, and undervaluation versus forward earnings consensus. MU reported a 196% YoY revenue increase and record gross margins, yet negative earnings revisions and sell-off have created a disconnect and upside potential. CAPEX expansion is viewed as a strategic response to structurally rising demand, with HBM and enterprise SSD execution de-risking future revenue streams.
Micron to pay dividends on April 15; Here's how much 100 shares will earn
Computer memory giant Micron (NASDAQ: MU) is set to pay its second dividend of 2026 next week, on April 15, following a notable yield increase and a major stock market rally.
Micron Rallies 123% in Six Months: Should You Still Buy the Stock?
MU surges 123% in six months, fueled by AI-driven memory demand and strong earnings growth, yet still trades at a deep valuation discount.
Micron: The Memory Bottleneck Is Shifting - And Market Hasn't Caught Up
Micron is positioned for structural AI-driven memory demand, supported by multi-year strategic customer agreements that enhance long-term growth visibility. Micron's shift to high-volume inference, rapid 1-gamma node ramp, and increasing mix of higher-margin non-HBM and LP DRAM also underscores structural earnings accretion, reducing reliance on near-term pricing tailwinds. Bit demand for both DRAM and NAND is expected to outpace supply through at least 2028, with data center demand exceeding 50% of memory TAM this year supporting pricing resilience.
Micron and other memory stocks soar as Iran cease-fire refocuses attention on the AI boom
The memory trade had been coming undone in recent weeks, but it now looks to be back on in a big way following the announcement of a two-week cease-fire agreement with Iran.


