


Micron Technology, Inc. (MU)





Meet the Monster Stock That Continues to Crush the Market
Demand for artificial intelligence (AI) has fueled a renaissance for the historically cyclical semiconductor industry. Accelerating investment in AI infrastructure signals a move beyond GPUs and data centers.
The Artificial Intelligence (AI) Stock That Refuses to Slow Down, and It's Not Nvidia
Micron is one of only three companies producing the high-bandwidth memory (HBM) needed to advance AI. Revenue growth continues to accelerate.
The $700 Billion AI Spending Boom: 3 Tech Stocks Positioned to Win in 2026
Nvidia should continue to see strong growth as AI infrastructure spending soars. As a leader in HBM, Micron is also poised to see strong growth stemming from the AI data center build-out.
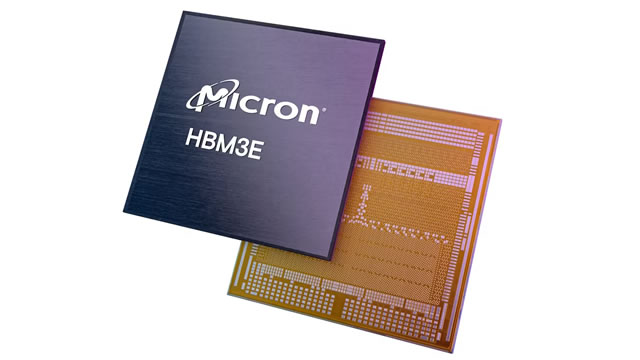
Is Micron Stock a Buy Now?
Micron Technology makes memory chips, which are much in demand. In fact, memory chip capacity is completely used up now thanks to AI.
Micron Is the Best-Performing Artificial Intelligence (AI) Stock of the Past Year -- Up 318%. Can It Keep Going in 2026?
The remarkable surge in memory prices is poised to continue in 2026, paving the way for strong results for Micron. The company's strong earnings growth potential suggests that it can still become a multibagger from current levels.
Micron Technology (NASDAQ:MU) Trading 5.1% Higher on Analyst Upgrade
Shares of Micron Technology, Inc. (NASDAQ: MU - Get Free Report) traded up 5.1% on Friday after Wedbush raised their price target on the stock from $320.00 to $500.00. Wedbush currently has an outperform rating on the stock. Micron Technology traded as high as $429.35 and last traded at $426.13. 39,024,558 shares traded hands during mid-day
Why Micron Stock Is Gaining Today
Micron stock is moving higher today despite bearish pressures shaping the broader market. The company's share price is posting gains in conjunction with bullish coverage from a leading investment firm.
Micron's stock is rising. Here's the big question heading into earnings.
Memory prices have been on a tear. Just how much will that flow through to Micron's profits?
Micron Technology price target boosted on stronger-than-expected memory pricing
Micron Technology Inc (NASDAQ:MU) saw its price target raised to $500 by Wedbush analysts, who cited memory industry pricing trends as the main driver behind the upgrade. The analysts also reiterated their ‘Outperform' rating on the stock, which traded hands at about $422 on Friday afternoon.
Micron Stock Climbs After Wedbush Lifts Price Target to $500
Micron Technology (MU) shares rose 3% on Friday after Wedbush lifted its price target on the chipmaker to $500 from $320 while keeping an Outperform rating.The
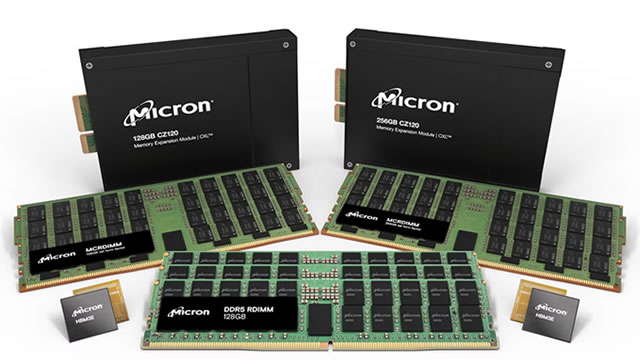
Micron Q2 Earnings Preview: Expect Another Monster Quarter
Micron Technology, Inc. is set to report Q2 earnings with anticipated revenue growth of 138% and EPS growth exceeding 450%, driven by AI-related memory demand. MU has consistently outperformed analyst estimates, benefiting from soaring DRAM prices and operating leverage, with the potential for another beat in the upcoming report. Forward guidance for Q3 will be pivotal; while memory pricing tailwinds persist, industry cyclicality and potential overinvestment could temper future growth.
Memory Inflation Is Real—and Apple Is the Only One Turning It Into an Opportunity
If you're in the market for a new laptop, smartphone, tablet, or even a gaming console, things could get a whole lot pricier as inflation on memory and storage products heats up, thanks to unprecedented demand from AI data centers. Micron (NASDAQ: MU) moved on from the consumer RAM market at the end of last year,... Memory Inflation Is Real-and Apple Is the Only One Turning It Into an Opportunity.


