


Rexford Industrial Realty, Inc. (REXR)



Warren Buffett Can't Buy These 2 Stocks, but You Can
These stocks have some qualities Buffett likes to see but are too small to be Berkshire investments.
1 Magnificent Dividend Stock Down 40% to Buy and Hold Forever
Rexford Industrial is a well-respected industrial real estate investment trust. The REIT has increased its dividend annually for over a decade.
Rexford Industrial: The 6.6% Yielding Preferred Shares Are Worth A Look
Rexford Industrial's preferred dividends and equity are well-covered, with a strong preferred dividend coverage ratio and a solid balance sheet. The REIT's two series of preferred shares offer attractive yields, with potential for capital gains if called or if/when the market interest rates continue to decrease. The risk/reward ratio for Rexford Industrial's preferred shares is excellent due to low leverage and potential for capital gains.
Rexford Industrial Remains One Of My Best Ideas In Real Estate
Industrial sector exposure in portfolios includes wide-moat companies, leading to no worries about portfolio structure. Rexford Industrial Realty benefits from industrial companies needing buildings to operate, showing resilience in a challenging environment. REXR's focus on SoCal infill market, strong financials, and growth opportunities position it as a top pick in the REIT space.
Income Strategy: 2 Fantastic Dividends For Total Returns
'Bend It Like Beckham' movie title references unconventional methods to achieve goals, similar to how Warren Buffett accumulated vast wealth. This includes utilization of the float in the insurance business and picking up high quality, undervalued names instead of simply buying the market index. Verizon and Rexford Industrial appear to fit the mold, as both are undervalued dividend stocks with strong business models for potential market-beating returns.
Compared to Estimates, Rexford Industrial (REXR) Q2 Earnings: A Look at Key Metrics
While the top- and bottom-line numbers for Rexford Industrial (REXR) give a sense of how the business performed in the quarter ended June 2024, it could be worth looking at how some of its key metrics compare to Wall Street estimates and year-ago values.
Rexford Industrial (REXR) Surpasses Q2 FFO and Revenue Estimates
Rexford Industrial (REXR) came out with quarterly funds from operations (FFO) of $0.60 per share, beating the Zacks Consensus Estimate of $0.58 per share. This compares to FFO of $0.54 per share a year ago.
3 REITs to Buy Now
Real estate investment trusts (REITs) can be a great way for investors to earn a steady income. It's important to diversify your portfolio.
Rexford Industrial: This REIT Is A Compelling Buy. Here's Why
Rexford Industrial faced headwinds, causing a decline in share price, creating a buying opportunity for long-term investors. Despite challenges, REXR saw double-digit growth in core FFO and revenue, outperforming some peers in same-store NOI growth. Strong balance sheet, growth projections, and raised guidance make REXR a no-brainer buy for investors seeking stable income and potential upside.
Rexford Industrial: West Coast Remains Compelling Despite (And Because) Of The Drop
Rexford Industrial is a high-quality industrial REIT with a BBB+ rating, 3.7% yield, and significant upside potential. Despite negative macro sentiment in California, REXR has impressive growth, low leverage, and a conservative investment thesis. Analysts underestimate REXR's stickiness and strength in the SoCal market, with a conservative price target of $75/share and a "BUY" recommendation.
Rexford Industrial: Still Focusing On Growth, Rather Than Shareholder Growth
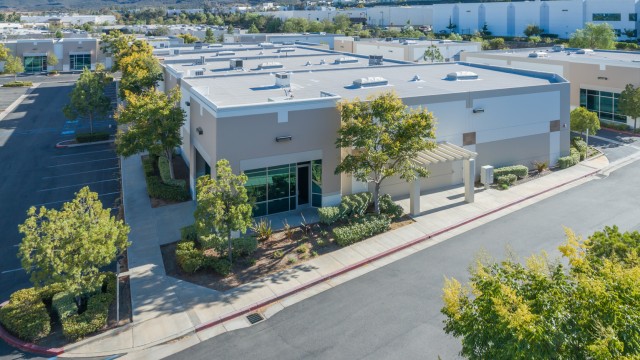
Rexford Industrial Realty, Inc. focuses on growth over growth per share, resulting in a continued overhang on the stock price. The company owns over 40 million square feet of industrial real estate in Southern California, with potential risks and benefits. Recent Rexford financial updates show continued growth in assets and rental income, but caution is advised due to the focus on growth and lower yields on acquisitions.
Rexford (REXR) Leases 1.3M Square Feet, Acquires $143M QTD
Rexford's (REXR) leasing activities and strategic acquisitions poise it well to ride the growth curve.


