


Star Group L.P. (SGU)
 NYSE NYSE Primary
Hulu To Become International Tile On Disney+, Replacing Star
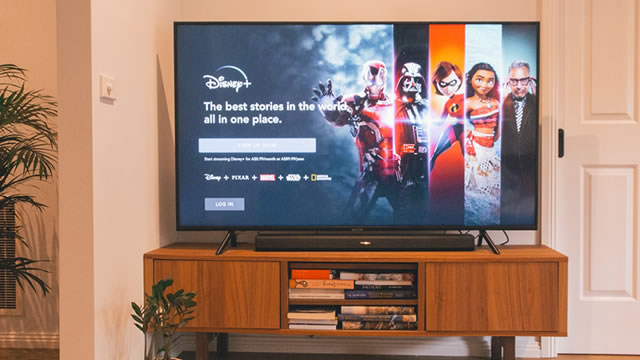
Hulu will replace Star as a tile on the international Disney+ service. This marks the first major international expansion for Hulu and closely follows Disney buying Comcast out of the U.S. streamer last month.
Brightstar Lottery: A $3 Dividend, A $500M Buyback, And One Very Bright Star
Brightstar Lottery has reduced debt, secured a major Italian license, and issued a $3 special dividend, unlocking significant shareholder value. Despite mixed Q2 results due to fewer U.S. jackpots, global instant product sales and strong free cash flow highlight resilient core operations. The company's $500 million buyback program and high dividend yield drive an impressive projected shareholder yield of 11.7%-13.3% for FY25.

High Profit And Low Debt Could Transform Headwater Exploration Into The Next Oil Star
Headwater expects to increase its production to 26,000 boe/d in 2027, representing a 30.48% increase compared to 2024. For this year, the company expects to pay a dividend yield of 6.35% to its shareholders. In Q1 2025, Headwater reported a liabilities-to-assets ratio of 25.22%, indicating its low debt levels.
Northern Star Resources: The 'Agnico' Of The ASX On The Sale Rack
Northern Star's FY2025 production missed guidance because of temporary delays accessing GPN ore and lower productivity, but long-term growth remains intact with KCGM and Hemi. In fact, Northern Star plans to take KCGM to 0.90 Moz/year by FY2029, making it a top-10 gold mine by scale, with Hemi also expected to add 0.55+ Moz/year. Assuming the stock was still trading above A$23.00/share, there wouldn't be much of an opportunity here, but at barely 1.0x P/NAV (6%) and ~$5,500/oz on EV/reserves, the stock is cheap.
Star Bulk: The Dry Bulk Stock To Own, Buybacks Should Help To Close The NAV Discount
Star Bulk Carriers Corp. management is committed to closing the NAV discount through share buybacks funded by vessel sales, creating a compelling arbitrage opportunity. A solid dividend policy and low operating costs support shareholder returns, with potential for the stock to regain its premium valuation. Dry Bulk market fundamentals remain favorable, with limited order books and strong demand, providing a tailwind for rates and asset values.
Undercovered Dozen: Nike, Star Bulk Carriers, Qualcomm And More
The Undercovered Dozen series highlights 12 lesser-covered stocks weekly, providing investment ideas and sparking community discussion on their potential. Featured stocks include Nike, Star Bulk Carriers and Qualcomm. Take a look and share your thoughts: Are any of these ideas worth a deeper review?
Blue Star Capital ups stake in SatoshiPay, shares rise
Blue Star Capital PLC (AIM:BLU) share rose in Thursday's early deals, as it confirmed it had raised its holding in SatoshiPay to 50%. Acquiring an additional 4,500 shares, representing 22% of SatoshiPay, the listed company further consolidated its stake.
Crude Oil Price Forecast: Rally Stalls Near Trendline, Shooting Star Emerges
Crude oil's advance has nearly mirrored April's drop, while trendline resistance and a bearish candle raise the risk of a near-term pullback.
AST SpaceMobile's Star Is Rising: Get in While It's Still Cheap!
You could examine AST SpaceMobile's NASDAQ: ASTS stock price and make a compelling case that it is highly overvalued, but you'd have to overlook its industry, growth trajectory, and earnings outlook. While the $38.50 price tag traded in mid-June seems high for a company with only $0.7 million in revenue, it reached an inflection point in FQ1 that has it on track to sustain hyper growth for several years, achieve profitability with two, and to grow earnings at a comparable hyper pace for the subsequent few years.
Liberty Star Minerals opens door to US grants and contracts after securing federal SAM registration
Liberty Star Uranium & Metals Corp. (OTCQB:LBSR) (dba Liberty Star Minerals) said it has completed its registration with the System for Award Management (SAM), the federal government's centralized platform for eligibility in contracts and grants. The move enables Liberty Star to compete for federal funding across multiple government agencies, the company told shareholders in a statement.
Primoris Services: A Rising Star In The Infrastructure Arena
Primoris Services has delivered strong long-term returns, with a 14.6% CAGR and nearly 300% total return over the past decade. Revenue per share has grown impressively, gross margins remain stable, and return on invested capital is showing positive momentum. The company recently increased its dividend after a long pause, with a low payout ratio suggesting future growth potential.
Bally's Corporation: Still Trading At An Unjustifiable Premium After Possible Star Takeover
Bally's remains overleveraged with a debt/EBITDA ratio of 11.3x, despite recent financing and the Star Entertainment deal reducing upfront capital needs. Q1 results showed mixed performance: declining casino and international revenues, modest North America iGaming growth, and continued negative operating cash flow. The Star Entertainment acquisition could provide international expansion, but consolidated EV/EBITDA remains high at 17.9x—well above industry peers and the sector median.


