


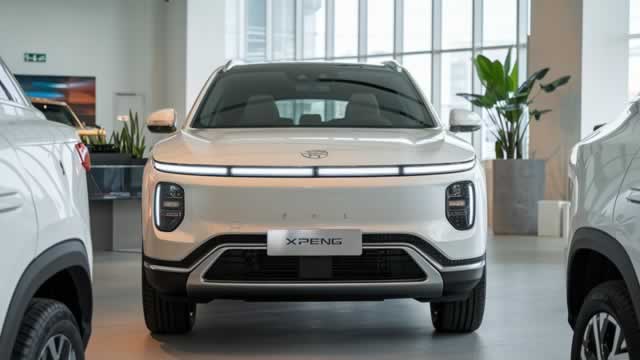
XPENG Q2 Earnings Call Highlights
XPENG NYSE: XPEV said its robotics business raised more than $900 million in an initial financing round at a post-money valuation exceeding $6.2 billion, as the electric-vehicle maker outlined plans to begin scaled production of its Iron humanoid robot by the end of 2026.
XPeng Sinks 7% as Q2 Miss Overshadows $6.3B Robotics Valuation, NIO Drops 4%, Tesla Slips
Chinese electric-vehicle ADRs are driving Monday morning's selling. XPeng (NYSE:XPEV | XPEV Price Prediction) stock is down 7% to $11.40 after a Q2 2026 revenue miss and soft Q3 2026 outlook overshadowed a record valuation for the company's humanoid robotics arm.
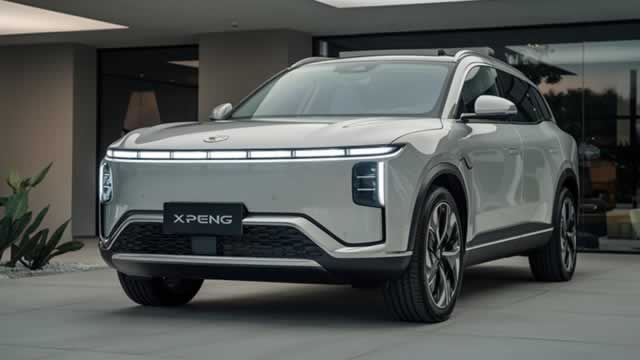
XPeng Net Loss Widens Amid Physical AI Push
The Chinese EV maker remained in the red despite resilient margins, as heavy investment in new models and AI-related tech outweighed profits from its main business and higher-margin services.
Wall Street Analysts Think XPeng (XPEV) Is a Good Investment: Is It?
When deciding whether to buy, sell, or hold a stock, investors often rely on analyst recommendations. Media reports about rating changes by these brokerage-firm-employed (or sell-side) analysts often influence a stock's price, but are they really important?

China's XPeng Charts Course From EVs to Robots
Chinese carmakers spent the past decade replacing gasoline engines with batteries. The next will be about integrating cars with robotics, XPeng's chief executive says.
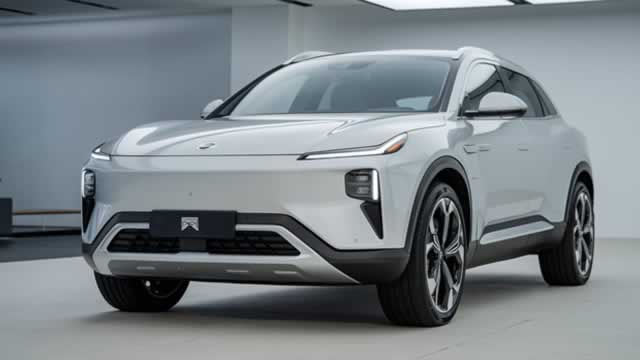
Chinese Automaker XPeng Unveils L03 SUV in Munich, Steps Up Overseas Expansion
Unveiling marks the company's first global vehicle launch outside China as it steps up expansion in Europe and other overseas markets amid intensifying competition at home.
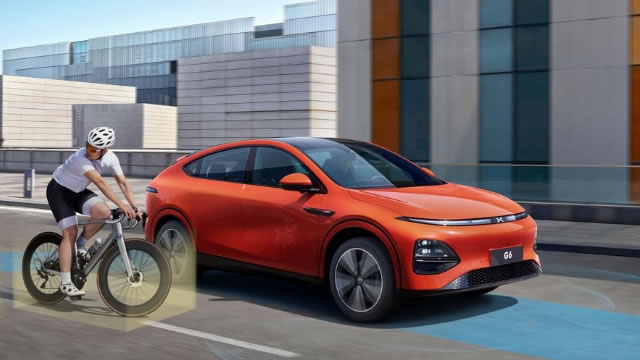
XPeng: A Weak Quarter Masks A Strong Year Ahead
XPeng had a soft first quarter where deliveries dipped and revenue growth turned negative, spooking a market already nervous about weak Chinese New Energy Vehicle sales. I expect a sharp reacceleration of vehicle sales and revenue through Q3 and Q4 2026, driven by new model releases including the GX flagship SUV and the upcoming L03/L05 SUVs. Gross margins have held firm above 20% despite rising component costs, driven by high-margin revenue from Volkswagen for VLA 2.0 and co-developed vehicles.
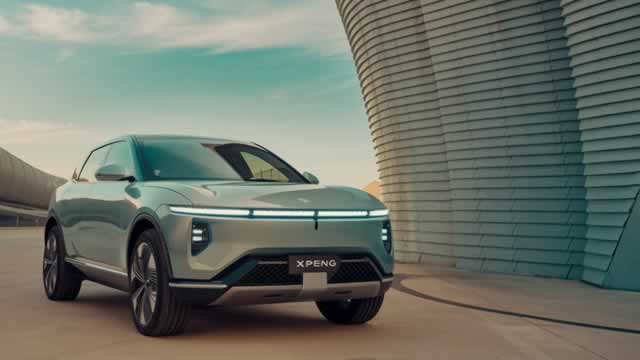
XPeng Aims to Produce Over 1,000 Robots a Month as It Plans Global Rollout
The Chinese electric-vehicle maker plans to launch its humanoid robot globally next year, as part of efforts to transform into a physical AI company.
XPeng: Strong June Deliveries Create Upside
XPeng delivered 103,295 vehicles in Q2, surpassing its guidance midpoint and showing strong Mona and GX momentum. Mona-branded deliveries accounted for 36% of June's total, while GX represented 17% of deliveries, supporting expectations for sequential gross margin gains in Q2. The company's price-to-revenue ratio of 0.6x remains higher than peers, but recent downside revaluation enhances its risk/reward appeal.
XPeng's Bottom Is Here: Demand Recovery Through New Models And Global Expansion
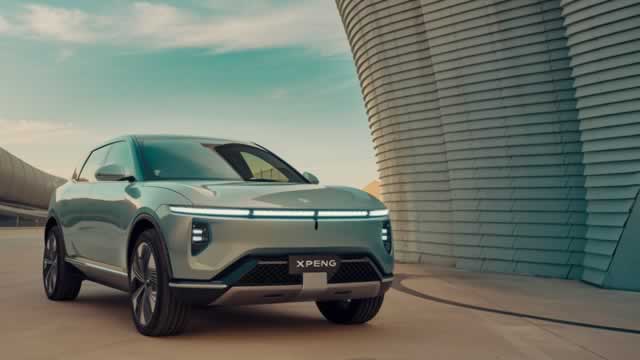
XPeng reports a much-needed demand recovery in Q2 '26, while hinting at further delivery growth in H2 '26, thanks to new model launches and the ongoing international expansion. These reasons may also be why the automaker may beat their prior FQ2 '26 revenue guidance in the upcoming earnings call, while similarly offering robust Q3 '26 delivery guidance. XPEV's prior meltdown has seemingly met a bottom at $12s, with the stock notably oversold while boasting extremely cheap valuation against the outsized top-line growth prospects.
Nio, XPeng, Li Auto, BYD, Polestar: Why are China EV stocks tumbling?
China EV stocks are in a strong freefall this year as investors remain pessimistic about their growth prospects. Nio stock slipped to $5 on Friday, down nearly 30% from its May high, and is hovering at its lowest level since March 9.
XPeng: New GX SUV A Catalyst For Growth
XPeng missed Q1 EPS estimates amid a major delivery downturn, in part aided by seasonal effects, such as Chinese New Year holidays. XPEV reverted back to a GAAP net loss in the first quarter and suffered a sequential margin drop to 12.1%. I maintain a 'Buy' rating despite delivery and margin challenges, as the company just brought a new product, the GX SUV, to market. This EV has seen strong reservation momentum.


