


Canadian Solar Inc. (CSIQ)


Canadian Solar: An Upcycle Is On The Horizon
Canadian Solar is a risky but potentially rewarding short-term investment, with a projected 20% price increase in 2025 despite competition and geopolitical risks. The company is vertically integrated and diversified, with significant exposure to China, which could face tariff issues under a Trump presidency. Valuation metrics suggest Canadian Solar is undervalued, but its lower EBITDA growth and negative free cash flow margin make it less attractive than its peers.
2 High-Risk, High-Reward Stocks I'd Buy Right Now
These stocks aren't right for everyone, but if you have a high risk tolerance, they could be worth a closer look.
2 Top Stocks We Just Bought: Here's Why (and Why You Might Want to, Too)
Deep value, a mini-turnaround, and attractive prices.
Canadian Solar's Arm Wins Deal to Supply 98MW/312MWh DC BESS in Chile
CSIQ's subsidiary, CSI Solar, through its e-STORAGE division, secures a contract to supply a 98 MW/312 MWh DC BESS to the Huatacondo project in Chile.
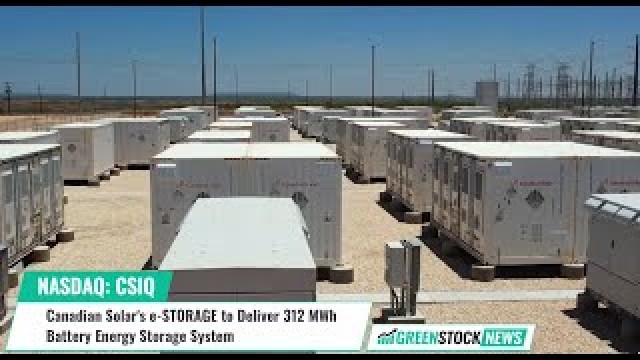
Canadian Solar's ($CSIQ) e-STORAGE to Deliver 312 MWh Battery Energy Storage System
Canadian Solar (NASDAQ: CSIQ) subsidiary, e-STORAGE, has secured an EPC contract to supply a 98 MW/312 MWh Battery Energy Storage System (BESS) project in Chile, with construction set to begin in 2025. e-STORAGE will integrate its SolBank 3.0 solution, managing all civil, mechanical, and electrical infrastructure.
Canadian Solar: Slight Growth Cannot Remove Concerns Over Operations In China
Canadian Solar stock is rated as a hold due to oversupply in China and export policy hurdles despite its solid fundamentals and expansion plans. The company manufactures solar panels and energy storage solutions, with significant production in China and growing market share globally. Subsidies and proximity to raw materials in China reduce production costs, but regulatory challenges and labor concerns impact its market.

Bargain Hunting: 2 Top Stocks to Buy Before 2025
There are some cheap stocks in the market, and here are two in particular that could be worth a closer look.

Canadian Solar: Recovery Won't Be Quick But Could Be Significant
Canadian Solar is highly cyclical, facing fierce competition and commoditization, leading to volatile stock performance despite industry growth. Recent performance has been poor with lowered guidance and a challenging macro environment. The solar panel market struggles with high interest rates, impacting demand; recovery is expected but not immediate, presenting a high-risk, high-reward scenario.

Canadian Solar (CSIQ) Q2 Earnings Beat, Revenues Fall Y/Y
Canadian Solar's (CSIQ) Q2 earnings top estimates. Its revenues decrease 30.8% year over year due to a decline in module ASPs.

Why Canadian Solar Stock Was Sliding This Week
The alternative energy specialist did not have a good second quarter. Both revenue and net income were down on a year-over-year basis, with the latter falling sharply.

Canadian Solar Inc. (CSIQ) Q2 2024 Earnings Call Transcript
Canadian Solar Inc. (NASDAQ:CSIQ ) Q2 2024 Earnings Conference Call August 22, 2024 8:00 AM ET Company Participants Wina Huang - Head of Investor Relations Shawn Qu - Chairman and Chief Executive Officer Yan Zhuang - President, Canadian Solar subsidiary CSI Solar Ismael Guerrero - Corporate Vice President and President of Canadian Solar subsidiary Recurrent Energy Xinbo Zhu - Senior Vice President and Chief Financial Officer Conference Call Participants Colin Rusch - Oppenheimer Philip Shen - Roth Capital Partners Praneeth Satish - Wells Fargo Vikram Bagri - Citi Operator Ladies and gentlemen, thank you for standing by. Welcome to Canadian Solar's Second Quarter 2024 Earnings Conference Call.

5 Low Price-to-Book Stocks Worth Adding to Your Portfolio
The P/B ratio helps to identify low-priced stocks with high growth prospects. GM, ITRI, CSIQ, ENS and GBX are some such stocks.


