


Ford Motor Company (F)




Ford Motor (F) Shows Fast-paced Momentum But Is Still a Bargain Stock
Ford Motor (F) could be a great choice for investors looking to buy stocks that have gained strong momentum recently but are still trading at reasonable prices. It is one of the several stocks that made it through our 'Fast-Paced Momentum at a Bargain' screen.
Is Ford Stock a Buy After Q2 Earnings Beat & Raised Guidance?
F's Q2 earnings beat, raised 2026 guidance, improving product mix and narrowing EV losses strengthen its investment case.
NHTSA Says 135,551 Ford Cars Pose an “Unreasonable Risk” as Recall Investigations Continue to Plague Ford Stock
The National Highway Traffic Safety Administration has escalated a long-running defect probe into roughly 135,551 Ford Fiesta, Focus, and EcoSport vehicles with 1.0L turbocharged three-cylinder engines from model years 2014 to 2021, declaring an “unreasonable risk to motor vehicle safety.
Some older Ford vehicles pose 'unreasonable' safety risks, regulators warn
The NHTSA upgraded its defect probe into 135,551 Ford Fiesta, Focus and EcoSport vehicles after 355 reports of timing belt failure causing power loss.
GM Up 61%, Ford Up 6% In Five Year Stock Price Race
It is easy to tell which huge American car company investors favor over the long term.
Ford Stock Analysis: Buy or Sell?
Automotive sales may be falling, but Ford (F -1.21%) has a new opportunity for growth.
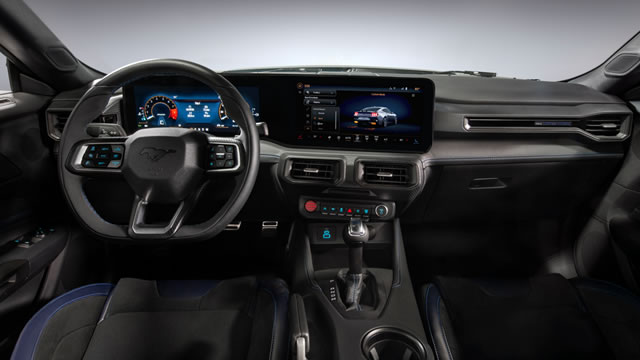
Ford Made Boring Cars Popular. It Doesn't Want Them Anymore.
The maker of the Mustang and Bronco wants a lineup of such ‘passionate' vehicles. Gone are staid family sedans, cheap hatchbacks or frumpy minivans.
GM and Ford are talking less and less about EVs
Just a few short years ago, General Motors and Ford were all-in on electric vehicles, spending billions of dollars on those efforts. Now, the two biggest American automakers are hardly talking about EVs with their investors.
GM vs. Ford Stock: Which Auto Giant Is the Better Buy After Q2 Earnings?
Following their upbeat Q2 reports, investors may be wondering whether the recent rally in GM or Ford stock has further room to run.
Ford Pro Makes Ford An Attractive Investment Despite Quarterly Stall
Ford Motor Company delivered a solid quarterly beat, with adjusted EBIT margin rising to 5.2% despite a 4% revenue decline to $48.3 billion. I remain at hold, verging on buy, as Ford Pro's moat and resilience offset industry headwinds, but recent share price strength tempers conviction. Ford raised full-year adjusted EBIT guidance to $10–$11 billion and adjusted free cash flow to $6–$7 billion, citing recovery from supply disruptions.
Ford's big-truck bet is paying off— and Wall Street is taking notice
Wall Street has long been more positive about General Motors than Ford, but that may be about to change.
Ford Q2 Earnings Beat on Pricing & Mix, 2026 EBIT & FCF View Raised
F's Q2 earnings beat as stronger pricing and product mix lifted EBIT, prompting higher 2026 profit and free cash flow guidance.


