


Firefly Aerospace Inc. (FLY)



Firefly Aerospace: Shares Have Yet To Price In Growth
Firefly Aerospace is positioned for significant growth via defense and lunar operations, with a Strong Buy rating and a $56/share price target. FLY's acquisition of SciTec enhances its missile detection and analytics capabilities, strengthening its role in the Golden Dome and FORGE defense programs. Revenue acceleration is expected from increased defense demand and lunar lander production, with profitability projected on an adjusted basis by eFY28.
Firefly Aerospace: No Profits, No Bull Case
Firefly Aerospace Inc. remains a Hold due to high valuation, persistent losses, and significant execution risk despite robust revenue growth and backlog expansion. FLY Q4 revenue surged 163% YoY to $57.7M, driven by spacecraft milestones and defense contracts, but operating expenses and cash burn also rose sharply. FLY's forward EV/sales of 5.97x and negative margins highlight expensive valuation and ongoing financial strain, with heavy CapEx and dilution concerns.
Firefly Aerospace Inc. (FLY) Q4 2025 Earnings Call Transcript
Firefly Aerospace Inc. (FLY) Q4 2025 Earnings Call Transcript
Firefly Aerospace: Successful Launch Validates Alpha, But The Real Test Is Cadence
Firefly Aerospace remains a speculative buy after a successful Mission 7 launch, despite a 42% YTD share price drop. FLY's launch success rate is only 43%, with recent mission failures weighing on investor sentiment and share price performance. My price target is $34.77, implying 50% upside, but this is reduced from prior estimates due to higher expected cash burn in 2026.
Why Fly Aerospace Stock Popped Today
Firefly Alpha Flight 7 had a successful flight last night. Issues with Flight 6 seem resolved, and Firefly's on course to fly Flight 8 next.
Aerospace Stock Surges on Successful Flight Launch
Firefly Aerospace Inc ( NASDAQ:FLY) stock is up 15.3% to trade at $23.75 at last glance, after the company announced it launched its Alpha Flight 7 successfully.
Firefly: If SpaceX Wants $1 Trillion, This Could Go Much Higher
Firefly Aerospace Inc. offers a compelling risk-reward at current levels, with the potential to triple over the next 12 months. FLY boasts a $1B+ backlog with key contracts but faces significant execution and cash burn risks as it scales. Upcoming FLY earnings will be pivotal, with a focus on Alpha launch reliability, Eclipse development, and progress in higher-margin in-space services.
Firefly Aerospace: Buy This Speculative Bet Focused On Execution
The story is about whether Firefly Aerospace Inc. can build a stable operating model not about near-term profits. FLY stock value depends on improving execution and achieving a stable and repeatable operating pace. Management has shifted toward execution, quality control and process discipline after early delays, which is critical for credibility and revenue stability.
Firefly Aerospace Stock Surges, But I Still See A Speculative Buy
Firefly Aerospace remains attractive for a speculative buy, despite a reduced price target of $37.38 and a recent 27% stock surge. Recent positives include Russell 2000/3000 index inclusion, a Volta Space partnership, and the appointment of an experienced COO from Boeing. FLY's valuation is now based on a 3x EV/Sales multiple for 2026, offering approximately 60% upside from current levels.

Firefly Aerospace Set to Report Q3 Earnings: Here's What to Expect
FLY's Q3 results may reflect strong launch and defense demand, though higher R&D costs are likely to have weighed on earnings.
Firefly Aerospace: Betting On The New Space Race
Firefly Aerospace is well positioned in the space sector, with strong NASA partnerships and a growing backlog, despite recent stock lows. FLY's solid financial footing post-IPO enables continued innovation, while the SciTec acquisition expands its presence in the national security and defense markets. Although the Alpha Flight 7 setback highlights technical risks, the company's diversified growth drivers and major contracts support a positive long-term outlook.
Will Firefly's $855M SciTec Acquisition Ignite a Stock Re-Rating?
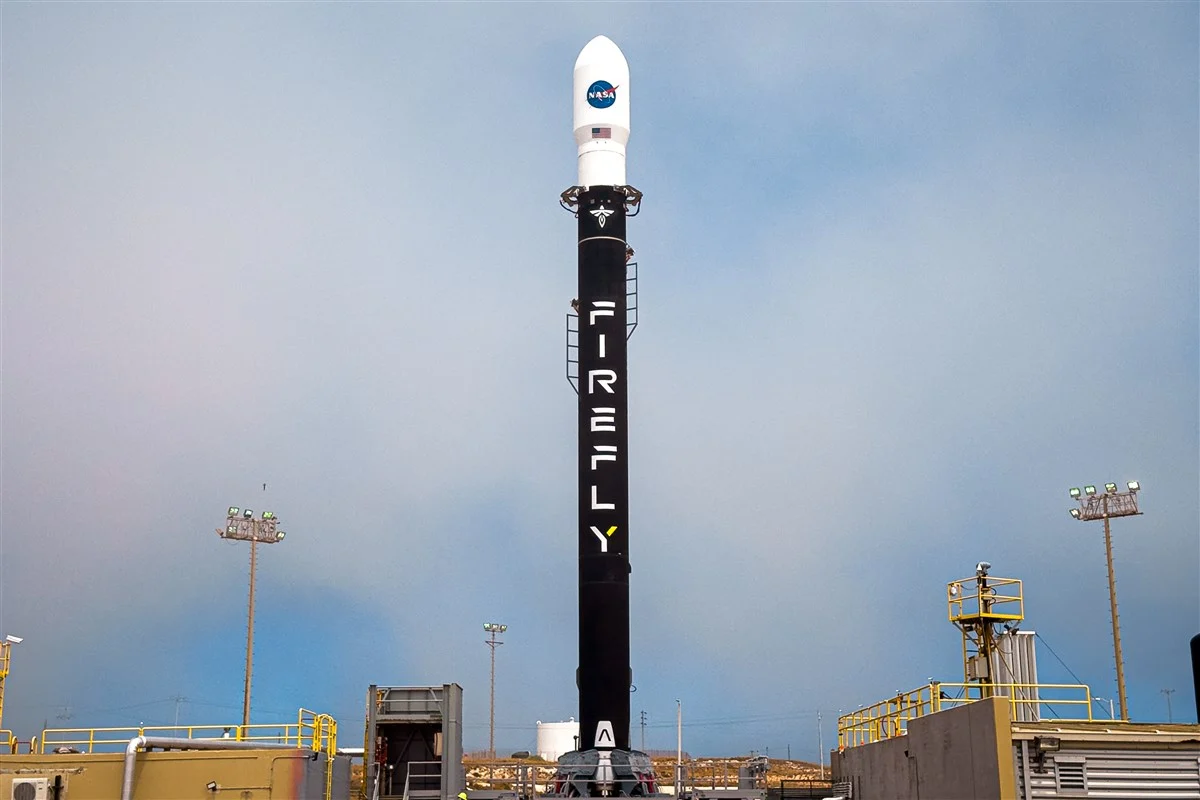
In the capital-intensive world of the modern space race, a company's success often hinges on its next launch. For Firefly Aerospace NASDAQ: FLY, however, its most significant recent maneuver happened on the ground with a landmark $855 million bet.


