



Matson: Underappreciated Compounder With Fortress Balance Sheet
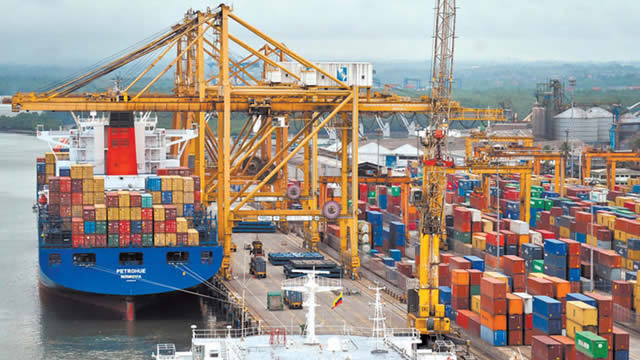
Matson's quasi-monopoly on Jones Act routes and low debt underpin my Buy rating, offering stability in a volatile shipping sector. Fleet renewal and aggressive share repurchases have structurally lifted EPS, with further gains likely as new ships launch in 2027-2028. Short-term China trade uncertainty weighs on guidance, but Matson's core US-Pacific business remains resilient and essential.
Matson Rewards Shareholders With 5.9% Hike in Quarterly Dividend
Consistent shareholder-friendly efforts of MATX to reward its shareholders through dividend hikes highlight its financial bliss.

Matson, Inc. (MATX) Q1 2025 Earnings Call Transcript
Matson, Inc. (NYSE:MATX ) Q1 2025 Results Conference Call May 5, 2025 4:30 PM ET Company Participants Justin Schoenberg - Investor Relations Matt Cox - Chairman & Chief Executive Officer Joel Wine - EVP & Chief Financial Officer Conference Call Participants Daniel Imbro - Stephens Jacob Lacks - Wolfe Research Omar Nokta - Jefferies Ben Nolan - Stifel Operator Thank you for standing by, and welcome to Matson's First Quarter 2025 Financial Results Conference Call. [Operator Instructions] As a reminder, today's program is being recorded.

Matson (MATX) Q1 Earnings and Revenues Lag Estimates
Matson (MATX) came out with quarterly earnings of $2.18 per share, missing the Zacks Consensus Estimate of $2.34 per share. This compares to earnings of $1.04 per share a year ago.

Matson (MATX) Upgraded to Buy: Here's What You Should Know
Matson (MATX) might move higher on growing optimism about its earnings prospects, which is reflected by its upgrade to a Zacks Rank #2 (Buy).

Is Matson (MATX) Stock Undervalued Right Now?
Here at Zacks, our focus is on the proven Zacks Rank system, which emphasizes earnings estimates and estimate revisions to find great stocks. Nevertheless, we are always paying attention to the latest value, growth, and momentum trends to underscore strong picks.

Matson: A Quasi-Monopoly On Sale
Matson benefits from the Jones Act, creating a regulated monopoly on West Coast US, Hawaii, Alaska, and Guam shipping routes. The company has achieved strong financial performance with minimal debt, thanks to its prudent capital allocation and reliable service. Despite US-China trade tensions, Matson's protected routes and upcoming efficient vessels mitigate risks, with China contributing only 33% of volume.

Strength Seen in Matson (MATX): Can Its 4.8% Jump Turn into More Strength?
Matson (MATX) witnessed a jump in share price last session on above-average trading volume. The latest trend in earnings estimate revisions for the stock doesn't suggest further strength down the road.
Here's Why Investors Should Buy Matson Stock Right Now
Matson's shareholder-friendly moves and robust expansion efforts are boosting the company's prospects.
Here's Why Matson (MATX) Is a Great 'Buy the Bottom' Stock Now
After losing some value lately, a hammer chart pattern has been formed for Matson (MATX), indicating that the stock has found support. This, combined with an upward trend in earnings estimate revisions, could lead to a trend reversal for the stock in the near term.

Matson, Inc. (MATX) Q4 2024 Earnings Call Transcript
Matson, Inc. (MATX) Q4 2024 Earnings Call Transcript
Matson (MATX) Q4 Earnings and Revenues Surpass Estimates
Matson (MATX) came out with quarterly earnings of $3.80 per share, beating the Zacks Consensus Estimate of $3.20 per share. This compares to earnings of $1.78 per share a year ago.


