


Micron Technology, Inc. (MU)





Can Micron (MU) Keep the Earnings Surprise Streak Alive?
Micron (MU) has an impressive earnings surprise history and currently possesses the right combination of the two key ingredients for a likely beat in its next quarterly report.
Up 500% In 12 Months, This is Where Micron Is Headed
Micron just delivered the most jaw-dropping quarter any US semiconductor company has posted this cycle, yet the stock is sliding and analysts are at war over what comes next. Where the smart money lands may surprise you.
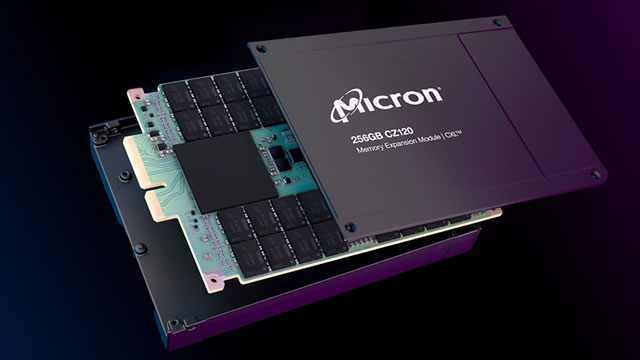
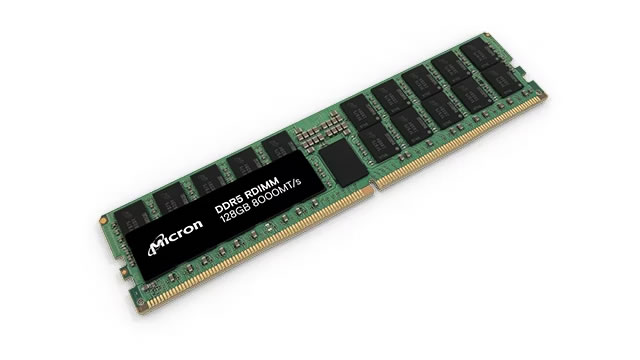
Micron Just Built One Memory Stick That Replaces Four. Is MU Stock a Buy?
Micron just pulled off a server memory breakthrough that has both AMD and Intel on board, but the revenue from it sits two fiscal years away while the stock already trades near all-time highs.
Micron: Why I'm Turning Bullish Before Huge Earnings News
Micron Technology, Inc. is approaching its next earnings report, drawing investor focus to near-term performance. Key topics include earnings expectations, potential catalysts, and how MU's results may impact its valuation. The article centers on forward-looking drivers and possible risks tied to MU's upcoming financial disclosure.
SanDisk Jumps 6% as Storage Bid Concentrates in One Name; Western Digital Rises 3%, Micron Ticks Up
SanDisk (NASDAQ:SNDK | SNDK Price Prediction) stock is rising 6% to $1,713.18 in Friday morning trading, running well ahead of every other name in the memory/storage group.
Eisman Says Buy Micron And SK Hynix. “In This Knife Fight You Want To Be The One Selling The Knives”
Steve Eisman highlighted a subscriber email arguing the safest way to play the AI buildout is owning upstream suppliers rather than betting on any one chip designer.
Earnings Growth & Price Strength Make Micron (MU) a Stock to Watch
The Zacks Focus List offers investors a way to easily find top-rated stocks and build a winning investment portfolio. Here's why you should take advantage.
Is Micron (MU) a Buy as Wall Street Analysts Look Optimistic?
When deciding whether to buy, sell, or hold a stock, investors often rely on analyst recommendations. Media reports about rating changes by these brokerage-firm-employed (or sell-side) analysts often influence a stock's price, but are they really important?
The Memory Market Could Be Entering a Golden Age for Micron
Micron has already posted five-year returns that most stocks never see in a lifetime, and Wall Street analysts are nearly unanimous that the run is not over.
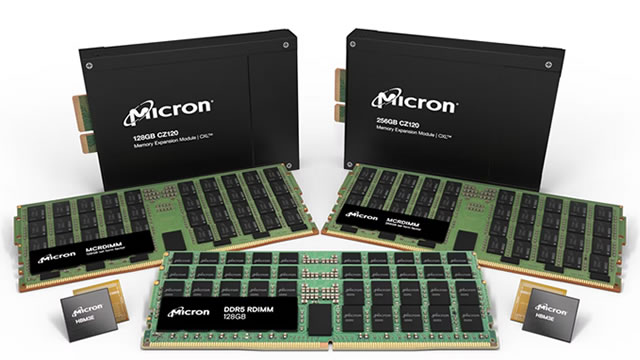
Micron Technology, Inc. (MU) is Attracting Investor Attention: Here is What You Should Know
Micron (MU) has received quite a bit of attention from Zacks.com users lately. Therefore, it is wise to be aware of the facts that can impact the stock's prospects.
Micron: Sept. 30 Could Reveal How Big Its Next Buyback Really Is
Micron Technology, Inc. remains a Strong Buy, supported by robust earnings, disciplined capital allocation, and new capacity coming online amid tight memory supply. MU's fiscal Q4 revenue guidance benefits from a 14th week; normalized run-rate and single-digit earnings multiple reinforce undervaluation. Upcoming buyback authorization size will signal management's confidence in sustained free cash flow and cycle durability, with $2.16B left on the current program.
Micron Q4 Earnings: AI Cycle Vs. Peak Margin Fears
Micron Technology, Inc. faces a pivotal FQ4 2026 earnings report amid record margin expansion and AI-driven demand. Consensus expects MU's net margin to reach a record of 70.7% in FQ4. I share the optimism for MU in the near term but remain skeptical about the sustainability in the longer term.


