


PayPal Holdings Inc (PYPL)




Is Disney or PayPal the Better Rebound Play Now?
Walt Disney (NYSE:DIS | DIS Price Prediction) and PayPal (NASDAQ:PYPL) are both trading well below their multi-year highs, attracting income-oriented investors hunting for a rebound.
Is PYPL Stock Worth Retaining in Your Portfolio for the Long Run?
PayPal benefits from rising payment volumes, Venmo growth and technology upgrades, while competition and macro risks remain key challenges.
PayPal AI Push: Will $1.5B Savings Drive Faster Growth Ahead?
PYPL targets $1.5B in AI-driven savings to fund checkout, Venmo and platform investments as it balances growth with margin pressure.
Paypal (PYPL) Advances While Market Declines: Some Information for Investors
Paypal (PYPL) closed at $45.65 in the latest trading session, marking a +1.24% move from the prior day.
PayPal Has Truly Hit The Bargain Bin (Upgrade)
PayPal is upgraded back to Buy as the stock appears to have found a long-term bottom, trading at just above 8x forward earnings. A bargain bin prospect now. Management's focus on technical simplification and Venmo integration is seen as a pivotal growth lever, though execution remains a 'show me' story. Branded checkout weakness persists, but $1.5 billion in cost savings could fund growth initiatives and improve Venmo-PayPal integration.
PayPal's BNPL Push: Will It Drive Higher Checkout Basket Sizes?
PYPL expands BNPL to strengthen branded checkout, attract customers and boost merchant sales as strong adoption leaves room for further growth.
Investors Heavily Search PayPal Holdings, Inc. (PYPL): Here is What You Need to Know
Recently, Zacks.com users have been paying close attention to Paypal (PYPL). This makes it worthwhile to examine what the stock has in store.
PayPal's Valuation Is Absurd
PayPal remains a deeply discounted growth machine, trading at low valuation multiples despite robust top-line expansion. PYPL reported Q1 2026 revenue of $8.35B (+7.2% YoY) and record-high active accounts and payment volumes. Profitability declined YoY due to higher transaction expenses and investment impairments, but management continues aggressive share buybacks and initiated a dividend.
PayPal Secures EPC Seat to Help Guide Future of European Payments
PayPal said Thursday (July 2) that it has secured a seat at the table to influence the future of payments in Europe by joining the European Payments Council (EPC). EPC brings together organizations that are involved with the rules, standards and infrastructure underpinning European payments.
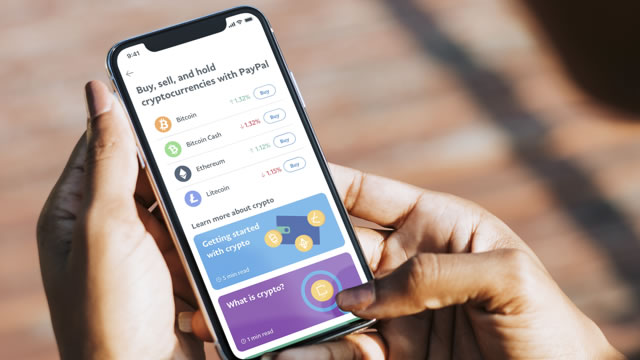
Paypal (PYPL) Stock Sinks As Market Gains: Here's Why
Paypal (PYPL) closed the most recent trading day at $43.18, moving 2.7% from the previous trading session.
PayPal's PYUSD Push: Can Stablecoins Improve Merchant Payments?
PYPL's PYUSD expansion into 70 markets and its new Payment Services & Crypto business line reshape faster, lower-cost merchant payments.
PayPal's Total Payment Volume: What's Fueling Double-Digit Growth?
PYPL's TPV climbs 11% to $464B in Q1 2026 as Venmo, PSP momentum, debit cards and branded experiences help drive broad-based payment growth.


