



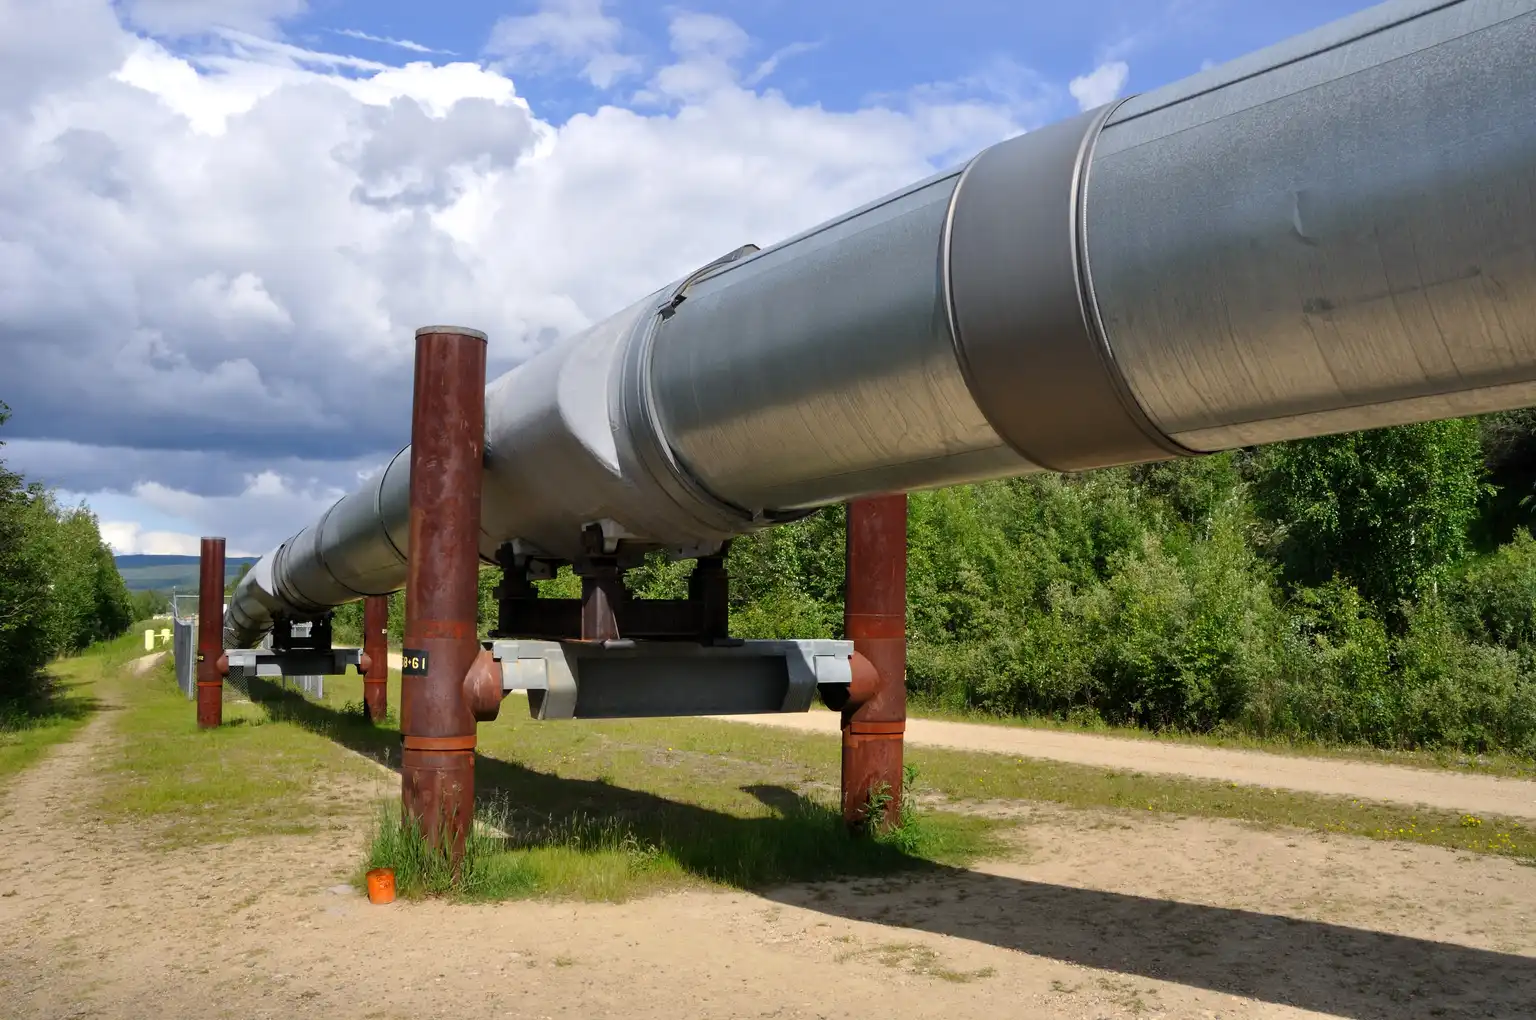
Tenaris: Betting On The Backbone Of The Oil Network
Tenaris S.A. is a global, but under-followed leader, in steel pipe manufacturing for the oil and gas industry. It also has a growing exposure to geothermal, hydrogen, and carbon capture storage applications. The company showcases a robust balance sheet and extremely lean and efficient operations that make it generate billions in free cash flow in any market condition.
Tenaris (TS) Reports Q2 Earnings: What Key Metrics Have to Say
While the top- and bottom-line numbers for Tenaris (TS) give a sense of how the business performed in the quarter ended June 2024, it could be worth looking at how some of its key metrics compare to Wall Street estimates and year-ago values.
Tenaris: Up And Down We Go - And Now A Buy
Tenaris is a top player in the energy servicing sector, controlling nearly half of the global OCTG market. Italy-based with listings in Milan and NYSE, making it an attractive European investment potential. Rig Direct program enhances customer relationships and production efficiency, adding considerable value to the company.

Tenaris: Holding Was The Right Choice, Upgrading To A Buy (Rating Upgrade)
Tenaris is an attractive company in the energy servicing sector. The company has recently dropped quite a bit, and is now more attractive than a few months ago. There's upside to be had, despite the company's relatively flat growth outlook for 2024 and 2025. I am upgrading the company to a "BUY" here, from a "HOLD".


