


Sonos Inc. (SONO)




Why Is Sonos (SONO) Up 4.6% Since Last Earnings Report?
Sonos (SONO) reported earnings 30 days ago. What's next for the stock?
How Sonos Q4 Guidance Balances Revenue Growth Against Memory Inflation
Sonos expects Q4 revenue growth to stay intact, but a $35 million memory-cost hit could sharply pressure gross profit and adjusted EBITDA.
Is Sonos Stock Worth Buying as Growth Improves but Margin Risks Rise?
Sonos is regaining revenue momentum as new products and overseas growth boost demand, but rising memory costs threaten margins into fiscal 2027.
Sonos Q3 Earnings Beat on Broad-Based Growth and Cost Control
SONO topped fiscal Q3 estimates as speaker demand, overseas growth and cost control lifted sales, margins and adjusted EBITDA.
Sonos, Inc. (SONO) Q3 2026 Earnings Call Transcript
Sonos, Inc. (SONO) Q3 2026 Earnings Call Transcript
Sonos Q3 Earnings Call Highlights
Sonos NASDAQ: SONO reported third-quarter fiscal 2026 revenue of $375 million, up 9% from a year earlier and near the high end of its guidance range, as growth in Asia-Pacific and Europe, the Middle East and Africa offset more modest gains in the Americas.
Sonos (SONO) Q3 Earnings and Revenues Beat Estimates
Sonos (SONO) came out with quarterly earnings of $0.27 per share, beating the Zacks Consensus Estimate of $0.24 per share. This compares to earnings of $0.19 per share a year ago.
Sonos (SONO) Soars 5.9%: Is Further Upside Left in the Stock?
Sonos (SONO) was a big mover last session on higher-than-average trading volume. The latest trend in earnings estimate revisions might not help the stock continue moving higher in the near term.
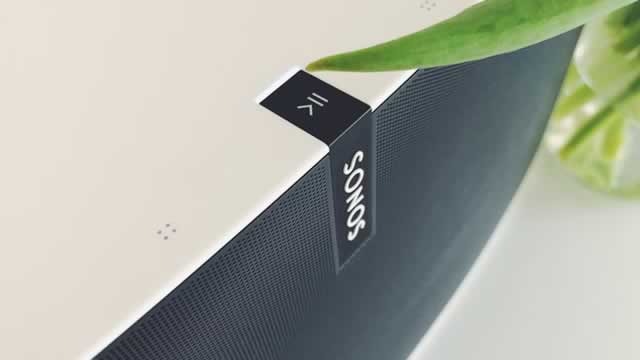
The new Sonos Play has become my go-to desk and kitchen speaker
I work from home, so I typically listen to audio through headphones or AirPods. But I've always wanted a desk speaker that doesn't take up too much space, which made the new Sonos Play a fitting first Sonos product to review.
Sonos: Despite Memory Spike, Sonos Excels At What It Can Control
Sonos faces gross margin pressure from surging memory prices, but I reiterate my 'Buy' rating, viewing recent downside as short-term noise. SONO is actively mitigating memory cost headwinds via tariff refunds, engineering redesigns, and disciplined opex management, without resorting to price hikes. Strong Q2 results: revenue grew 8% y/y to $281.5 million, beating expectations and supporting management's confidence in accelerating growth for 2H FY26.
Sonos' Reports Q2 Loss, Revenues Beat Estimates, Stock Jumps
SONO posts Q2 revenue growth and narrower loss, as improving trends and strong execution mark a key turnaround for SONO.
Sonos, Inc. (SONO) Q2 2026 Earnings Call Transcript
Sonos, Inc. (SONO) Q2 2026 Earnings Call Transcript


